Alibaba Plans to Spin Off T-Head for Hong Kong IPO: Billions in Revenue, 560,000 Chips Shipped, Yet a $66 Billion Valuation Gap?


- Key Takeaways: Alibaba's spin-off of T-Head for an independent listing in Hong Kong has been confirmed by the Stock Exchange of Hong Kong. With annualized revenue exceeding RMB 10 billion and cumulative AI chip shipments in the hundreds of thousands, the move marks the shift of domestic computing power from a technology narrative to a commercialization validation stage. However, the valuation divergence between $20 billion and $86 billion highlights differing market perceptions of its revenue structure, profitability, and growth sustainability.
- Key Elements:
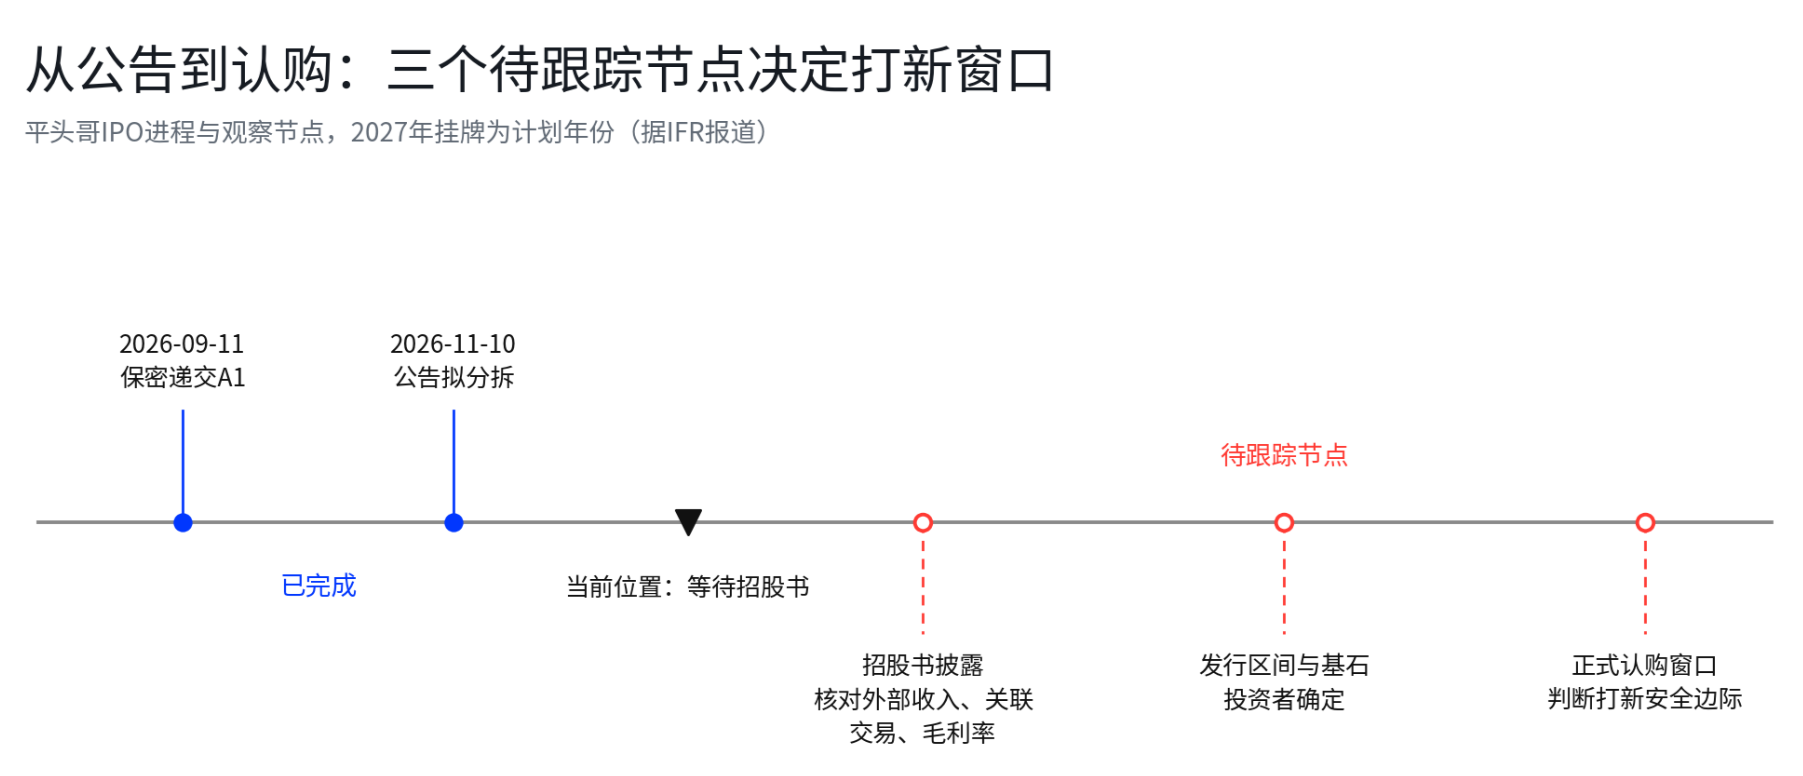
- The Stock Exchange of Hong Kong has confirmed that Alibaba may spin off T-Head under Practice Note 15. The company confidentially submitted its Form A1 on September 11, 2026, seeking a Main Board listing, with fundraising rumored at $2 billion to $3 billion and a target listing in 2027.
- T-Head's annualized revenue exceeds RMB 10 billion, with cumulative shipments of its Zhenwu-series AI chips surpassing 470,000 units. As of June 2026, it served more than 650 enterprise customers, with external commercialization customers accounting for over 60%.
- Its product line spans AI chips, server CPUs, SSD controllers, smart NICs, interconnect chips, and RISC-V IP. Cumulative shipments of the XuanTie series exceed 6 billion units, with more than 400 ecosystem partners.
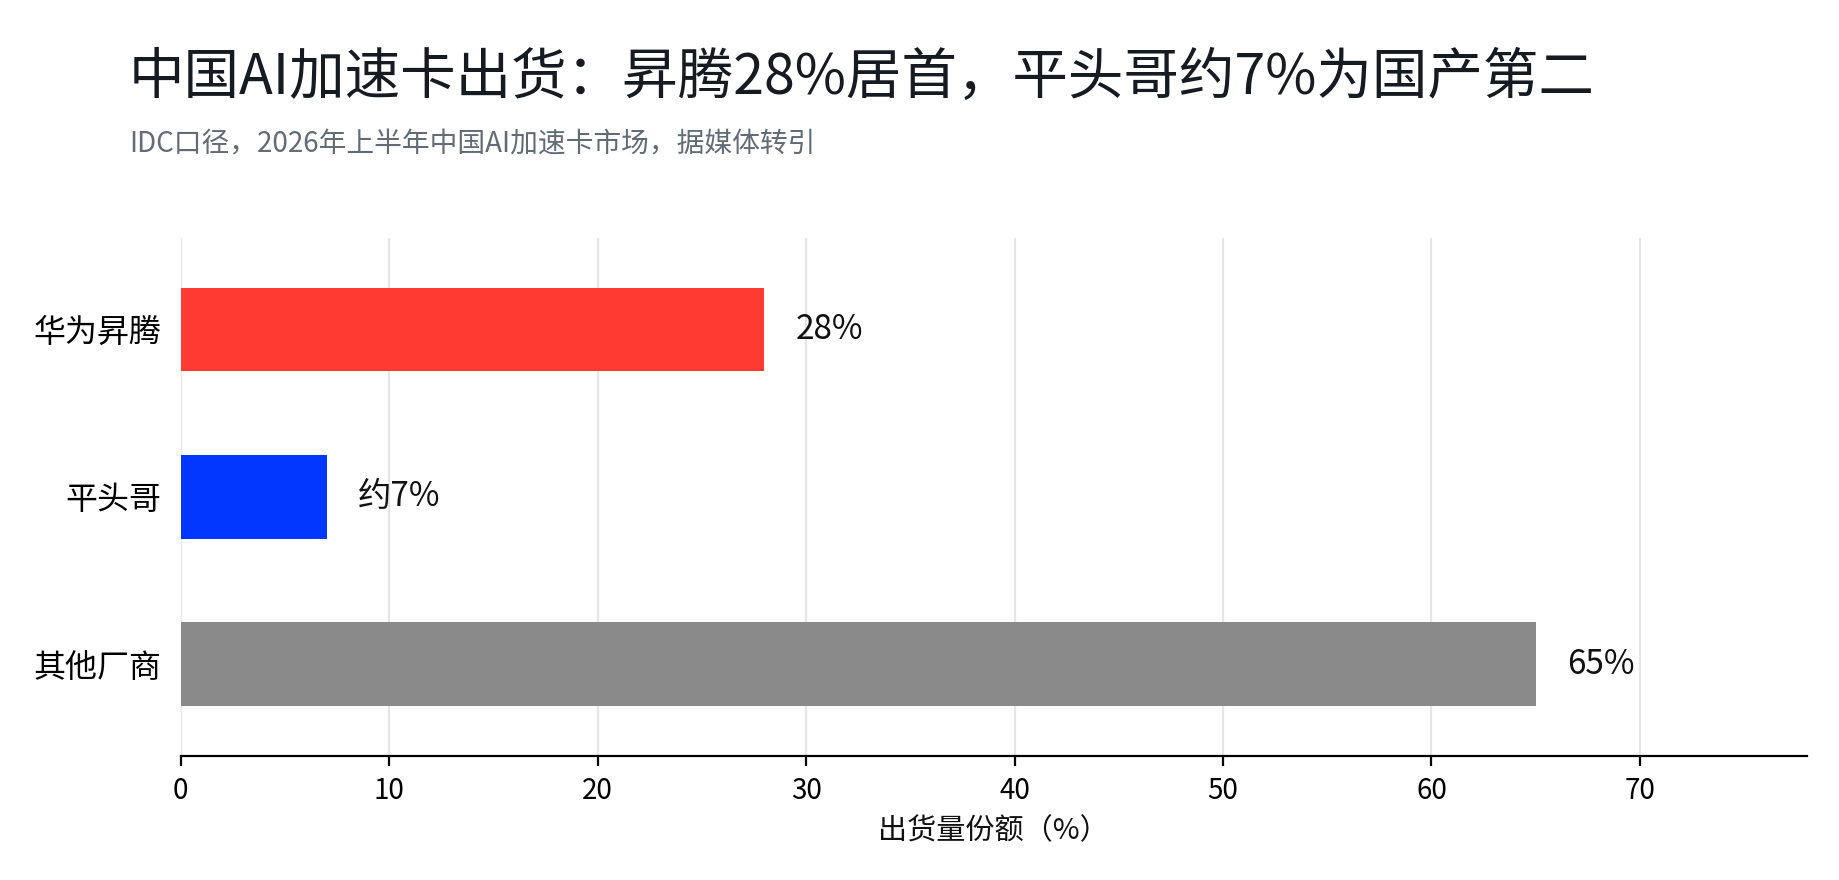
- According to IDC data, in the first half of 2026, T-Head held about a 7% shipment share of China's AI accelerator card market, ranking second among domestic players, behind only Huawei's Ascend at 28%.
- The next-generation Zhenwu V900 boosts memory to 216GB and interconnect bandwidth to 1,200GB/s, with the company claiming three times the computing power of the previous generation. It is scheduled for mass production in Q1 2027 and is a key validation point for the valuation growth thesis.
- Institutional valuation ranges diverge by $66 billion: professional institutions estimate roughly $20 billion to $30 billion, JPMorgan $25 billion to $62 billion, and Morgan Stanley about $28 billion to $86 billion.
- The prospectus needs to focus on verifying five items: the share of revenue from external customers, external revenue growth, V900 mass production progress, gross margin and R&D investment, and the offering valuation and issue price.
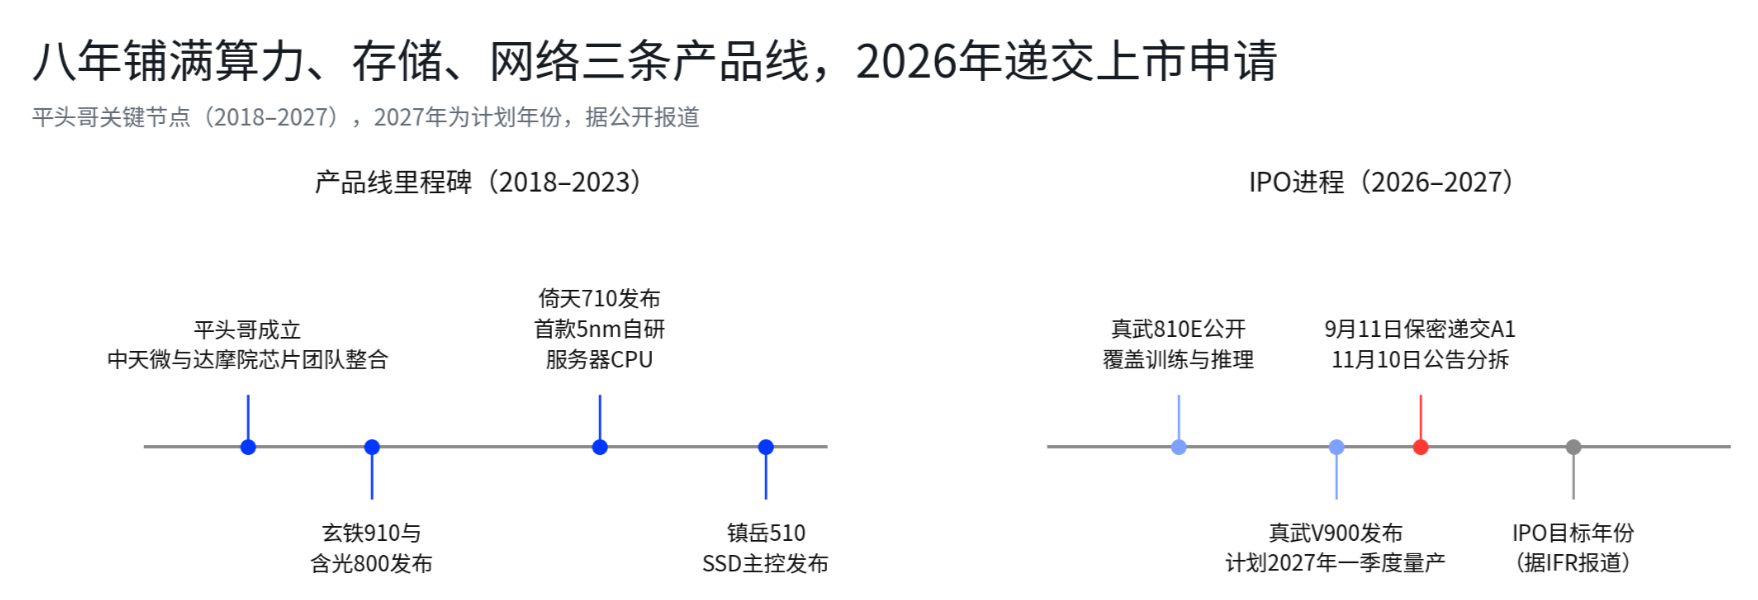
On the evening of November 10, Alibaba-W (09988.HK) announced that it plans to spin off its wholly-owned subsidiary T-Head (Shanghai) Technology Co., Ltd. for a separate listing on the Main Board of the Hong Kong Stock Exchange, and the Exchange has confirmed that the spin-off may proceed; T-Head had previously submitted its A1 listing application on a confidential basis on September 11. From its founding to preparing for a listing, T-Head has taken about 8 years.
The company, named after the honey badger, was initially positioned as a chip design firm, and today its products cover AI computing, server CPUs, SSD controllers, smart NICs, interconnect chips, and RISC-V processor IP. The company's annualized revenue exceeds 10 billion yuan, and its Zhenwu series AI chips have moved from product validation into large-scale commercialization. The key questions for T-Head's IPO now come down to "how much the products can sell, how independent the customers are, how much profit can be retained, and how much valuation the capital markets are willing to assign."
For the Hong Kong stock market, this is also an event worth adding to the watchlist in advance: if the listing ultimately goes through, the Hong Kong market's domestic computing power sector will gain a new chip company covering computing power, storage, and networking, and the market will also gain a more direct pricing reference for domestic AI chips.
1. The Exchange Confirms the Spin-off, T-Head's IPO Enters a Substantive Advancement Phase
The information that has landed so far is relatively clear. Alibaba submitted a spin-off proposal under Practice Note 15 of the HKEX Listing Rules, and the Exchange has confirmed that the spin-off may proceed. T-Head submitted its A1 application form on a confidential basis on September 11, 2026, planning to apply for the listing and trading of H shares on the Main Board of the Hong Kong Stock Exchange, and intends to conduct a global offering of H shares, including a Hong Kong public offering and a placing to institutional and professional investors.
This spin-off does not involve "selling off" T-Head; after the separate listing, Alibaba will maintain control, and T-Head will remain a subsidiary of Alibaba. This has two direct implications for the company itself: on the one hand, after the separate listing, the chip business's revenue, customers, R&D investment, and profitability will receive clearer capital market pricing; on the other hand, internal ecosystems such as Alibaba Cloud and Qwen can still provide application scenarios and computing power demand, so T-Head is not completely detaching from its original ecosystem and starting over.
As for the size of the fundraising and the timing of the listing, market information remains at the expectation stage. According to IFR, the offering plans to raise US$2 billion to US$3 billion, with a target listing in 2027. What can now be confirmed is that "the IPO process has been initiated"; the offering size, offering price, and listing valuation are not yet final results. The next document that will truly determine the value of subscribing to the IPO is still the prospectus.
2. Ten Billion in Revenue Is Not Just a Story: Zhenwu Chips Have Entered Large-Scale Commercialization
The most valuable change at T-Head is that its business has moved from "chip R&D" to "chip sales." According to disclosures on the company's earnings call, T-Head's annualized revenue exceeds 10 billion yuan, and cumulative shipments of the Zhenwu series AI chips have exceeded 470,000 units; according to media statistics, as of April 2026, cumulative shipments of the Zhenwu series totaled about 560,000 units, and as of June 2026 it had served more than 650 enterprise customers, with external commercial customers accounting for more than 60%.
If this commercialization trend can be further verified in the prospectus, then T-Head will be clearly different from early-stage chip companies that rely solely on technology stories to support their valuations: it already has revenue, shipments, and customers, and has entered a real procurement cycle.
The product side is also continuing to iterate. Public information shows that the Zhenwu 810E is equipped with 96GB HBM2e memory and 700GB/s inter-chip interconnect bandwidth, and has already been used in some of Alibaba Cloud's 10,000-card clusters for Qwen large model training and inference. The next-generation Zhenwu V900, released in September 2026, increases memory to 216GB and inter-chip interconnect bandwidth to 1200GB/s; the company officially claims computing power reaches three times that of the previous generation and plans mass production in the first quarter of 2027.
For IPO valuation, the significance of the V900 lies in its growth logic: if the V900 can be mass-produced as planned and generate revenue, T-Head will have an opportunity to prove that its growth does not depend entirely on existing products, but can continuously raise its revenue ceiling through new-generation chips. This will directly affect the valuation center the market assigns to it.
3. From AI Chips to RISC-V, What T-Head Sells Is a Product System
Another advantage of T-Head is that its business is not limited to AI accelerator chips. Currently, the company's data center products cover the Zhenwu series AI chips, Yitian 710 server CPU, Zhenyue 510 enterprise-grade SSD controller, Panmai smart NIC, and ICN interconnect chips; on the terminal side, there is also the XuanTie series RISC-V processor IP, with cumulative shipments exceeding 6 billion units and more than 400 ecosystem partners.
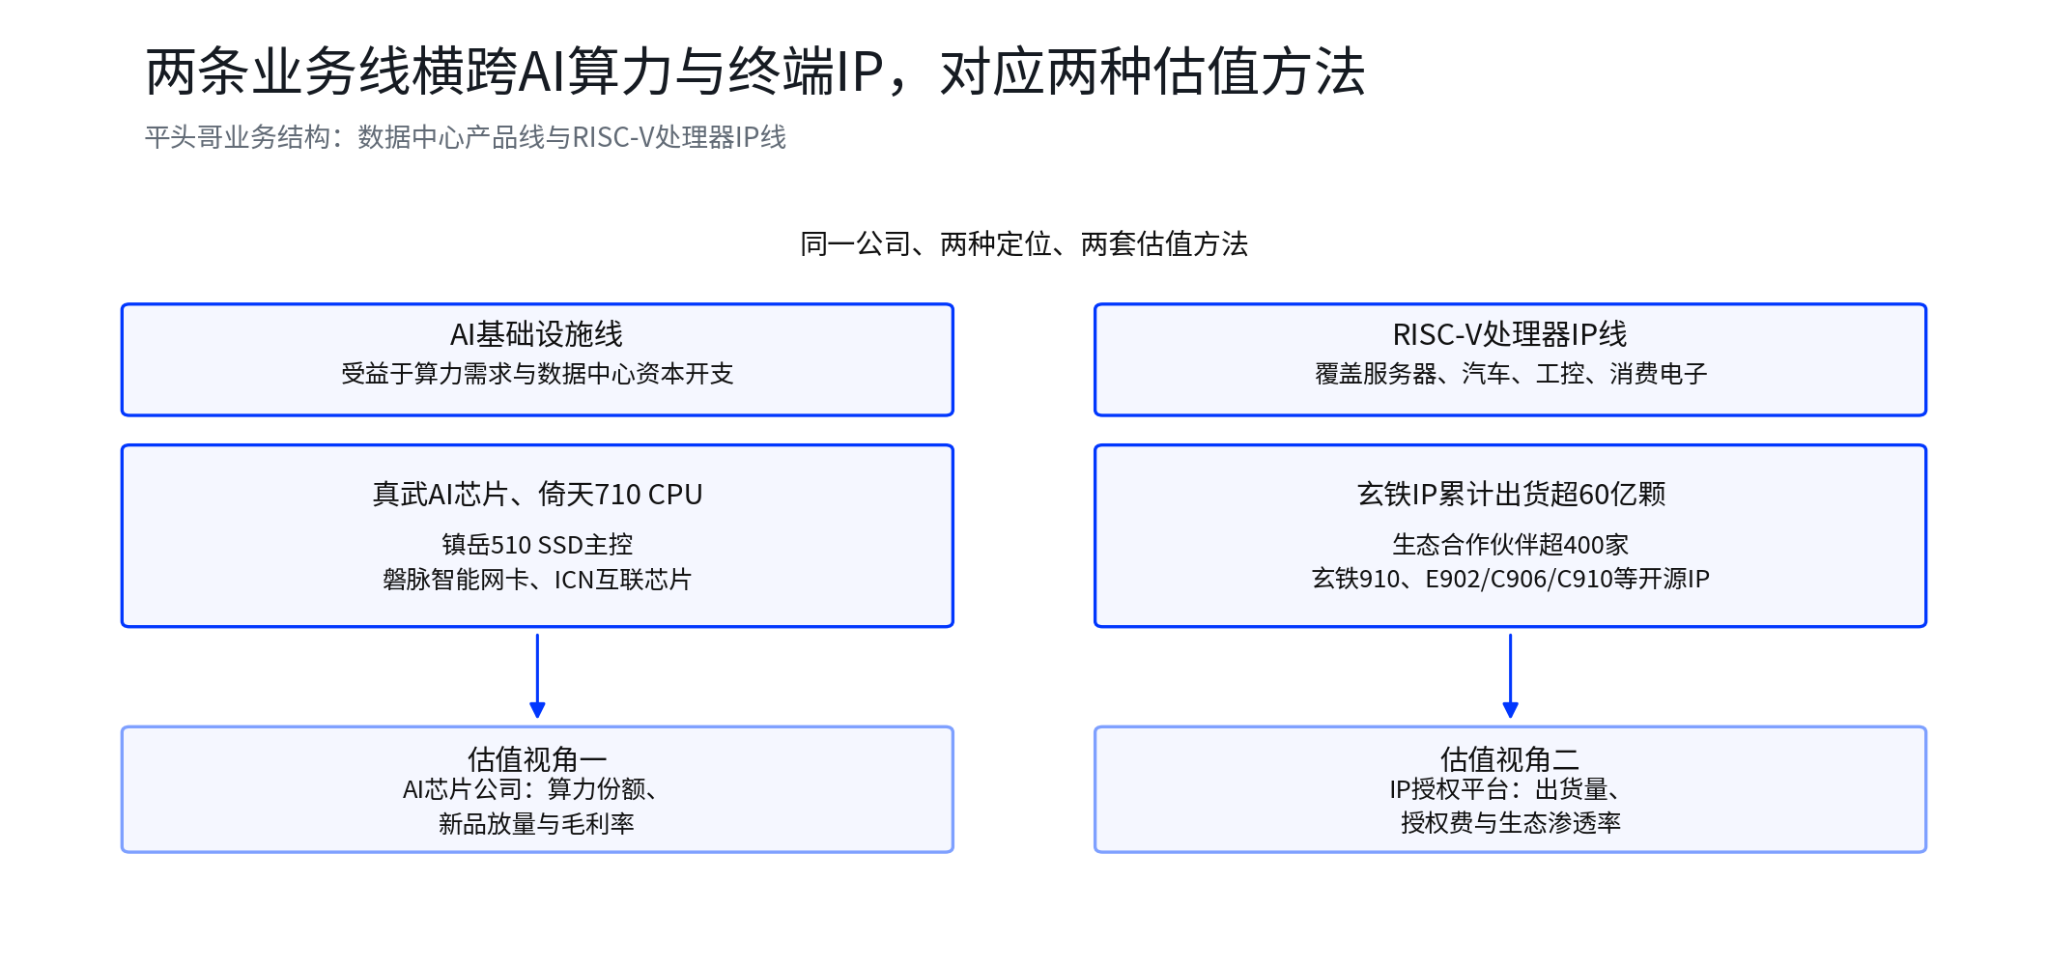
This means T-Head's business model actually spans two lines: one is AI infrastructure, directly benefiting from computing power demand and data center capital expenditure; the other is RISC-V processor IP, covering broader terminal markets such as servers, automotive electronics, industrial control, and consumer electronics.
For Hong Kong stock investors, this business structure is worth noting because it determines whether T-Head will ultimately be treated by the market as an AI chip company, a comprehensive chip platform, or a computing power infrastructure asset within the Alibaba ecosystem. Different positioning corresponds to different valuation methods.
On the AI infrastructure line, third-party data already provides a reference for market position. According to IDC data (as cited by media), in the first half of 2026 in China's AI accelerator card market, T-Head held about a 7% shipment share, ranking second among domestic players, behind only Huawei Ascend at 28%.
4. The Real Valuation Mystery: US$20 Billion to US$86 Billion, Why a US$66 Billion Gap?
Current market expectations for T-Head's valuation vary widely. According to 21st Century Business Herald, valuation ranges given by professionals at institutions are about US$20 billion to US$30 billion; JPMorgan's estimate in January this year ranged from US$25 billion to US$62 billion; another media report said Morgan Stanley's valuation range was about US$28 billion to US$86 billion. The difference between the highest and lowest is US$66 billion.
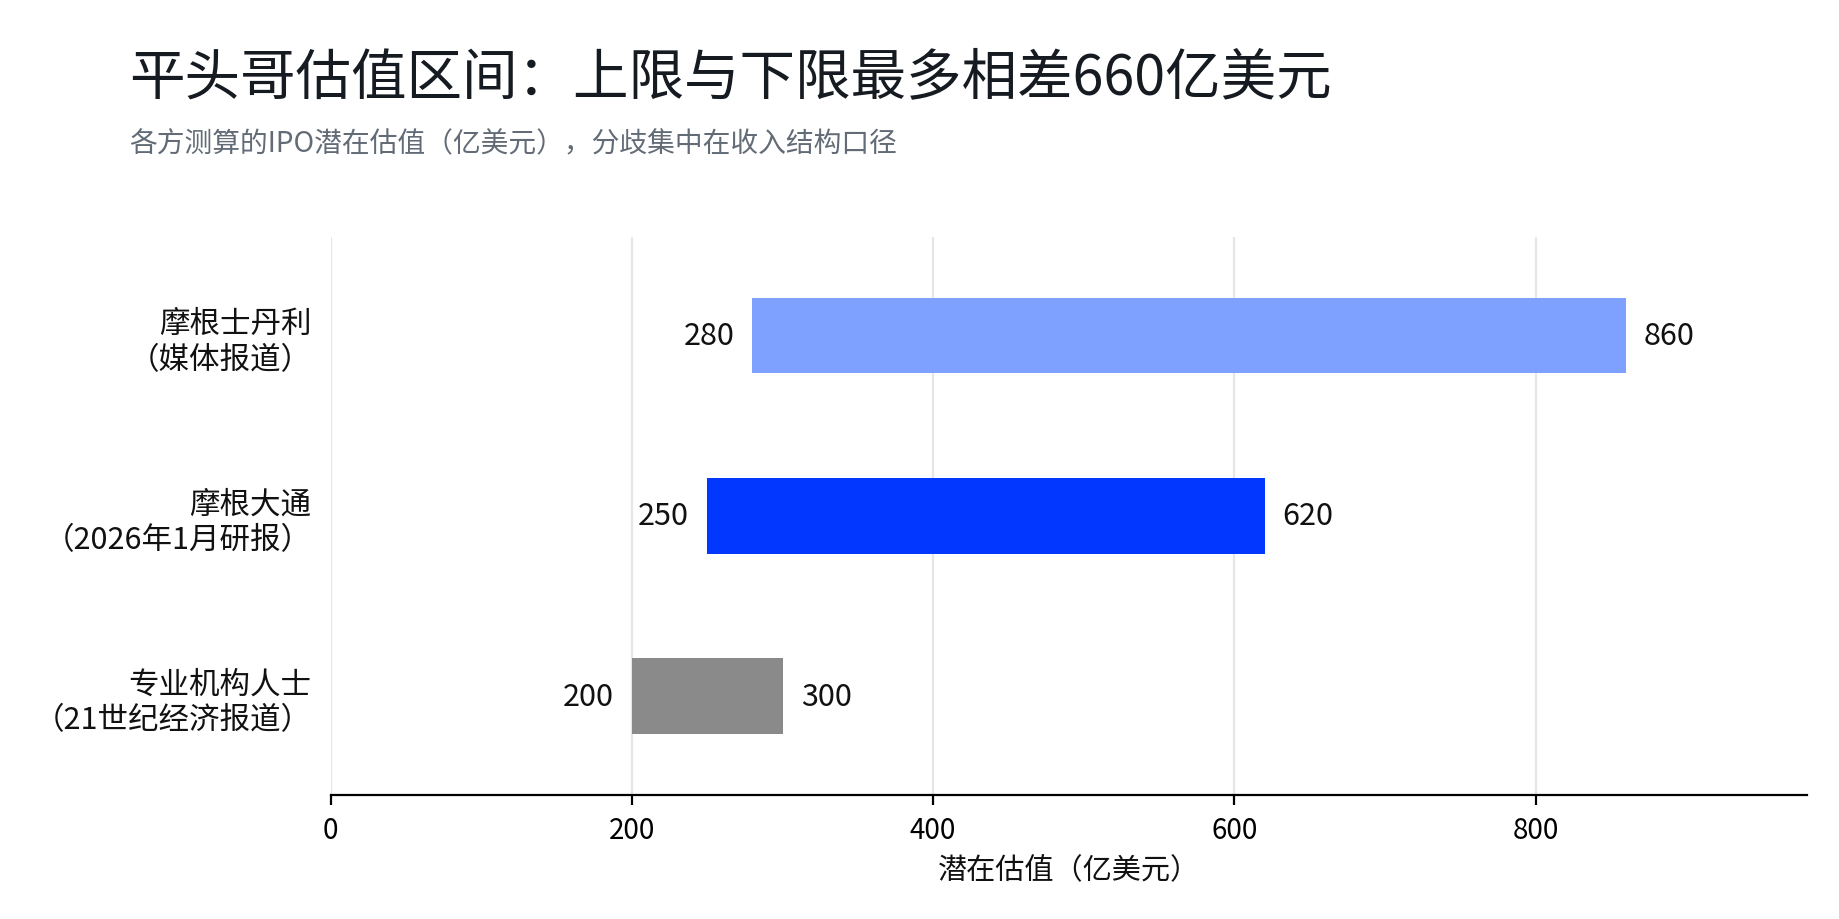
For a single company, this has gone beyond the normal calculation error of a few hundred million dollars and represents a clear divergence in the capital market's understanding of the business model. This divergence does not mean the market does not know how much T-Head is worth; the real problem is that several key accounts are still missing.
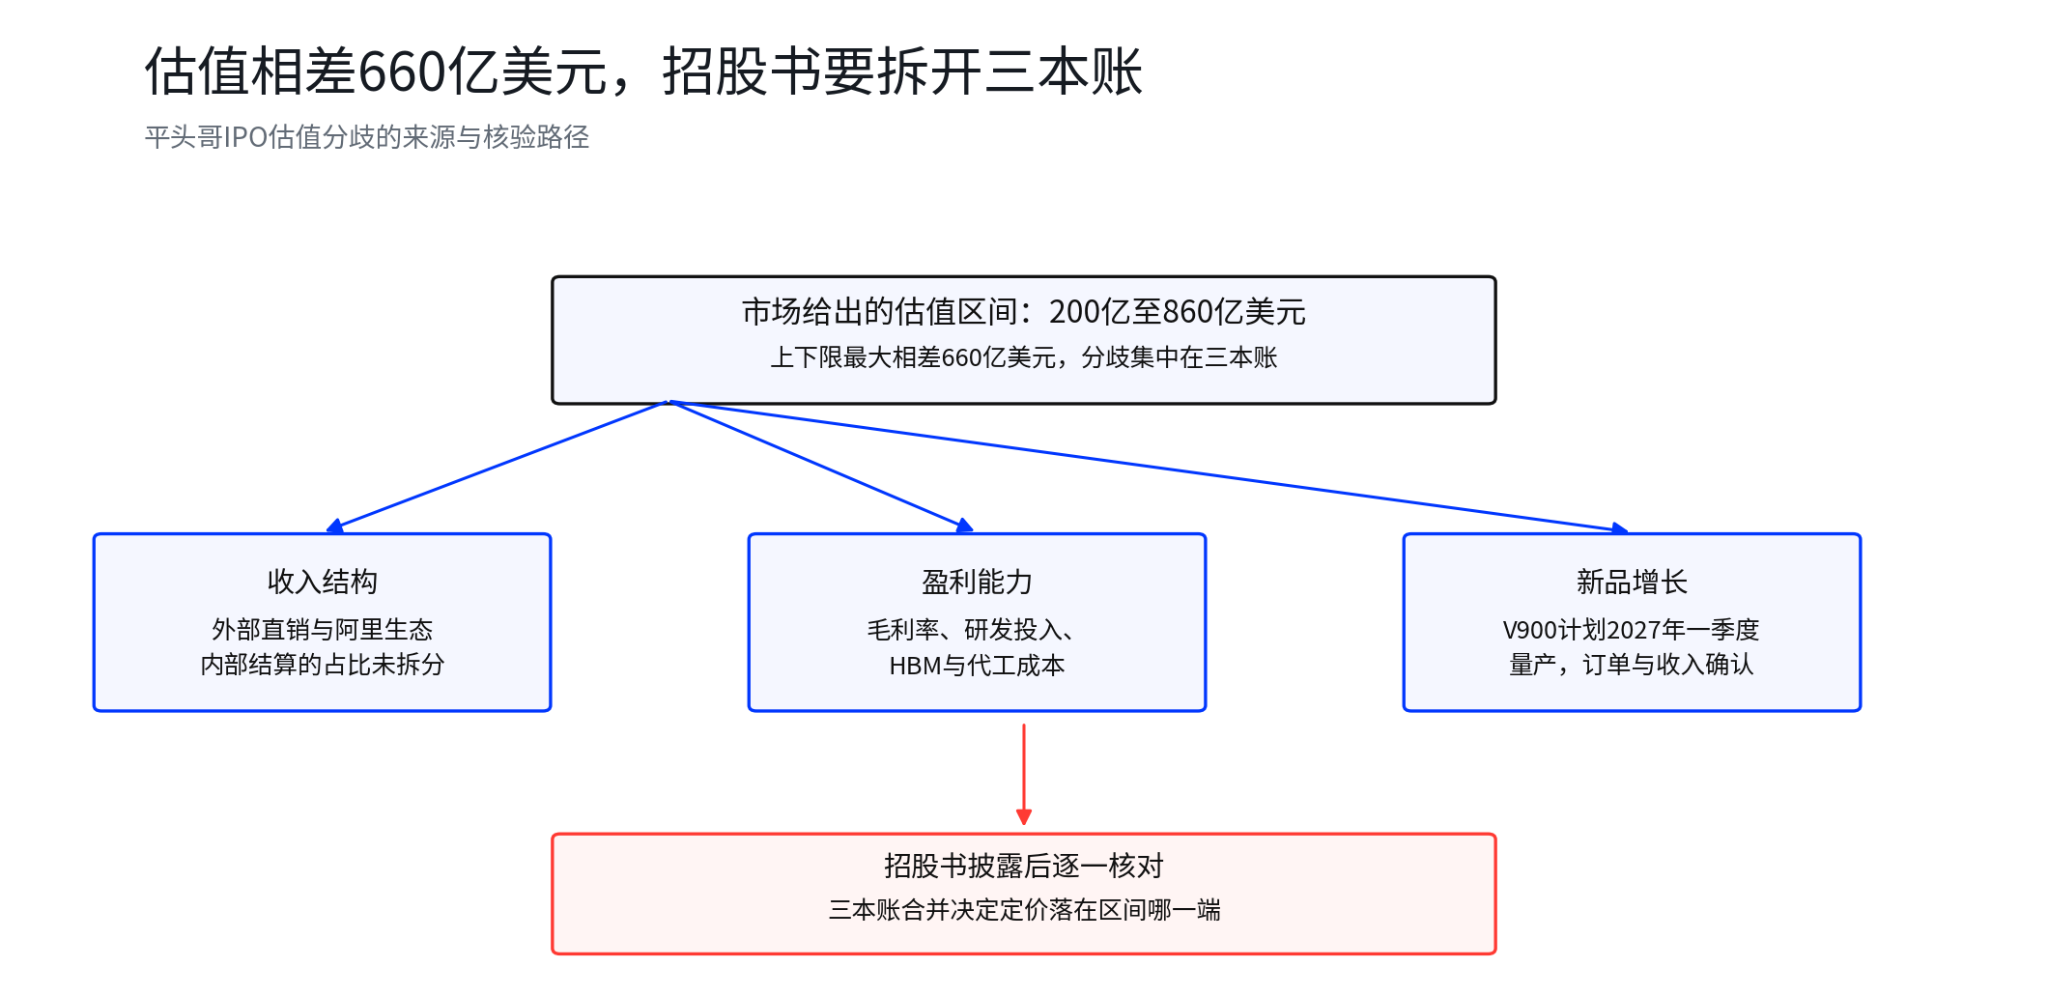
The first is the revenue structure. T-Head's annualized revenue already exceeds 10 billion yuan, but how much of that comes from genuine external customers and how much from within the Alibaba ecosystem still lacks complete public data.
The second is profitability. Revenue growth for chip companies does not automatically equal high profit; R&D investment, wafer manufacturing, advanced packaging, HBM and other supply chain costs all affect final gross margin and net profit. The market is willing to assign a high valuation on the premise that high revenue can gradually translate into sustainable profit.
The third is new product growth. If the V900 is smoothly mass-produced in the first quarter of 2027 and quickly generates orders and revenue, what the market sees will be a product curve still expanding upward, and revenue scale could exceed the current 10 billion yuan.
Therefore, what is truly worth reading in the prospectus is the financial and customer structure cards that could push the valuation from US$20 billion to US$86 billion.
5. Before the Prospectus Is Disclosed, Look at These 5 Numbers First: They May Determine How Much T-Head Is Worth
After the prospectus is officially disclosed, investors can focus on verifying the following five items.
1. Share of revenue from external customers. Currently available public information shows that external commercial customers account for more than 60%. If this figure continues to rise, it means T-Head's dependence on orders from within the Alibaba ecosystem is declining and its independent commercialization capability is strengthening; if it remains at a low level for a long time, more attention should be paid to related-party transactions and revenue quality.
2. Growth rate of external revenue. Total revenue growth is important, but external revenue growth is more important. If external customer revenue grows consistently faster than the overall business, it shows that T-Head is moving from being a chip company within the Alibaba ecosystem toward becoming a market-facing chip supplier.
3. Mass production progress of the Zhenwu V900. The current official plan is mass production in the first quarter of 2027. For IPO subscription valuation, the V900 is not just a product launch event, but also an important validation point for whether the next round of revenue growth can be delivered. Mass production, shipments, customer adoption, and revenue recognition are the complete chain truly worth tracking going forward.
4. Gross margin and R&D investment. The chip industry cannot be judged by revenue alone. If revenue grows rapidly while gross margin improves and R&D investment as a share of revenue gradually declines, earnings elasticity will clearly strengthen; conversely, if revenue growth is achieved mainly through high R&D investment and high supply chain costs, it will be more difficult for the market to assign a high valuation.
5. Offering valuation and offering price. This is the most direct question for Hong Kong IPO subscription. No matter how good the company is, an excessively high offering price will compress the margin of safety for IPO subscription; if fundamentals continue to improve while the offering valuation is relatively restrained, it is easier to form positive expectations.
Therefore, once the subscription stage truly begins, it is also necessary to look at the offering market capitalization, fundraising size, offering ratio, peer valuations, and the company's profit forecasts together; looking only at valuation figures circulating in the market is not enough.
6. The IPO Has Not Yet Reached the Subscription Window; What Should Hong Kong Stock Investors Watch Now?
T-Head is still in the IPO advancement stage, and the formal offering and final issuance terms still need to wait for subsequent documents. Therefore, the more appropriate action now is to build a watchlist in advance; the offering price has not yet been determined, so there is no question of trading ahead of time.
The most direct direction to watch is the domestic computing power sector in the Hong Kong stock market. If the market begins to trade T-Head's IPO expectations in advance, related areas such as domestic AI chips, servers, semiconductor manufacturing, packaging and testing, storage, and data center infrastructure may all see sentiment spillover.
But this spillover needs to distinguish between two types of signals: if trading volume expands, leaders strengthen in sync, and industry chain fundamentals are also supported by order or price changes, it is usually a higher-quality sector move; if it is only a one-day pulse driven by IPO news, it is more suitable for observation and not for simply chasing highs.
For Hong Kong IPO subscription users, what is truly worth waiting for is the following three milestones: disclosure of the prospectus, determination of the offering range and valuation, and formal subscription. At the formal offering stage, judging whether it is worth participating based on the offering valuation, cornerstone investors, public offering ratio, company profitability, and peer valuations will be more meaningful than guessing the offering price now.
7. Why Is This IPO Worth Continued Tracking and Attention?
The significance of T-Head is not just that another subsidiary of Alibaba is listing. If it ultimately succeeds in landing on the Hong Kong stock market, the market will gain a domestic chip platform company covering AI computing power, server CPUs, storage controllers, network interconnect, and RISC-V IP at the same time.
More importantly, as revenue, customers, shipments, and R&D investment gradually become public, the market can begin to use the same capital market language to compare the commercialization capabilities of domestic computing power companies. For investors, this comparability itself is valuable.
In the past, the market traded more on the industrial trends and thematic expectations of domestic computing power; after the listing, investors can further compare who has faster revenue growth, who has more external customers, who has higher gross margin, and who can turn R&D investment into sustained orders. This is also the most noteworthy aspect of T-Head's IPO: it may further move domestic computing power from thematic trading toward fundamental pricing.
Final Thoughts: Look at Company Quality First, Then the Offering Price
From its founding in 2018 to now having annualized revenue exceeding 10 billion yuan, cumulative AI chip shipments of hundreds of thousands of units, and reaching the doorstep of a Hong Kong IPO, T-Head has already completed an important step from technology R&D to commercialization validation. But the real reason an IPO is worth subscribing to should not just be labels such as "under Alibaba," "domestic computing power," or "AI chips."
What matters most next is whether, after the prospectus breaks down the accounts, T-Head's external revenue, customer structure, gross margin, R&D investment, and V900 mass production can jointly support a higher valuation. The current market valuation range of US$20 billion to US$86 billion is itself a good reminder: recognition of direction does not mean any price is worth buying.
For Hong Kong stock investors, at this stage they can first add T-Head to their IPO watchlist and focus on tracking the prospectus, offering valuation, and cornerstone investor situation. Once the price actually lands, they can then judge whether a "good company" and a "good price" appear at the same time.
Subject to meeting eligibility requirements and jurisdictional restrictions, BIT provides Hong Kong and US stock trading services to eligible users (Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted jurisdictions). Margin financing for IPO subscriptions may increase the subscription amount, but does not guarantee more allotment; leverage amplifies costs and risks and should be carefully considered in light of individual risk tolerance. This article does not constitute investment advice, and whether to participate is for investors to decide on their own.
Disclaimer:
The content of this article is for general information and market commentary only, based on public materials as of the time stated in the article, and relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other persons cited in the article represent only the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it be used as the basis for any investment decision. Financial markets involve risk; securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Investors should independently assess relevant risks according to their own circumstances and seek professional advice when necessary.