


Bank of America's Hartnett: The Dollar Is "Breaking Everything," Stay Defensive Until the Dollar Falls


- Core View: A strong dollar is tightening global liquidity and suppressing risk assets. BofA strategist Hartnett has pushed the timing for rotating into risk assets to next spring, waiting for signals of a dollar peak and a pullback in oil prices and Treasury yields.
- Key Elements:
- The dollar index closed at 103.42, a new year-to-date high, while gold fell below $4,000, seen as a signal of global liquidity contraction.
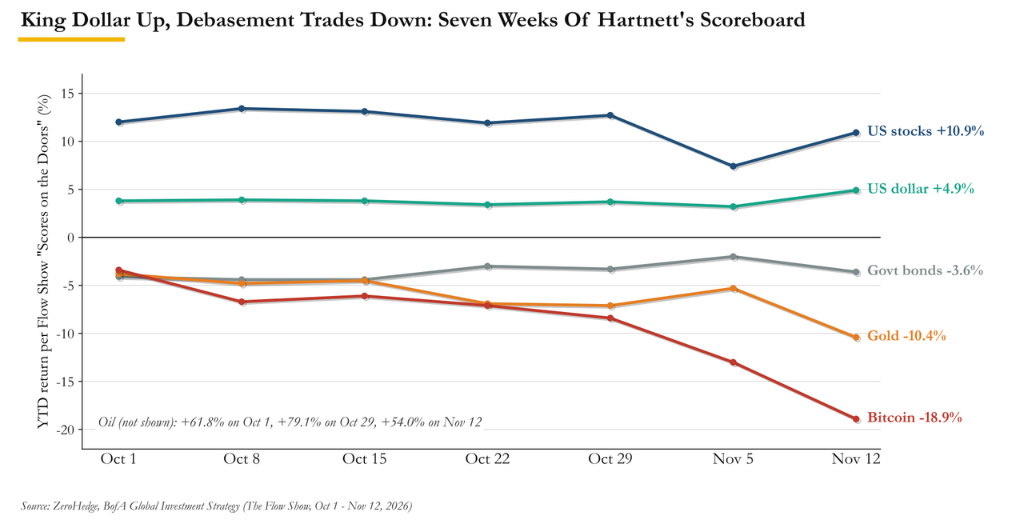
- Gold is down 10.4% year-to-date, Bitcoin down 18.9%, government bonds down 3.6%, and emerging market bonds saw $1.5 billion in outflows in a single week.
- All three entry conditions (WTI below $70, 10-year Treasury yield below 4.5%, and a weakening dollar) have not been met.
- Fed officials signaled a 50 basis point rate hike in December, and Goldman Sachs has incorporated a March rate hike into its base case forecast.
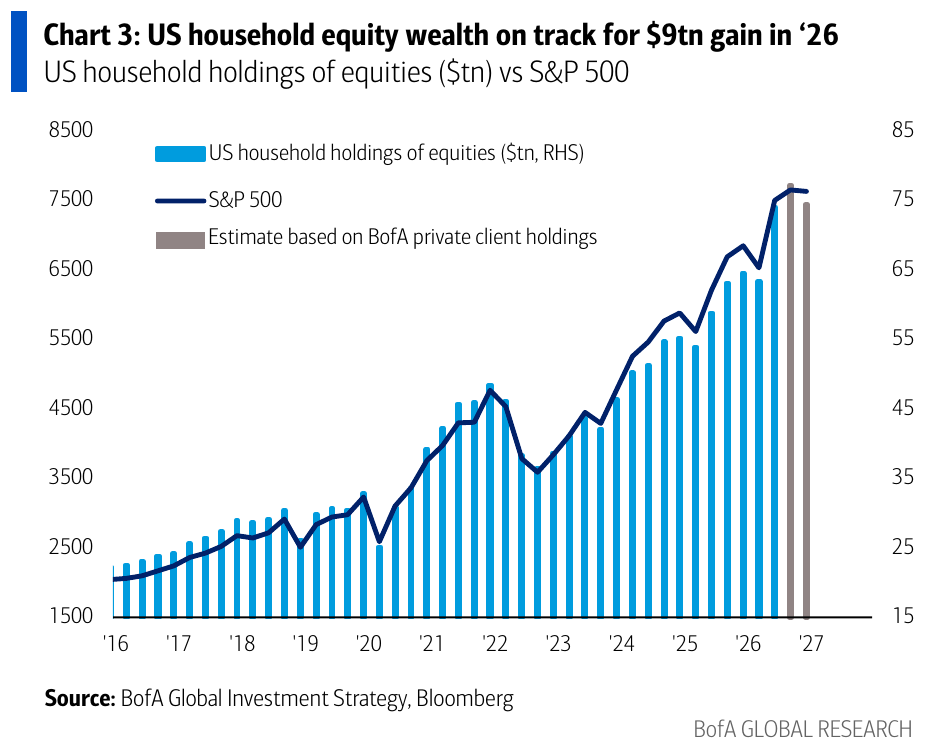
- U.S. household stock wealth has increased by $19 trillion to $74 trillion since January 2025, supporting consumption and the economy.
- The market consensus for S&P 500 earnings growth is 18%, while Goldman Sachs forecasts only 11%, corresponding to an index level of about 7,100 points, close to the 7,000-point bear market trigger range.
Original authors: Bao Yilong, Ye Zhen
Original source: Wallstreetcn
A continuously surging dollar is tightening global liquidity and has become a "wrecking ball" for financial markets, suppressing global risk assets and commodities, with risk assets still difficult to enter.
This is the view of Michael Hartnett, Chief Investment Strategist at Bank of America, in his latest Flow Show report.He believes the market currently faces a triple contradiction—the Fed's tightening cycle is far from over, government market support has built a barrier against short sellers, and the wealth effect of high-net-worth consumers is propping up the economy. This means that, at present, risk assets are neither worth chasing higher nor safe to short.
Hartnett has once again pushed back his year-end bullish "finish line." He had originally expected a year-end rally to potentially begin after the midterm elections and before Thanksgiving, but employment data coming in far above expectations, inflation running hot for three consecutive months, and Fed officials signaling a 50-basis-point rate hike have completely disrupted the timing. Only when oil prices, U.S. Treasury yields, and the dollar all decline in sync will there be a signal to add positions—and that wait may last until next spring.
Last Friday, the dollar index closed at 103.42, a new high for the year. Hartnett characterizes it as the "wrecking ball" of global liquidity—a persistently strengthening dollar combined with gold falling below $4,000 means, in his analytical framework, that global liquidity is contracting.
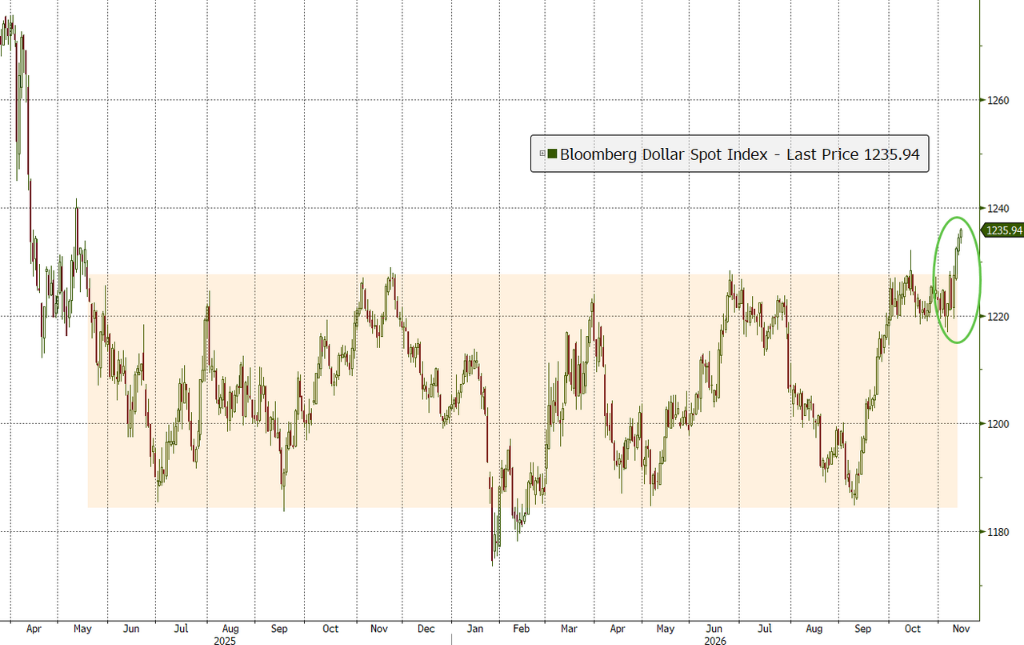
Against this backdrop, he has pushed the end of the global rate-hike cycle to the Fed's April policy meeting next year and extended his bearish stance on risk assets until after the dollar peaks next spring.
In terms of market impact, this round of dollar strength has already dealt a clear blow to multiple asset classes: gold's year-to-date decline has widened to 10.4%, Bitcoin is down 18.9%, government bonds have fallen 3.6% this year, and emerging market bonds saw a single-week outflow of $1.5 billion.
The Dollar as a "Wrecking Ball": Global Liquidity Contracts Across the Board
Dollar strength is the most central market variable this week.
After rising for four consecutive trading days, the dollar index closed Friday at a new year-to-date high of 103.42; the yen touched the 160 mark, prompting verbal intervention from Tokyo authorities; gold fell 4.7% for the week to about $3,874, closing below $4,000 for the first time in months; and Bitcoin slid below $70,000.
Hartnett's logic is simple and direct: a surging dollar plus gold falling below $4,000 equates to a retreat signal for global liquidity.
He had already used this as his benchmark when he advised clients on October 3 to start increasing bond allocations, explicitly stating that he would maintain a risk-off stance until the dollar peaked. Six weeks later, the dollar has risen rather than fallen, and he now pushes his expected dollar peak to February–March next year.
This judgment aligns closely with the forecasts of Goldman Sachs' FX team. According to Bloomberg, Goldman strategists Kamakshya Trivedi and Michael Cahill expect in their 2027 outlook that EUR/USD will fall to 1.08 within three months and then rebound to 1.15 by the end of 2027; the trade-weighted dollar is currently about 13% overvalued relative to its average.
Both institutions believe the dollar's destructive move will arrive before any easing.
All Three Entry Conditions Fail, Turning Point Pushed to Next Spring
Hartnett has set three prerequisites for a shift toward risk appetite: WTI oil below $70, the 10-year Treasury yield below 4.5%, and the dollar beginning to decline. At Friday's close, none of the three conditions had been met.
On oil, WTI would need to fall another roughly 21% to reach the $70 threshold, and that threshold itself has already been lowered from $80 a week earlier. Brent crude briefly fell below $90 this week but then rebounded on geopolitical comments, with WTI settling around $89 over the weekend.
On Treasury yields, the 10-year yield closed last Friday at 5.15%, up about 28 basis points for the week and just shy of multi-year highs, with tail spreads appearing in the three-year, 10-year, and 30-year auctions. Achieving a 65-basis-point decline in yields while the Fed is debating whether to raise rates by 25 or 50 basis points in December is extremely difficult.
On the dollar, the current trend is the exact opposite of the entry condition—a new year-to-date high, with the peak expectation pushed to February–March next year.
Meanwhile, the inflation situation continues to exert pressure. Fed Governor Waller has signaled a 50-basis-point hike in December, Goldman Sachs has incorporated a March rate hike into its baseline forecast, and the October NFIB survey shows the share of small businesses planning to raise prices jumping to the highest since July 2022—historical data show this is highly correlated with inflation of at least 3% to 4%.
Hartnett also specifically notes that the Fed's 2% inflation target was last met in February 2021—67 months ago.
Why Stocks Remain Resilient: Wealth Effect and Policy Support
Despite a challenging macro environment, the S&P 500 has maintained its gains.
Hartnett explains the market's refusal to fall through two dimensions. First, "why not save." According to BofA data mapping, since January 2025, U.S. household equity wealth has increased by $19 trillion, reaching a total of $74 trillion. Since consumption accounts for 70% of U.S. GDP, the high propensity to consume among wealthy households holding substantial equity assets makes it difficult for the economy to fall into a deep recession.
Second, "why not sell short."
Recent turmoil in Asian markets has prompted governments in multiple countries to take substantive intervention measures. According to reports, relevant regulators have introduced measures including short-selling restrictions, suspension of margin rules, and the establishment of a $15 billion stabilization fund; China's equity funds even set a record with five consecutive weeks of inflows totaling $88 billion. Policymakers' stance of treating the stock market as "too big to fail" has supported retail buying of tech stocks.
"Boom" Expectations Are the Last Line of Defense
Hartnett points out that in May this year, market consensus collectively bet on "no landing, no rate hikes, no cuts to AI capex, no Democratic sweep"—and nearly all four failed.The last remaining bullish belief in the market is the expectation of a "boom"—namely, 5% to 6% nominal GDP growth in 2027 and S&P 500 earnings growth exceeding 15% to 18%.
He believes this expectation carries downside risk. Goldman Sachs Chief Equity Strategist Peter Oppenheimer forecasts in his 2027 outlook that S&P 500 earnings will grow 11% next year, far below the 18% market consensus. At the current price-to-earnings ratio of about 19.5x, this gap corresponds to an index level of about 7,100 points—landing right near the 7,000-point bear-market trigger range set by Hartnett.
Goldman itself still maintains an 8,700-point target, but that requires earnings delivery and further valuation expansion, and the current 5.15% 10-year Treasury yield poses a clear constraint on that.
Hartnett sees BofA's November Global Fund Manager Survey, to be released on November 17, as a key observation window:
- If "boom" expectations fall sharply and the cash level rises above 4.2%, sentiment will no longer be an obstacle to buying;
- If "boom" expectations remain elevated while the cash level falls below 3.7%, the market has not yet formed sufficient panic, and entry conditions are still not in place.
Hartnett has laid out a clear two-way scenario framework for the S&P 500. The index currently closed at 7,562 points, sitting right in the middle of the two trigger points.
If the index breaks above 8,000 points, the drivers would be continued dip-buying flows, the "stocks over bonds" signal conveyed by the equal-weight S&P 500 returning to historical highs, and the technical support of junk bonds, the S&P 500 index, brokerage stocks, and TSMC all holding their 200-day moving averages.
He also views the APEC summit in Shenzhen on November 18 as a potential catalyst, believing a meeting among the leaders of China, the U.S., and Russia could confirm an oil price peak.
If the index falls below 7,000 points, the core risks come from a liquidity shortage triggered by a sharp dollar rally and a policy mistake in which central banks continue raising rates amid an economic slowdown. The most vulnerable assets include high-yield bonds, U.S. and emerging market equities, the energy and healthcare sectors, and mega-cap consumer stocks.
If his risk-off judgment is proven wrong, the assets most likely to rally significantly over the next eight weeks include gold, investment-grade tech debt, Japanese and European equities benefiting from a strong dollar and low oil prices, Chinese tech stocks, small- and mid-cap stocks, semiconductors, consumer discretionary, and homebuilder sectors.





