


Storage Profit Margin at 80% Yet Still Sold Off: Has the Market Stopped Believing in the Memory Supercycle?


- Core Viewpoint: Memory giants are posting record profits, but their stock prices have pulled back sharply. The market's pricing logic has shifted from "profit level" to "profit slope," with the core debate centering on whether high margins can be sustained and whether new demand can materialize as expected.
- Key Elements:
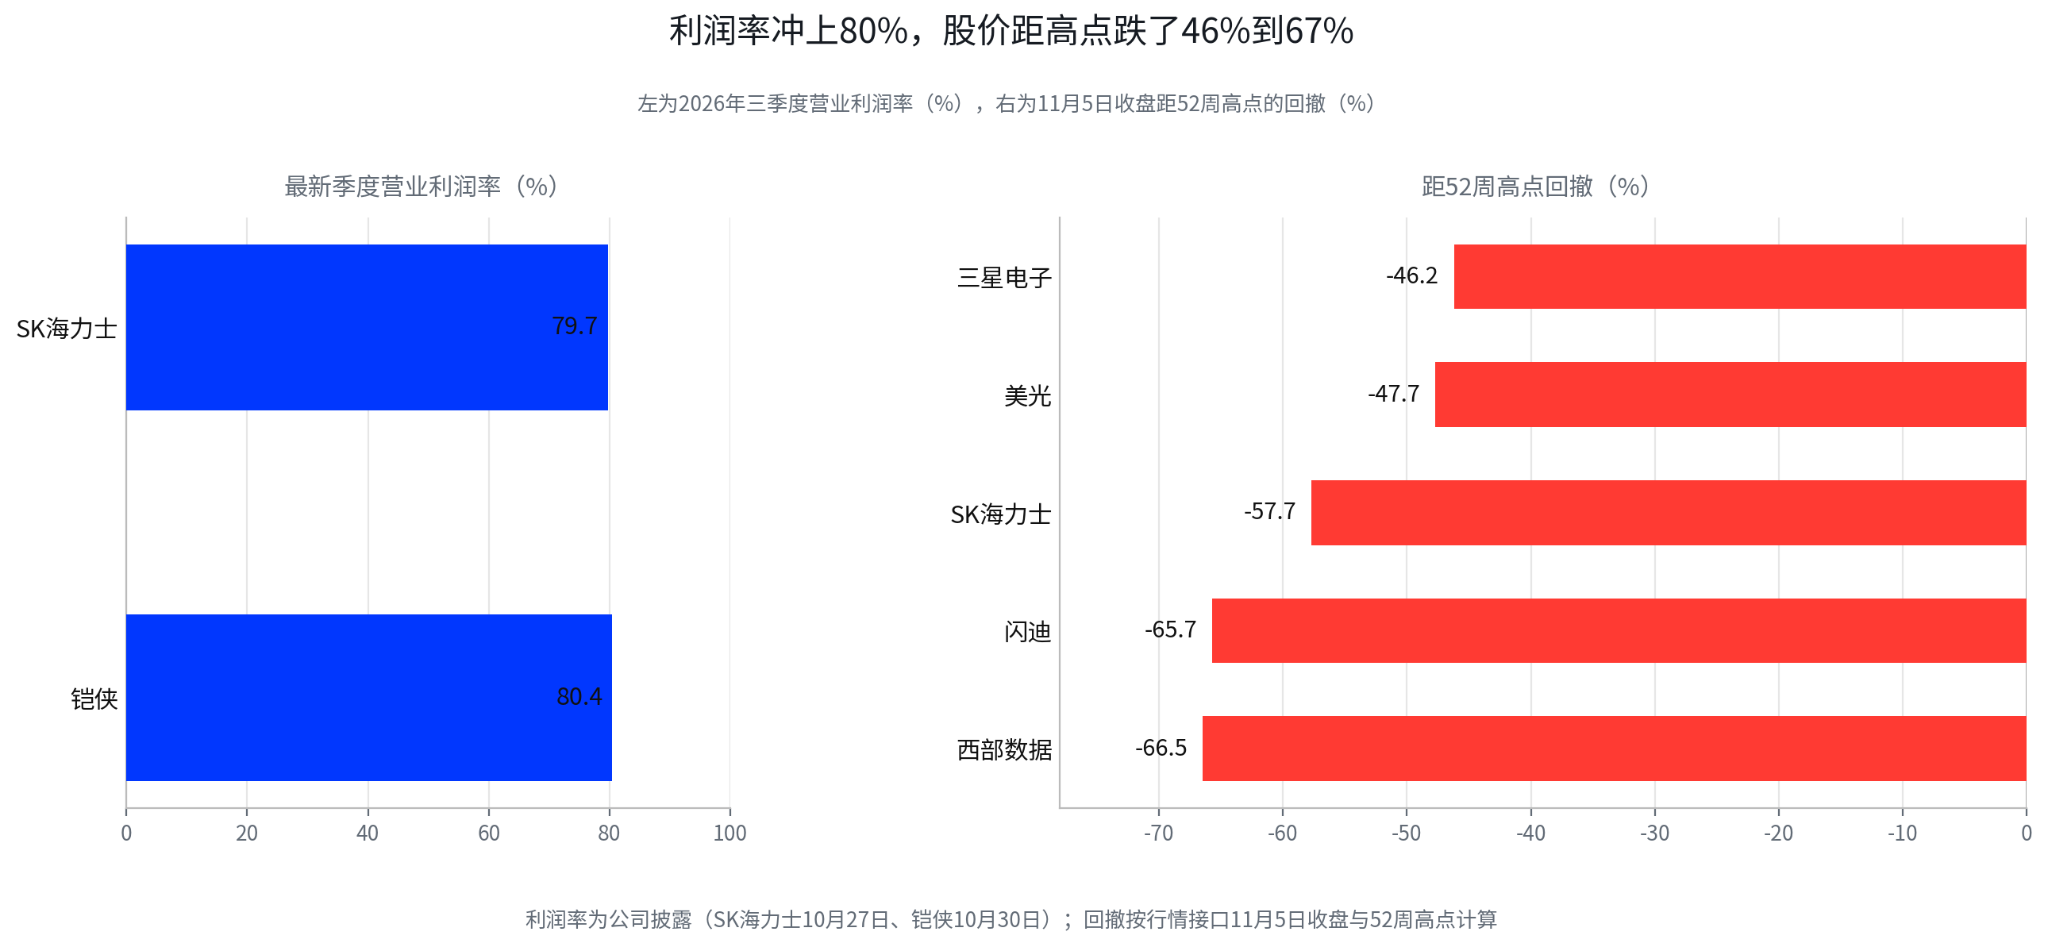
- SK Hynix's Q3 operating margin was nearly 80%, and Samsung's quarterly operating profit exceeded KRW 107 trillion, yet their stocks fell 9.46% and 7.57% respectively on the day, with SK Hynix down 57.7% from its June high.
- The sequential increase in DRAM contract prices narrowed from 90%-98% in Q1 to 13%-18% in Q3. Prices are still rising but the pace has clearly slowed, with support shifting to capacity allocation and structural shortages.
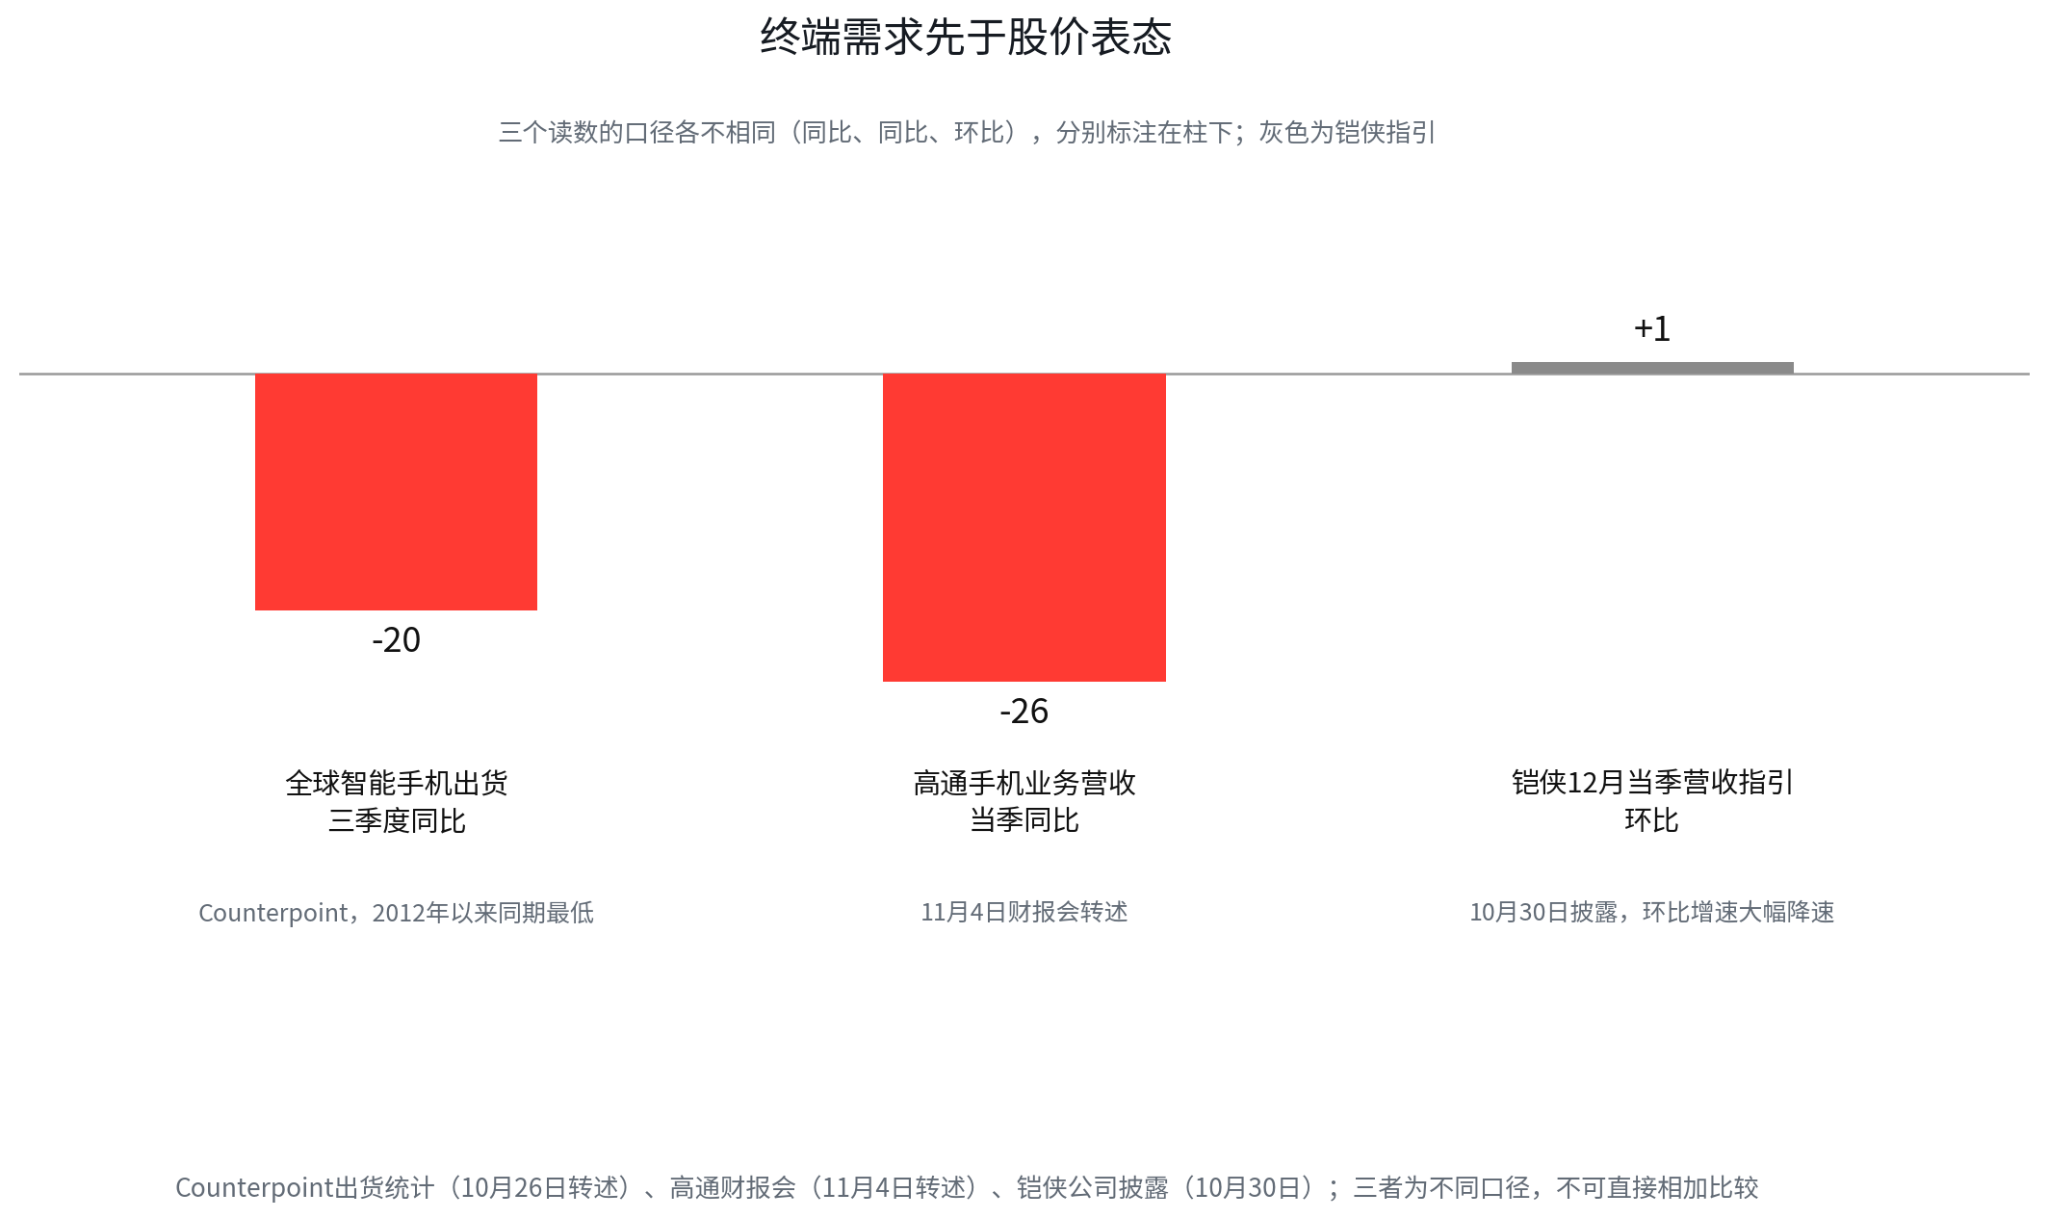
- Kioxia's operating margin exceeded 80%, but its December-quarter revenue guidance implies only about 1% sequential growth. Management cited weak smartphone and PC demand, as end markets have limited capacity to absorb high memory costs.
- After the midterm elections, 46 of 47 local votes on data center construction leaned toward restricting development. Policy risk mainly affects new projects that have yet to break ground, while signed long-term agreements are not directly impacted.
- Major memory stocks trade at roughly 3.5x 2027 expected earnings, yet the market expects a 98% EPS CAGR from 2026 to 2028. The low P/E relies on assumptions of profit sustainability.
- Over 50% of SK Hynix's 2027-2028 capacity has been locked in under long-term supply agreements, with the memory shortage expected to persist until 2030; Micron expects supply to improve only gradually by 2028.
- Judging whether the cycle has peaked requires watching three key signals: whether contract prices turn negative, whether AI data center capex is constrained by policy and power limits, and whether long-term agreement coverage and actual margins can both be maintained.
On November 5, a striking contrast emerged in the memory sector that was hard to ignore. SK Hynix reported third-quarter operating profit of 83.33 trillion Korean won, with an operating margin approaching 80%. Samsung Electronics' single-quarter operating profit exceeded 107 trillion Korean won, with its semiconductor business contributing the vast majority. Both companies were posting record profits, yet their stock prices moved in the opposite direction of their earnings. SK Hynix fell 9.46% in a single day, Samsung Electronics dropped 7.57%, and U.S. memory stocks also faced concentrated selling.
SK Hynix closed at 1.264 million Korean won, down 57.7% from its high of 2.987 million Korean won on June 25. The market can see the profits; what it doubts is something else entirely: is this profit the starting point of a new long-term growth cycle, or the highlight moment left behind at the peak of a cycle?
The question facing memory stocks has shifted to a different level. Whether profits are high enough is only the first half; how fast profits can still grow is the second half. What the market is trading on now is no longer the level of earnings—the slope of earnings is the main thread.

The core debate in this rally has shifted from whether there will be demand in the future to whether already-locked orders can sustain current prices, and how much unlocked new demand can still grow.
1. Prices Are Still Rising, but the Market Is Starting to Worry They Can't Rise Further
The earnings elasticity of the memory industry comes from prices. Prices are still rising, but the pace of increase has slowed.
DRAM and NAND are typical cyclical products. Once supply and demand become unbalanced, price increases quickly transmit to the income statement. When the rate of price gains begins to narrow, even if quoted prices are still rising, stock prices may trade on profit growth peaking ahead of time.
TrendForce data already shows this path of change: conventional DRAM contract prices rose 90% to 98% quarter-over-quarter in Q1, slowed to 58% to 63% in Q2, and further narrowed to 13% to 18% in Q3 (as cited in reports). From nearly doubling in a single quarter to growing in the low teens, the pace of price increases has clearly slowed.
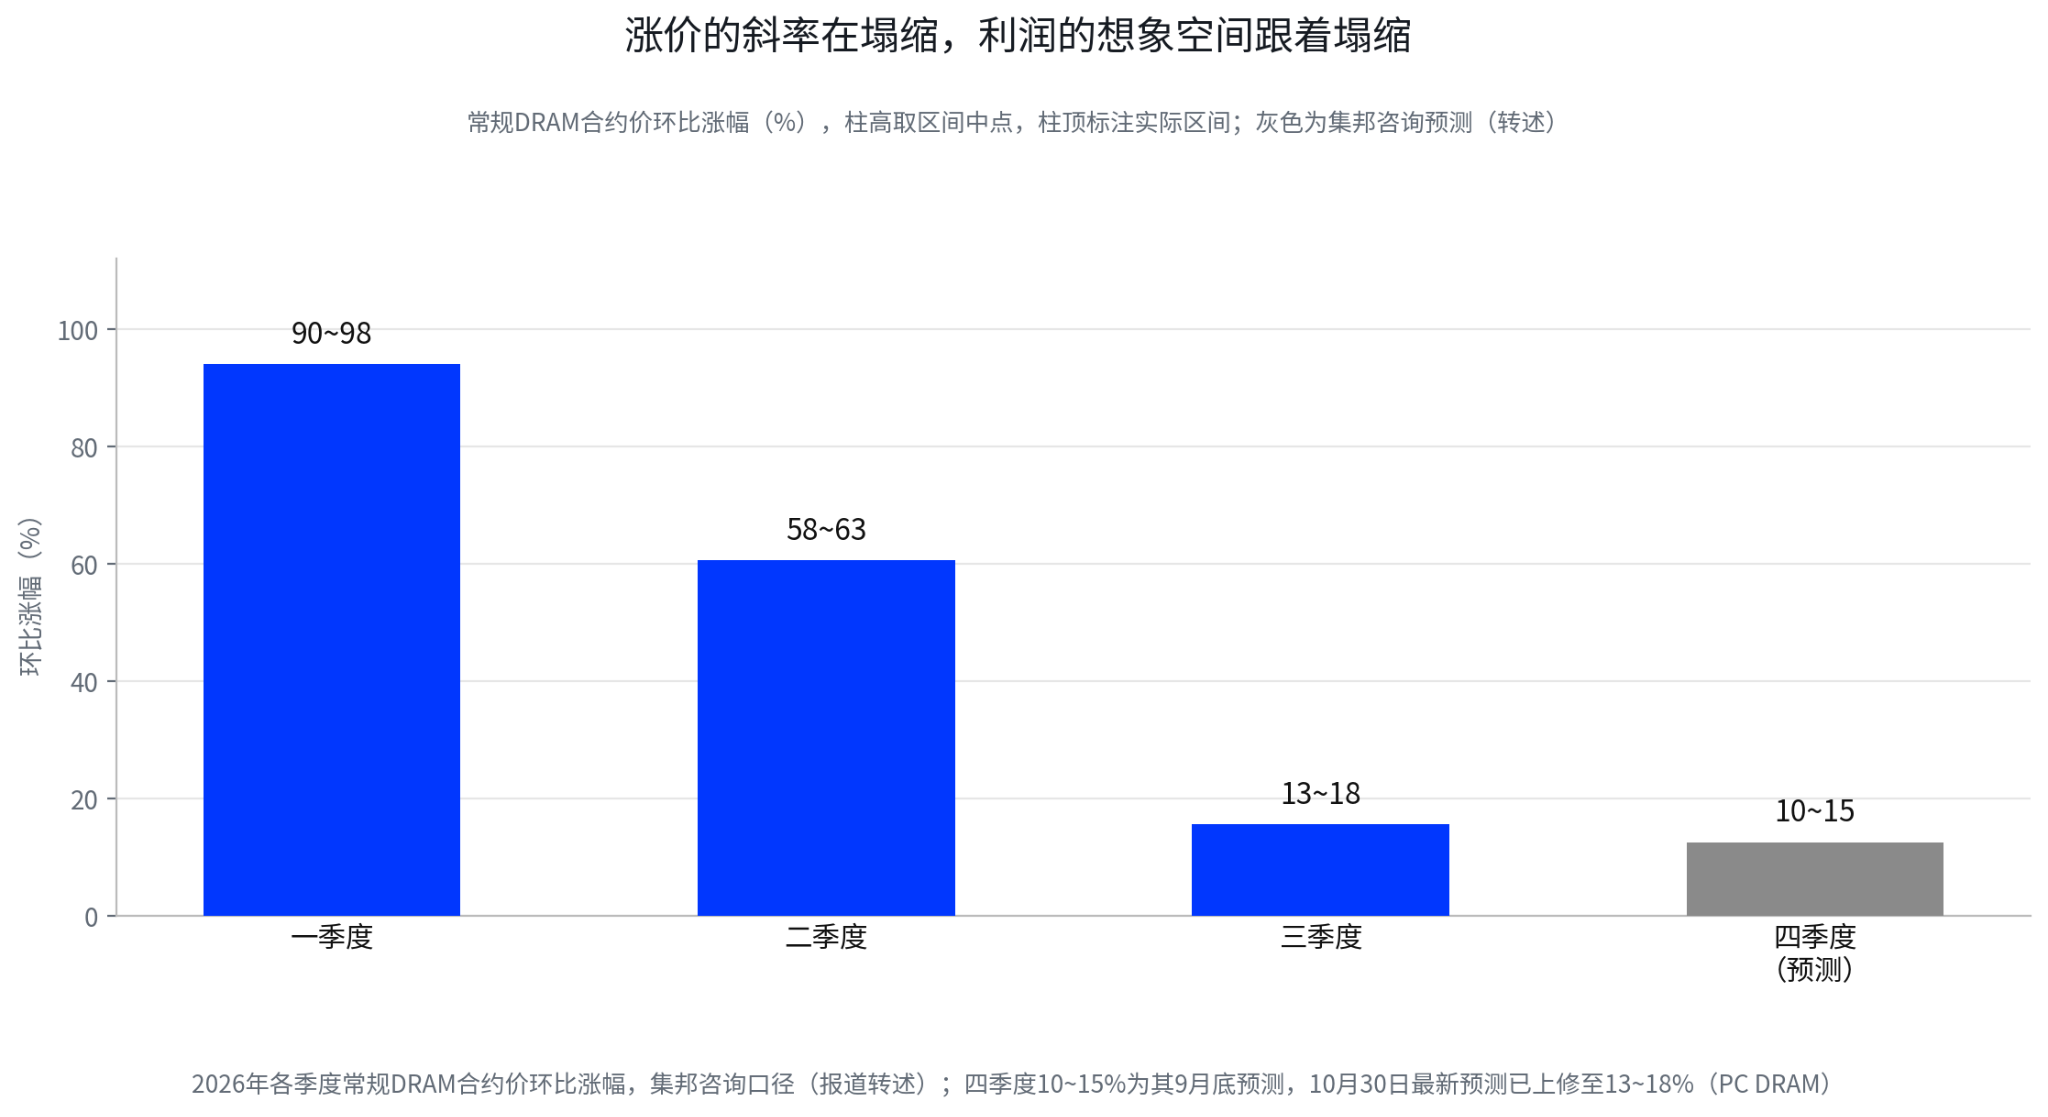
Of course, one set of numbers alone is not enough to conclude that the cycle has reversed. On October 30, TrendForce revised up its Q4 PC DRAM price increase forecast to 13% to 18%, higher than its previous forecast of 10% to 15%, as suppliers continue to shift capacity toward server memory, potentially further tightening ordinary PC DRAM supply. The industry view circulating in the market is that Samsung, SK Hynix and other manufacturers may cut PC DRAM supply by more than 40% next year. The price uptrend remains, but the support has changed sources—it now relies on capacity allocation and structural shortages. The phase of synchronized expansion across all categories of end demand is over.
Kioxia's earnings showed the market another side of demand. The company reported revenue of approximately 2.48 trillion yen for the July-September quarter, operating profit of approximately 1.99 trillion yen, and an operating margin exceeding 80%—very strong profitability (company disclosure, October 30). Yet its revenue guidance for the December quarter was only about 1% quarter-over-quarter growth, and management mentioned weak demand for phones and PCs, with end customers having limited ability to absorb higher memory costs. Kioxia's stock closed lower on the day of the announcement.
This is where the market is truly nervous: upstream manufacturers can continue to push prices higher through production cuts and product mix adjustments, but downstream customers may not be able to accept it indefinitely. The higher memory prices go, the greater the cost pressure on phone, PC and other end-device manufacturers. If they ultimately pass costs on to consumers through price increases, demand may be further suppressed; if they choose to absorb costs themselves, margins will be compressed.
The memory industry has entered a more complex phase: servers remain tight, consumer end is beginning to bear high prices, supplier profits continue to expand, and end demand's response to prices has become more important than ever.
2. The Midterm Elections Add a New Variable to AI Server Demand
Pressure on consumer electronics is already reflected in data and company statements, and AI servers—the most solid leg—have also gained a policy variable.
Counterpoint data shows global smartphone shipments fell 20% year-over-year in Q3, the lowest for the same period since 2012 (as cited in an October 26 report). Qualcomm said at its November 4 earnings call that memory pricing is shrinking the phone industry, with its handset business revenue down 26% year-over-year for the quarter (as cited from the earnings call).
Apple's statement was even more representative. John Ternus, who recently took over as CEO, said at the November 2 earnings call: "What we're seeing with memory pricing right now is unprecedented." The company guided December-quarter gross margin to 45% to 46% and noted that higher memory costs were an important reason for gross margin pressure (earnings call transcript). If even Apple needs to raise product prices to cope with rising costs, the pressure on small and mid-sized phone and PC makers will only be greater.
Demand elasticity on the consumer end is declining, making the memory industry's growth focus even more dependent on AI servers. This was originally the most solid support of this super cycle, but after the November midterm elections, a new policy variable has emerged along this demand line.
The Democratic Party winning the House and Senate means the Trump administration's legislative agenda for the next two years will face stronger constraints, and congressional investigation and oversight may also intensify. What the memory industry should pay more attention to is the local political backlash against data center construction that emerged during the election period. Ballotpedia statistics as of November 4 showed that of 47 decided local votes related to data centers, 46 outcomes tended to restrict data center construction. The restrictions were not all identical, including bans on new construction, construction moratoriums, added public referendum procedures, and stricter conditions for projects receiving tax incentives. Another institution counted 38 of 44 related votes that day as passing restrictions; the scope and timing of each count differ.
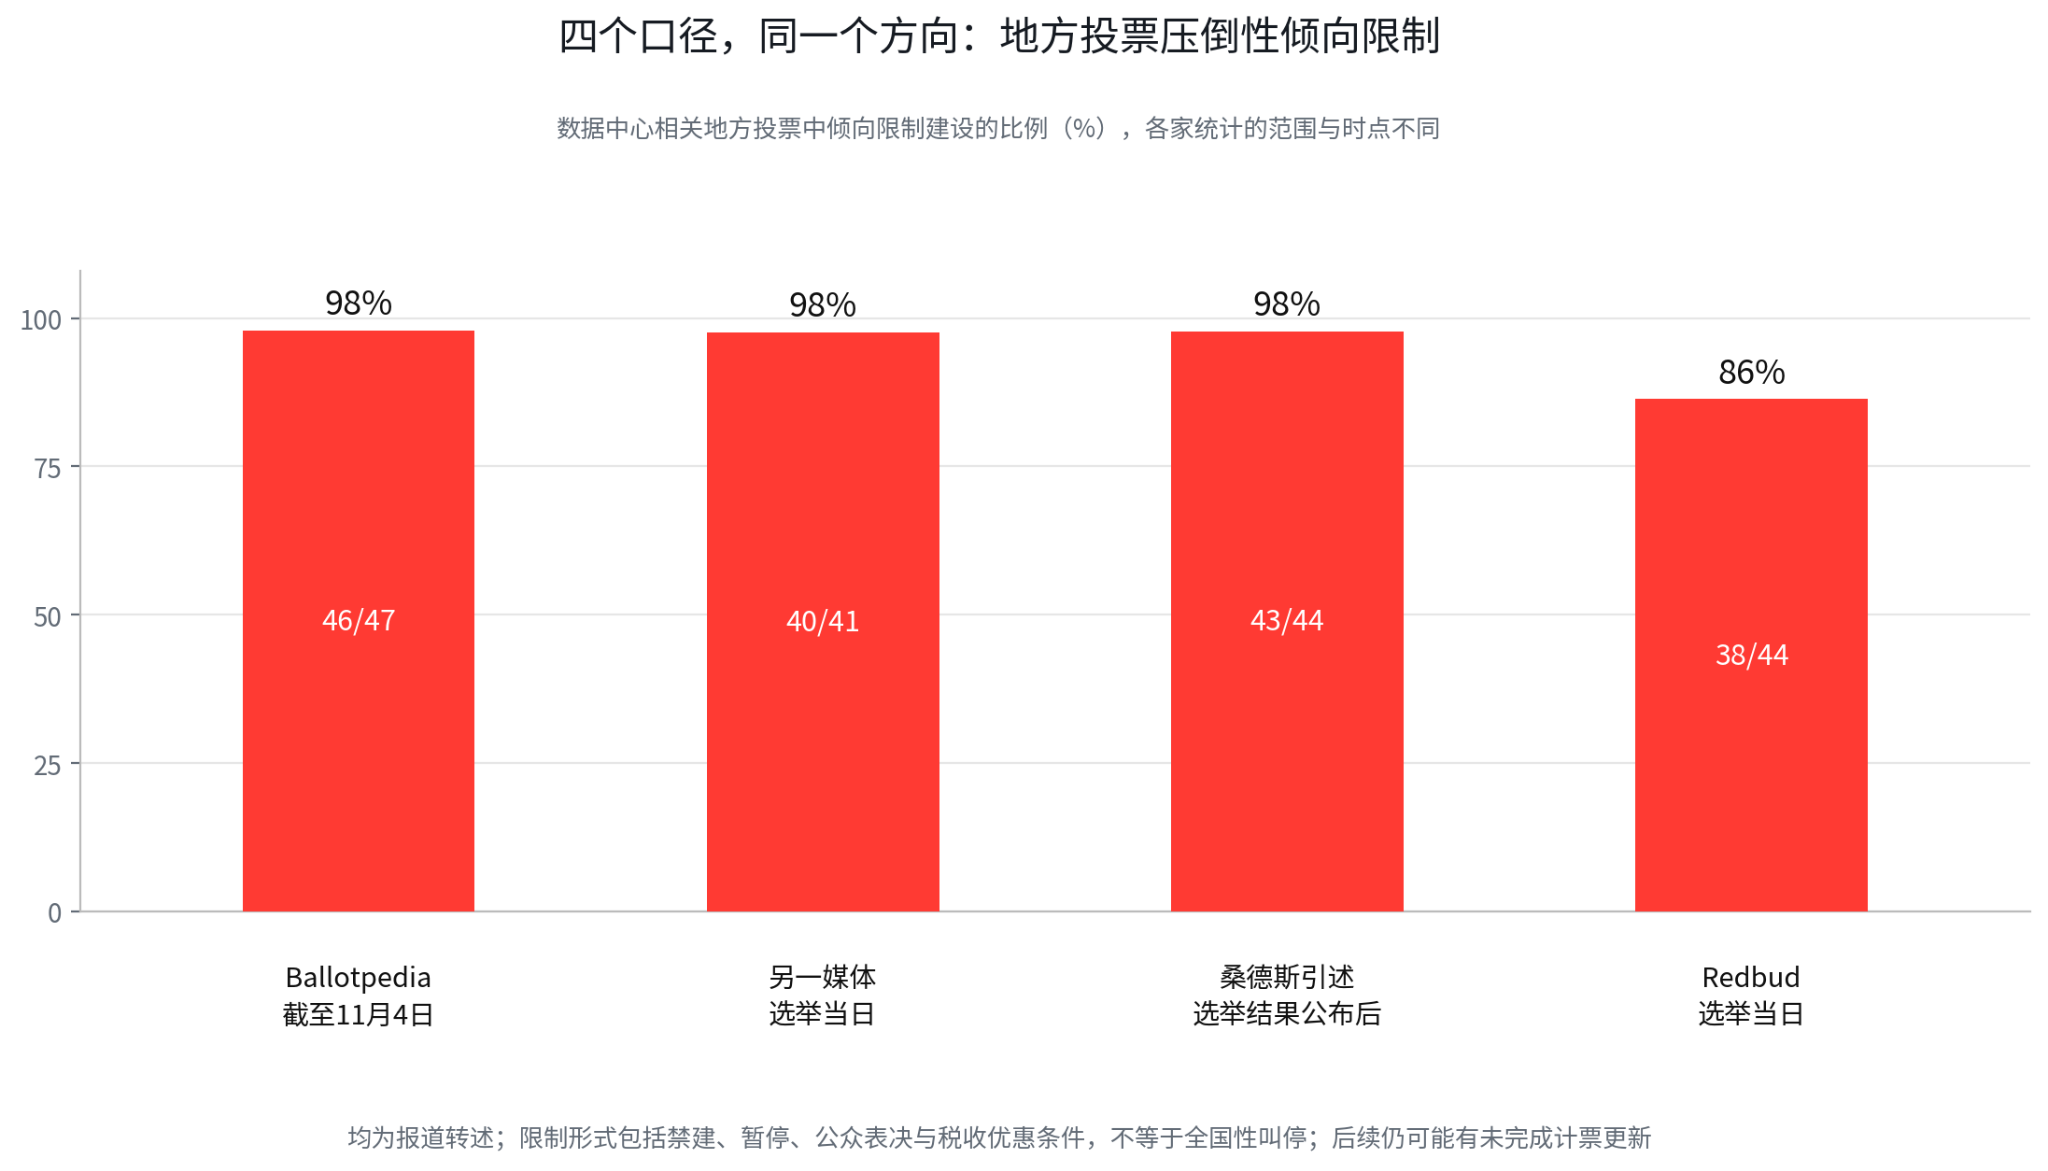
Bernie Sanders also renewed his call for a nationwide moratorium on data center construction after the election results were announced, citing the figure that 43 of 44 communities supported local restrictions. This remains a political proposal and has not entered the congressional review process. Democratic control of Congress does not mean data center projects across the U.S. can be directly halted; Trump still holds presidential veto power, and local planning and project approvals are dispersed among state, municipal and related regulatory authorities.
For the memory industry, the issue that truly deserves attention has changed object: beyond orders already signed, whether the implementation cost and timing of new projects have changed. If local governments raise approval thresholds, require developers to bear more costs for power, water and community infrastructure, or tighten tax incentives, project financing and construction cycles could be lengthened. Once data center projects are delayed, server procurement, network equipment deployment, and accompanying DRAM and SSD orders may also be postponed.
The impact on the memory market has an obvious time lag. Long-term supply agreements already signed will not automatically disappear because of one election result, but new data center projects in 2027 and beyond may need to reassess investment returns and construction schedules. Orders signed now will not suddenly drop to zero because of one election; what the market worries about is that incremental demand in the coming quarters is no longer as certain as previously expected.
This also explains why forward demand remains strong but stock prices have begun to fall. Goldman Sachs' industry meeting notes remain bullish on HBM demand, believing the supply gap may persist until 2028 (as cited on October 28). Capital markets are beginning to split AI infrastructure investment into two questions: can already-determined orders be fulfilled, and can the next round of new capital expenditure be implemented as planned. The former supports current profits; the latter determines whether valuations can continue to expand.
3. A 3.5x PE Looks Cheap—and May Be Exactly When Cyclical Stocks Are Most Expensive
The cheap calculation is not wrong; what is wrong is using peak-cycle profits as the denominator.
JPMorgan's November 4 report brought the current valuation contradiction of memory stocks to the table. Data cited in the report showed that major memory stocks had retraced about 45% on average from their 2026 highs, while the Philadelphia Semiconductor Index had retraced about 29% over the same period. The 2027 expected P/E was about 3.5x; another media outlet cited about 3.6x—both figures are presented side by side. Meanwhile, the market's expectation for the 2026-2028 EPS compound growth rate remains as high as 98% (as cited in reports).
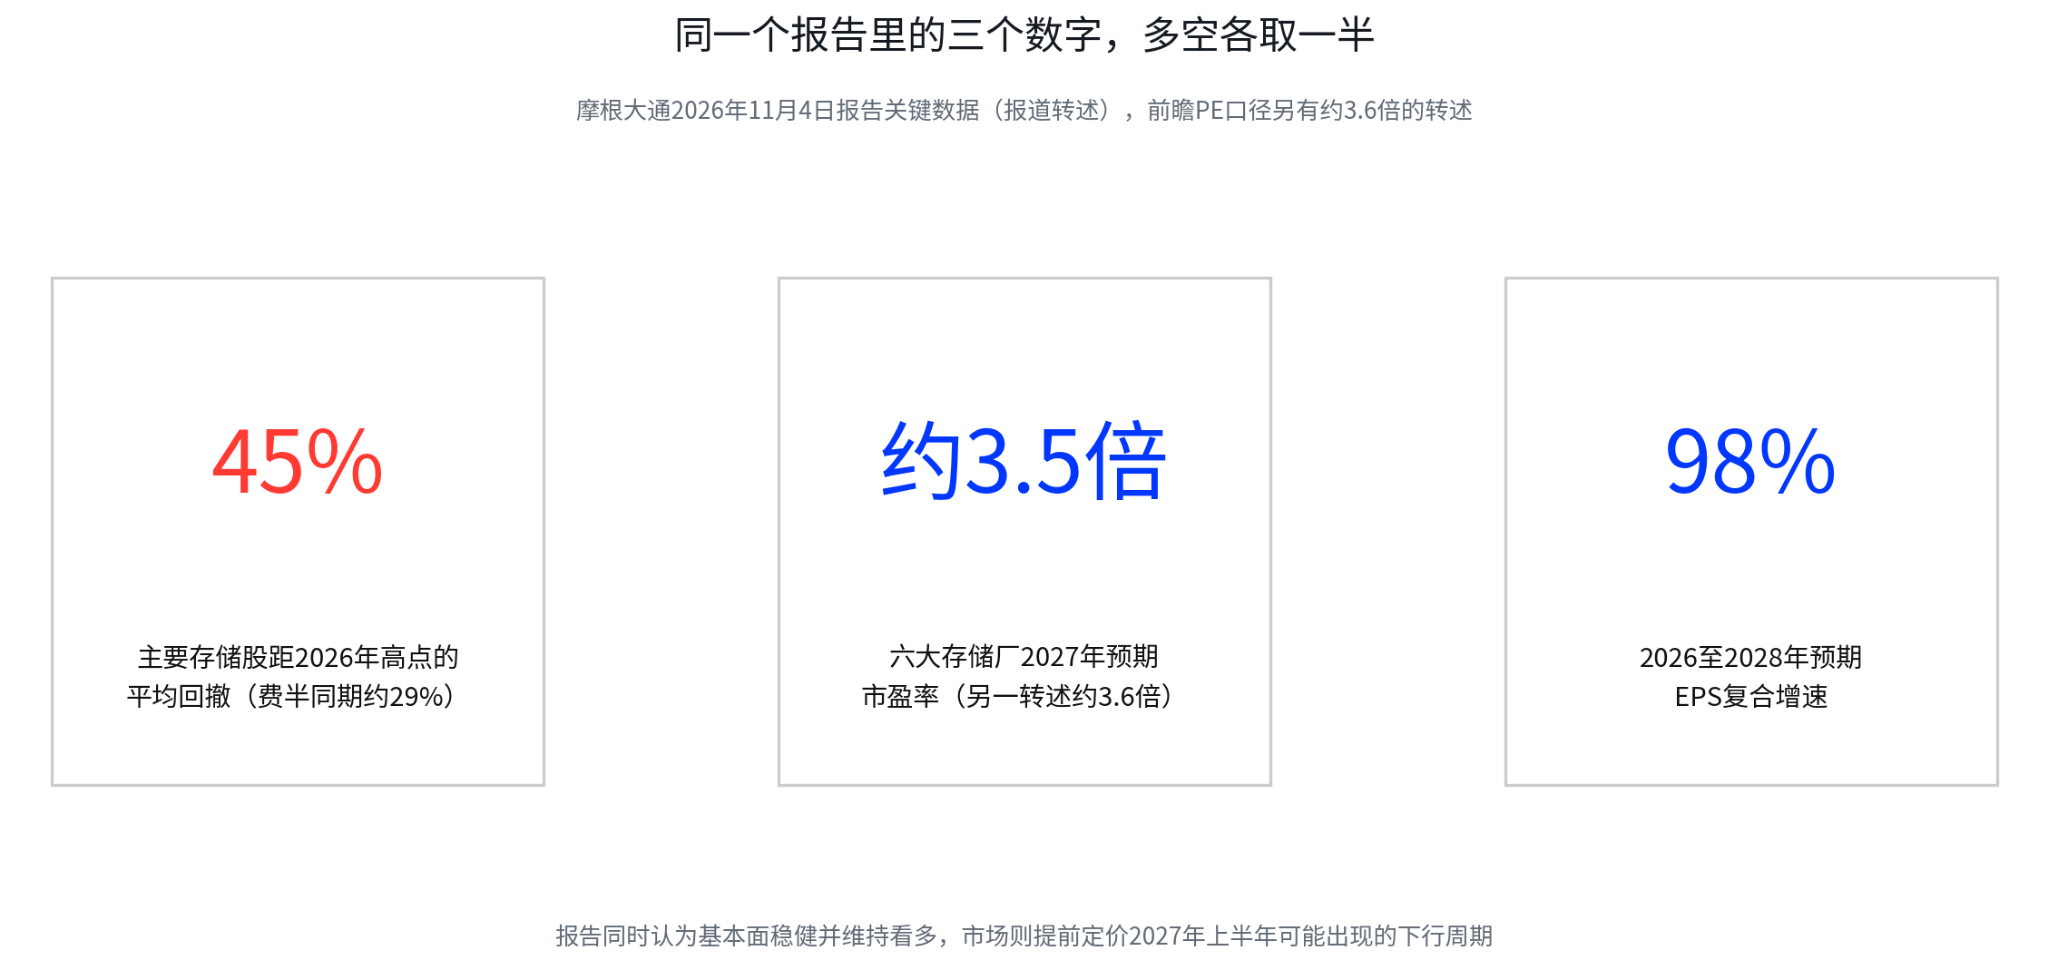
A 3.5x PE paired with near-doubling earnings growth looks very cheap at first glance. The denominator of the P/E ratio is profit. When memory prices rise rapidly, capacity utilization is high, and the product mix keeps shifting toward HBM and server memory, company profits are quickly pushed up. At this point, even if the stock price has already risen a lot, as long as earnings grow faster, the PE may still remain at a very low level. This represents something else: the market is willing to believe current profits can last for years before it can even talk about cheapness.
If memory prices enter a plateau, or consumer demand further contracts due to rising costs, profit growth may change before revenue does. Assuming profits fall from the cycle peak, a PE that originally looked like only 3.5x will quickly stop looking cheap once the denominator shrinks. What the market really needs to judge is whether these companies can still maintain profit levels close to today's two years from now; this year's report card is only a ticket to entry.
This is also why stock prices fall ahead of record earnings. Stock prices discount the future; already-reported quarterly results are only the past. The valuation compression of memory stocks is essentially reflecting capital's discount on profit sustainability.
However, bears cannot ignore supply-side constraints either. SK Hynix officially disclosed that more than 50% of its capacity for 2027-2028 has already been covered by long-term supply agreements, and the company also expects the memory shortage to persist until 2030 (company disclosure, October 27). The company emphasized that agreements will reflect market conditions and help stabilize future earnings. Samsung is also continuously expanding supply of HBM4, server DRAM and enterprise SSDs. AI server demand remains strong, and expanding advanced process, packaging and testing capacity takes time; supply cannot quickly catch up in the short term.
Both bulls and bears acknowledge the existence of AI demand; what they are fighting over is how long high profits can last. Bulls bet that the structural shortage of HBM and server memory will continue until 2028, believing long-term agreements and capacity constraints can protect profits. Bears worry that the period of fastest price increases has passed, and that end-cost pressure, data center project approvals and power constraints will gradually transmit over the coming quarters. Micron's forward P/E is also below 5x, and CEO Mehrotra's statement is that supply will only gradually improve by 2028 (as cited in a November 3 report).
The 3.5x PE the market is now assigning reflects something else: capital is unwilling to use today's profit level to pay for high valuations over the coming years.
4. Capacity Has Been Booked for Years; What Can't Be Locked Is the Profit Margin
Locking capacity solves who to sell to; long-term agreements solve how much to sell. What really determines valuation is still the selling price and profit margin.
If capacity for the coming years has already been locked in by customers in advance, what exactly is the market still worried about? Three concepts must be distinguished here:
What SK Hynix officially disclosed is that more than half of its 2027-2028 capacity has signed long-term agreements—a very strong fundamental signal. Some media summarized management's statement as supply being substantially sold out for the next three years; that is a paraphrase. The hard number at the announcement level is that more than half of capacity has signed long-term agreements. The specific binding force of long-term agreements depends on contract terms: whether there is a minimum purchase volume, how prices adjust, whether customers can delay or cancel, whether prepayments exist, and how high breach costs are. Shipment volumes being guaranteed does not mean every chip can maintain the current selling price and profit margin.
This is also where the policy risk of the midterm elections needs to be re-understood. U.S. local governments raising data center approval thresholds and adding power and water infrastructure requirements will not automatically cancel cloud厂商' already-signed long-term memory agreements in the short term. What is truly affected are data center projects not yet implemented and the next round of new server procurement. If projects are delayed, cloud providers may first adjust new capital expenditure, which then affects future renewals and expansion of long-term agreements. Policy shocks are more likely to affect incremental demand; scenarios in which already-locked orders are directly destroyed are relatively rare.
The supply side also has a time lag. SK Hynix, Samsung and Micron are still expanding HBM and server memory supply, but capacity release for advanced products takes time. At the same time, the ordinary DRAM and NAND markets may also be affected by capacity expansion from domestic Chinese manufacturers. ChangXin Memory Technologies' fifth-generation DRAM process has already entered mass production, with capacity expected to double at most by 2028 (TechInsights claim, as cited in October 5 and 19 reports), and Yangtze Memory is also continuously advancing NAND product upgrades. The supply-demand cycles of different products are not fully synchronized; one cannot infer that the entire memory industry can maintain current profit levels just because HBM remains tight.
5. To Judge Whether the Memory Cycle Has Truly Peaked, Three Signals Matter More:
First, watch whether contract prices move from narrowing gains to actual declines. The upward revision to Q4 PC DRAM price increase forecasts shows supply tightness still exists. But one must distinguish server DRAM, PC DRAM, HBM and NAND; the quote for one category cannot be directly equated with the entire memory market. What truly warrants caution is prices shifting from slower increases to declines, accompanied by rising channel inventories and weakening customer purchasing willingness.
Second, watch whether AI data center capital expenditure is constrained by policy and power. After the midterm elections, local restrictions on data center projects have moved from campaign slogans to actual cases of construction bans, moratoriums, public referendums and tax incentive conditions. Next, observe whether major cloud providers adjust capital expenditure guidance, whether project approval and power connection cycles lengthen, and whether construction plans for new data centers are postponed. Only when these changes transmit to server procurement will they truly affect memory manufacturers' orders.
Third, watch whether long-term agreement coverage and actual profit margins can be maintained simultaneously. Long-term agreements can improve capacity utilization and shipment certainty. If the magnitude of contract price adjustments declines, or supply of high-margin products gradually increases, profit margins may still fall back. In SK Hynix and Samsung's upcoming earnings, it is necessary to simultaneously observe the product mix, average selling prices, gross margins and capital expenditure of HBM, server DRAM and enterprise SSDs. Looking only at whether revenue and operating profit hit new records is not enough.
The memory industry remains in a structural opportunity brought by AI infrastructure expansion; demand for HBM and server memory has not disappeared because of one election. The market is no longer willing to price in all growth expectations in advance. Whether the consumer end can bear high prices, whether data center projects can be implemented on time, and whether suppliers can maintain current profit margins—these questions are beginning to matter more than the next record-breaking earnings report.
An 80% operating margin is the result this super cycle has already delivered. A 3.5x forward PE is the market's doubt about the sustainability of future profits. The wall memory stocks have hit is built from pricing. The height of the wall does not depend on the absolute level of profits; it depends on how much the market is willing to pay for years that have not yet materialized.
Disclaimer:
This content is for general information and market commentary only, based on public materials as of the time described in the article, and relevant market data, expectations and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts or other persons cited in the article represent only the views of the relevant third parties at specific times and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation or recommendation for any securities, investment products or trading strategies, and should not be relied upon as the basis for any investment decision. Financial markets involve risks; securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when needed. BIT's Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted





