


The Battle for Long-Tail Markets: Is Hyperliquid Losing Its Edge?


- Core Viewpoint: Hyperliquid's liquidity in long-tail assets has deteriorated significantly, with near-end order book depth shrinking substantially. It has lost its core competitive advantage relative to Binance. The root cause lies in mechanisms such as fees and network resource allocation that continuously favor top market makers, squeezing the survival space of smaller market makers.
- Key Elements:
- Under the 10bps standard, Hyperliquid's median USD-denominated depth fell 82%, Binance fell 61%, and OKX fell 78%; Hyperliquid's median depth ratio relative to Binance dropped a further 57.5%.
- In the 5bps near-end range, the USD depth index is only about 13, and the token count index is about 28; however, the 20-level full-range token count index reaches 127, indicating liquidity is migrating away from the mid-price area.
- Median trading cost for a $10,000 order: Hyperliquid 5.21bps, Binance 2.95bps (excluding fees).
- Over the past month, within the 25bps range, the median quote share of the largest account group rose from 34.5% to 38.6%, and the spread widened from 2.13bps to 3.55bps.
- Fee structure imbalance: the lowest quartile account group by trading volume pays 0.961bps, while the highest quartile group receives 0.236bps in rebates, a cost difference of about 1.20bps.
- The average number of account groups providing effective quotes dropped from 7.64 to 6.39, with declines in 58 of 72 markets.
- Within 25bps of HIP-4 contracts, 47% of visible depth comes from four professional market-making wallets; congestion rules allocate block space based on the previous day's share, creating a cycle of "you need trading volume to get an allocation."
This article is from: 0d Labs CEO matteo
Compiled by Odaily (@OdailyChina); Translator: Azuma (@azuma_eth)
Over the past few months, because we are developing a product that has not yet been made public, we have spent a great deal of time analyzing the liquidity of various DEXs across different trading pairs. We possess more than a year and a half of complete order book data, recorded during our own trading activity in the relevant markets through 0d Labs. During this analysis, we discovered a rather unexpected phenomenon in the long-tail segment of the crypto market — liquidity is becoming increasingly thin.
After the 1011 incident last year, we had already expected such an outcome, but at present, the entire crypto market does not yet appear to have truly recovered from that event.
In addition, many of our close trader friends have recently been complaining that Hyperliquid is becoming increasingly difficult to compete on, and that certain mechanisms on the platform seem to be concentrating advantages among top participants. From Read Priority Fees being monopolized by Wintermute, to fees and L1 network congestion making life miserable for small market makers (MMs), these issues have all caught our attention.
Therefore, I decided to further investigate the liquidity changes on Hyperliquid and try to figure out — is there a causal relationship between the deteriorating survival environment for small market makers and the decline in platform liquidity? After all, one of Hyperliquid's core competitive advantages in its early days was precisely its ability to provide deep liquidity for long-tail assets.
Comparison Baseline
First, we need to establish a baseline that reflects conditions across the entire crypto market. Liquidity may be thinning, but if this is a market-wide phenomenon, we must distinguish which changes stem from the overall market and which are Hyperliquid's own problems.
For overall altcoin liquidity, Binance is a valuable reference baseline. To this end, we selected 86 assets that traded on both platforms between November 1, 2025, and November 1, 2026, with maximum leverage below 10x, as the long-tail asset sample for this study.
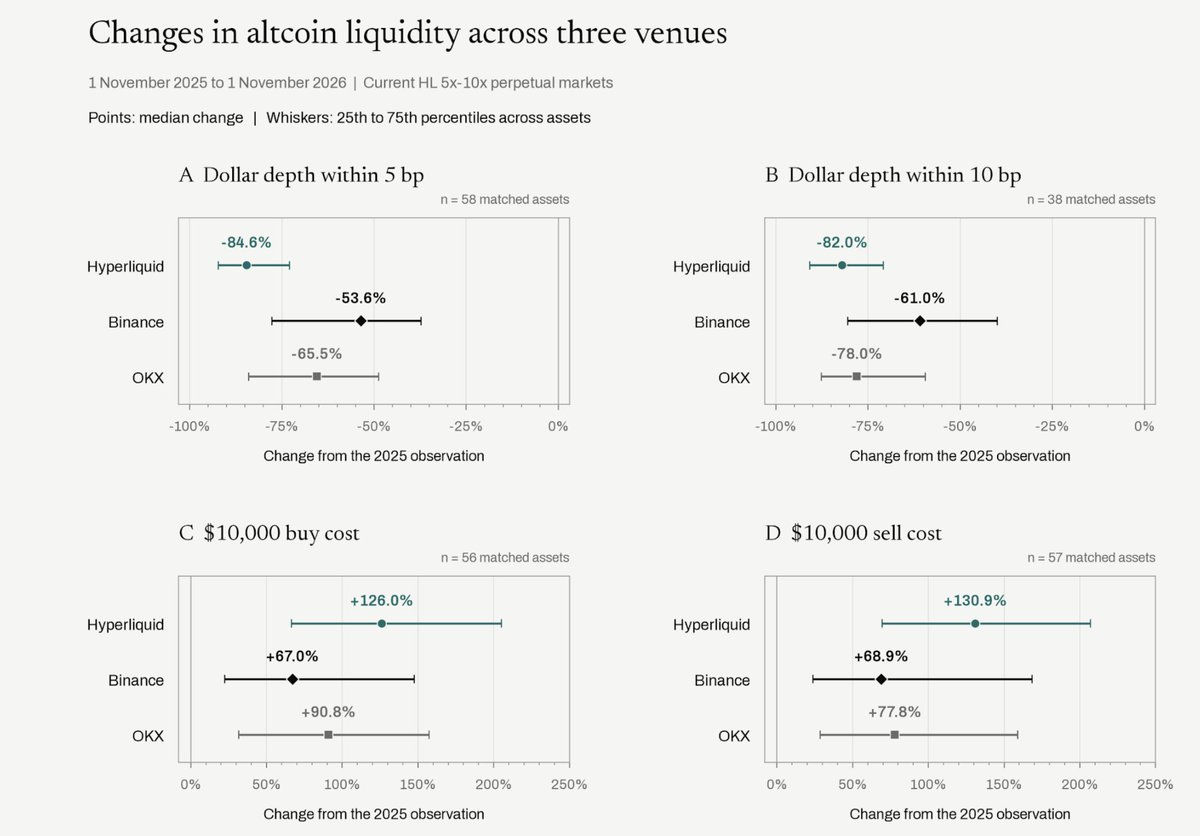
Among the 38 markets that could be compared using a uniform 10 basis point (bps) standard, the median USD-denominated depth on Hyperliquid fell by 82%, Binance fell by 61%, and OKX fell by 78%. This gap is already quite significant.
Of course, falling token prices themselves will cause USD-denominated order book depth to shrink, but we still need to further confirm whether the quantity of tokens quoted within these price ranges is also declining.
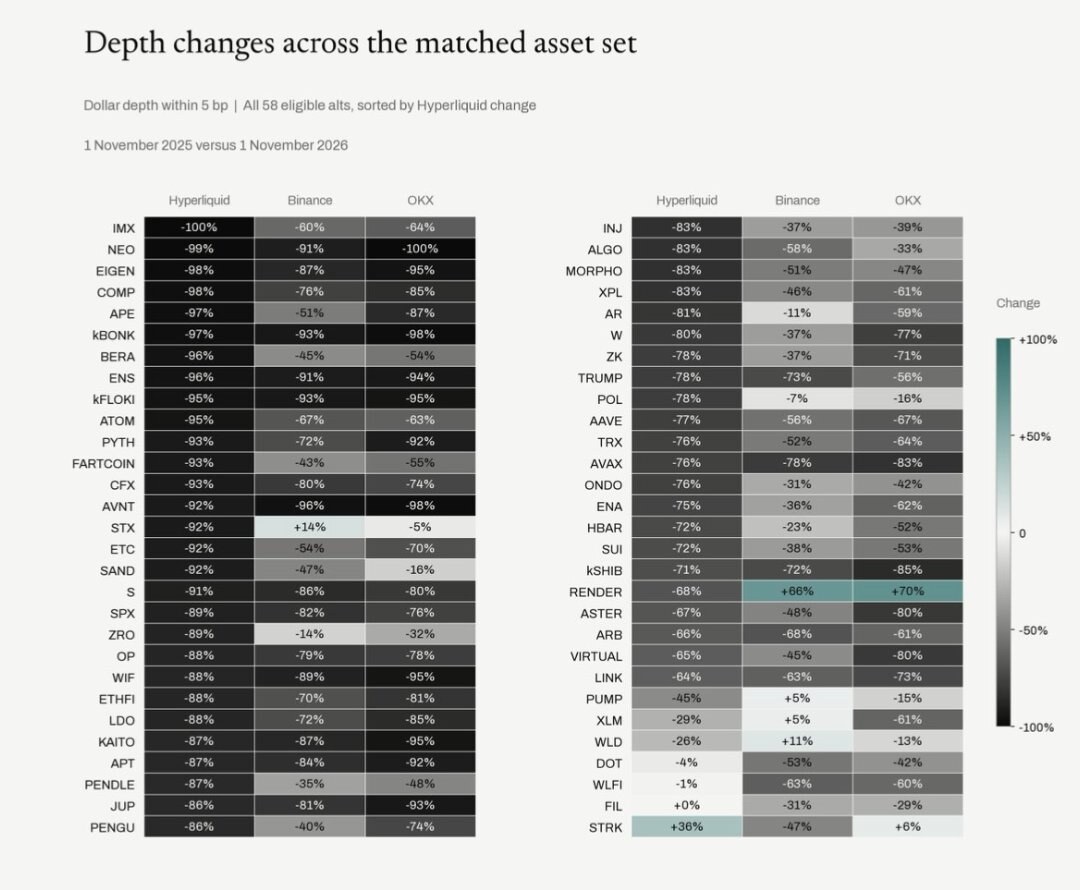
To determine whether Hyperliquid has a unique problem, I divided each asset's depth on Hyperliquid by its depth on Binance, then compared how this ratio changed over the course of a year. Within a 5 basis point range, the median of this ratio fell by 57.5%.
This means that even when we observe the liquidity of the same token on two platforms, Hyperliquid still lost a substantial amount of liquidity relative to Binance. It should be noted that these ratios are calculated market by market, rather than simply dividing the median depth of the two platforms.
If we wanted to buy $10,000 worth of an asset during the latter sample period, based solely on the quotes displayed on the order book, the median trading cost on Hyperliquid was 5.21 basis points, while on Binance it was only 2.95 basis points, before accounting for fees. For an order of this relatively modest size, that means costs of $5.21 versus $2.95 respectively.
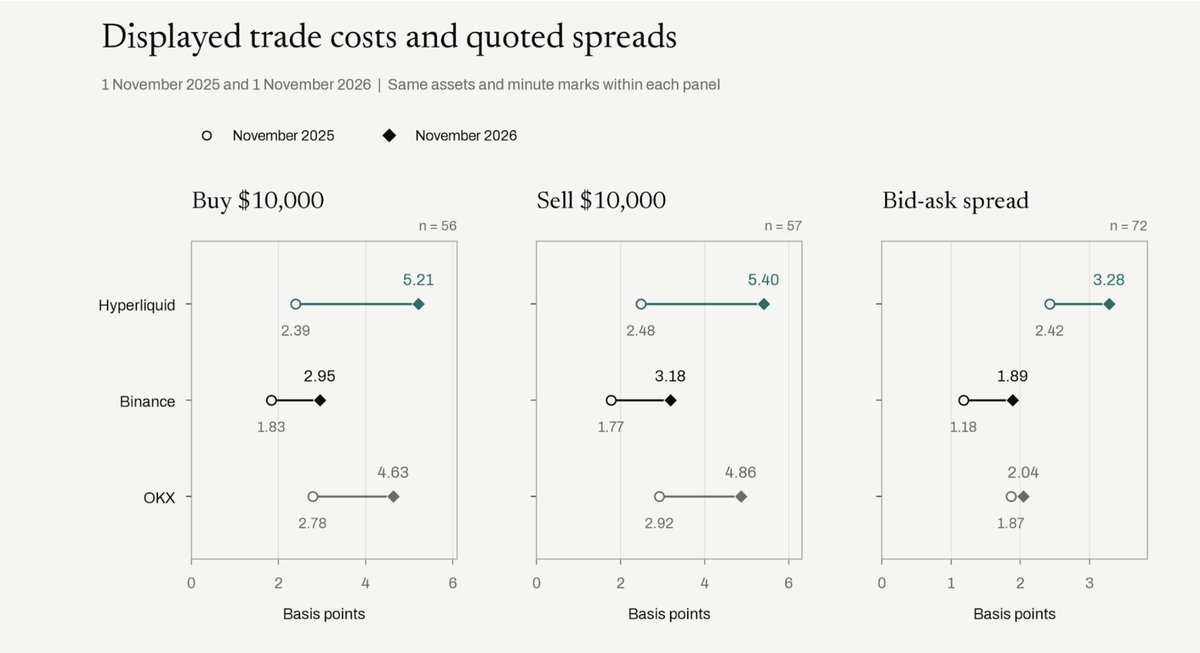
Spread provides an interesting counterexample. Binance's spread actually widened by a larger relative margin (though its spread was narrower to begin with and remains lower in absolute terms).
The Area Closest to Mid Price Shows the Most Obvious Problems
Some may raise a basic objection to the above analysis: if a token's price falls sharply, even if the quantity of tokens in the order book remains unchanged, the USD-denominated depth will appear to have shrunk. To eliminate this factor, we tracked both the USD quoted amount and the token quantity in the order book.
In the Hyperliquid charts, we fixed the asset universe and observation periods across 13 sampling dates. Among these, the 5 basis point sample includes 63 markets, while the broader top 20 basis point sample includes 80 markets.
It should be noted that the screening criteria for these samples are stricter than the earlier sample that only compared two points in time, so the endpoint data here cannot be directly used to replace the earlier comparison results with centralized exchanges (CEXs).
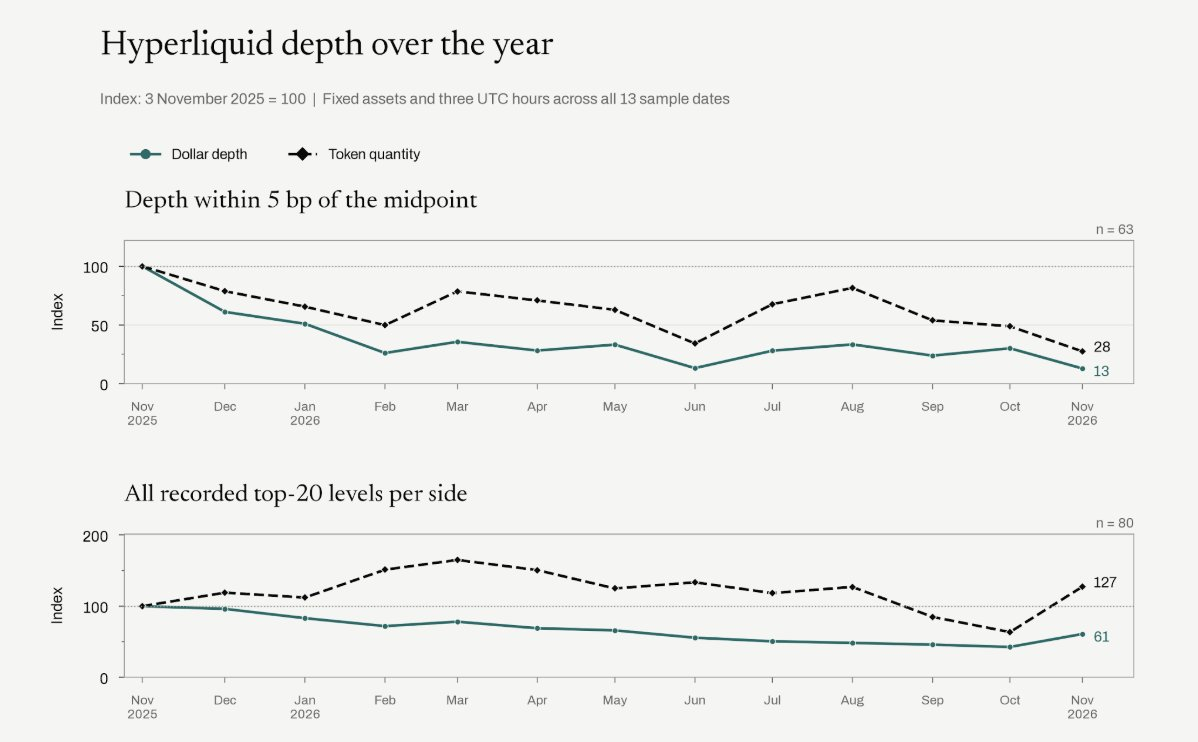
For ease of observation, we set each market's value in November 2025 uniformly to 100. One year later, within the 5 basis point range, based on the median across markets, the USD depth index stood at only about 13, while the token quantity index stood at about 28. In other words, even after excluding the impact of price declines, we still lost the vast majority of the order quantities that originally existed within this price range.
If we further broaden the scope to include all 20 recorded levels of order book depth, the results differ: the median USD depth index ends at 61, while the token quantity index reaches 127. This presents a completely different picture — in the broader sample, the typical market actually has more tokens quoted than before; but within the 5 basis point range closest to the market price, the quantity of quotes has fallen sharply.
In other words, it is not that the order book is completely devoid of liquidity, but that within the price range where we could actually trade, liquidity has become much thinner.
A Closer Look at Some Details
We believe it is necessary to show the data from the past 6 months separately, because during this period, overall depth actually improved (the improvement mainly occurred in areas farther from the market price, rather than the portion closest to the execution price).
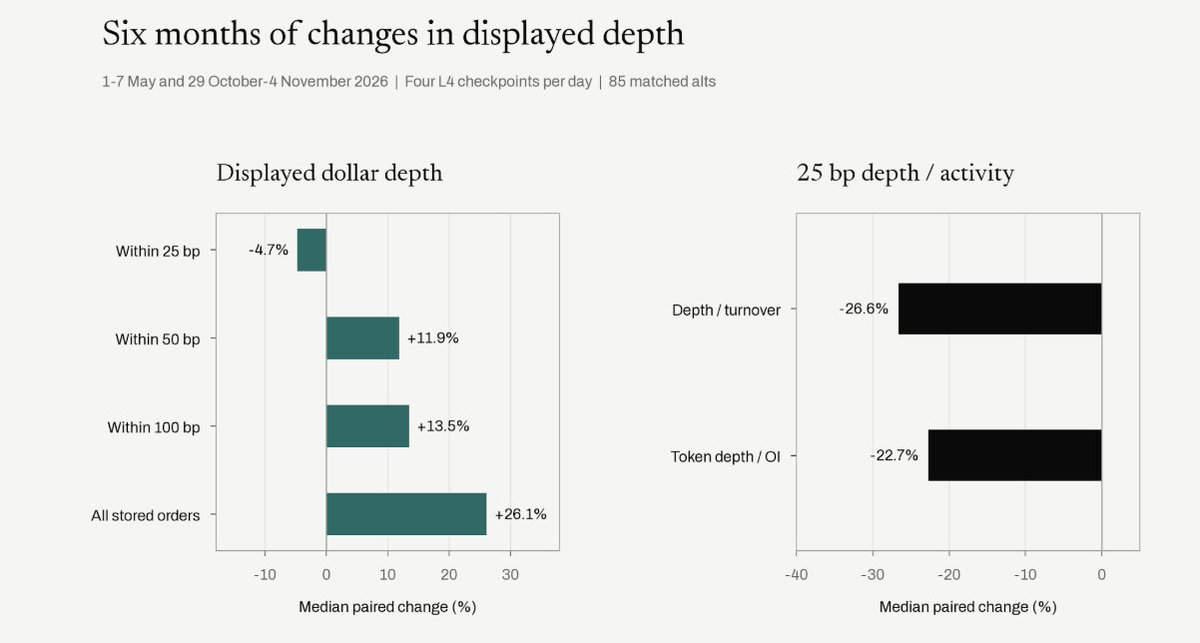
If we further refine the analysis, we can look at spread changes over the past year.
Surprisingly, until recently, Hyperliquid's spreads had been gradually converging toward other platforms. Clearly, we will need to wait some time to confirm whether this is a trend or a random fluctuation.
But the changes currently visible in the order book happen to align with the aforementioned recent market structure concentration and the issues reported by market makers.
Is Market Competition Weakening?
Next, I re-examined the underlying account structure and grouped main accounts with their explicitly associated sub-accounts into the same account group, avoiding double-counting multiple accounts belonging to the same institution. In this way, even if we do not know which company these accounts belong to, we can still identify distinct account systems.
Previously, I had thought that most of the trading volume on the platform might be contributed by a handful of large market makers, but year-over-year volume data does not support this judgment.
I selected a complete week from a year ago and a recent complete week, comparing the same 80 markets. The results show that the median share of market maker volume held by the largest account group actually fell from 25.2% to 14.6%. Therefore, I do not believe the overall decline in liquidity over the past year can simply be attributed to a single market maker dominating the market.
However, what interests us more is what exactly has changed on the quoting side recently.
Now let us narrow the observation window to the most recent month, using the same 72 assets as the spread baseline. The timing here is quite noteworthy: starting around October 30, as liquidity near the market price became increasingly concentrated, spreads widened accordingly.
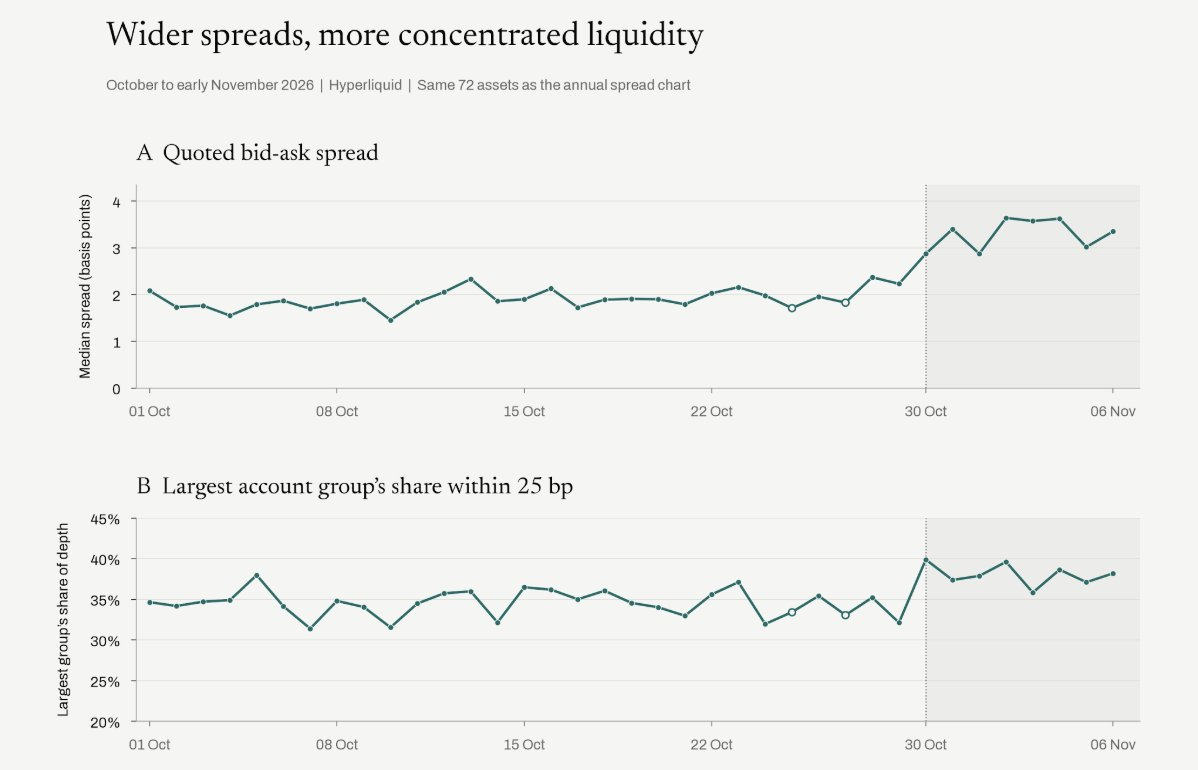
Comparing the periods of October 8–14 and October 31–November 6, we can observe:
- Within 25 basis points of the mid price, the median share of quotes held by the largest account group across markets rose from 34.5% to 38.6%;
- At the same time, the median quoted spread widened from 2.13 basis points to 3.55 basis points.
This aligns more closely with the issues recently reported by market makers.
However, the Binance security incident on October 29 also occurred within this observation window, so based on these curves alone, we cannot definitively attribute this change to priority fees or network congestion.
Looking at individual accounts, we also found that one large liquidity provider sharply reduced its quotes around November 3, while the market share of several other account groups rose at the same time.
This may also be one explanation for the problem. Whether this is indeed the case will require time to verify.
The Problem with the Fee Structure
There is also a rather fundamental issue here: the fee structure.
We compiled historical market maker fees paid by 54 account groups. Based on volume-weighted rates, the bottom quartile of accounts by volume paid an average fee of 0.961 basis points, while the top quartile not only paid no fees but actually received a rebate of 0.236 basis points.
This means that for smaller market makers, before even considering hedging costs and bad fills, the fee gap they need to overcome is already about 1.20 basis points. For a spread of only a few basis points, this is a rather heavy cost. Small market makers are at a clear structural disadvantage.
We can also see declining market participation from the order book quotes themselves.
Among the same 72 markets, comparing the periods of October 8–14 and October 31–November 6, the average number of account groups in a typical market providing at least $1,000 of quotes on each side within 25 basis points of the mid price fell from 7.64 to 6.39. Even holding token prices constant, 58 of the 72 markets still experienced this decline in the number of accounts.
This means that even after excluding the impact of falling token prices, the number of account groups providing meaningful quotes in the area near the market price is still declining.
HIP-4 Also Needs Small Market Makers
Network congestion is another challenge.
According to Hyperliquid's network congestion rules, the platform currently allocates resources based on an address's weighted market-making share from the previous UTC day. During periods of high network congestion, that address can use at most twice its own share of block space. This creates a loop — you need trading volume to obtain an allocation, and obtaining an allocation is a prerequisite for generating trading volume.
When discussing HIP-4 with traders, we repeatedly heard one piece of feedback: when Hyperliquid becomes congested, they simply cannot place orders normally. These smaller market makers have in fact already provided considerable liquidity to the platform.
In our November 10 sample survey of 256 HIP-4 contracts, 47% of the visible depth within 25 basis points of the mid price came from four professional market-making wallets. These markets are still relatively small at present, but for many binary options markets, this situation is not uncommon. If Hyperliquid wants to build a long-tail ecosystem of prediction markets with ample liquidity, it must enable these market makers to participate.
The core point this article most wants to convey is — deep liquidity for long-tail assets was once one of the important reasons traders chose Hyperliquid, and based on the markets we compared, Hyperliquid has already begun to fall behind Binance on this advantage.
If these order books are to remain competitive, the platform must ensure that enough market makers can bear the cost of continuous quoting. If it becomes increasingly difficult for institutions smaller than the top market makers to survive, then losing this competitive advantage is likely only a matter of time. And for HIP-4, success will require ensuring from the very beginning that small market makers can provide quotes stably and reliably.
Hyperliquid should design its mechanisms around this goal.





