


Interpreting Anthropic's 57-Page Investor Roadshow Deck: "Compute" Mentioned 49 Times, Aiming for 35% Long-Term Profit Margin


- Core Takeaway: Anthropic has launched its IPO roadshow, leveraging its AI model capabilities to grow revenue roughly 12x in a year to $17 billion, while betting on long-term growth with approximately $900 billion in compute commitments, emphasizing both safety and compute.
- Key Elements:
- Q3 2026 revenue of $16.956 billion, more than 12x the same period last year; annualized run-rate revenue of approximately $81 billion, adjusted operating margin of 15%, GAAP basis -3%.
- In the roadshow video, "compute" appeared 49 times, topping the list, while safety-related terms appeared 27 times; the revised S-1 pre-estimates compute and infrastructure spending at approximately $895 billion.
- Paid large customers (paying over $100,000 annually) exceed 11,900, growing nearly 8x in a year; net revenue retention rate of approximately 900%, with 79% of revenue coming from outside the top five customers.
- During the period of over 45x revenue growth, compute costs grew approximately 10x, with compute efficiency rising from 0.40x to 1.72x; Q3 saw a margin pullback due to $5 billion in short-term compute commitments.
- Total compute commitments of approximately $900.9 billion, of which about $451.6 billion is expected to occur before the end of 2030; total liquidity of $216 billion prior to listing.
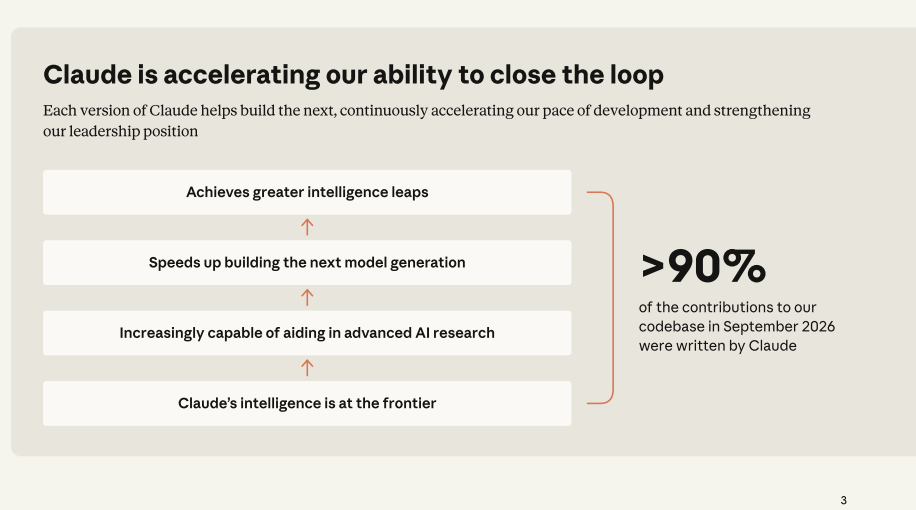
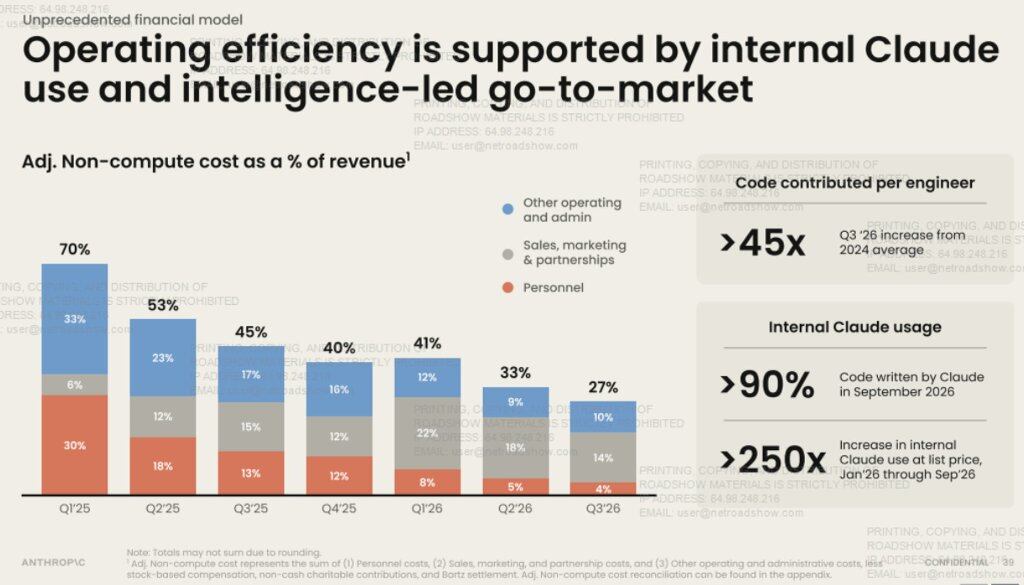
- Internal use of Claude has yielded remarkable results: code output per engineer exceeds 45x that of 2024, over 90% of codebase contributions are written by Claude, and personnel costs as a share of revenue have dropped from 30% to 4%.
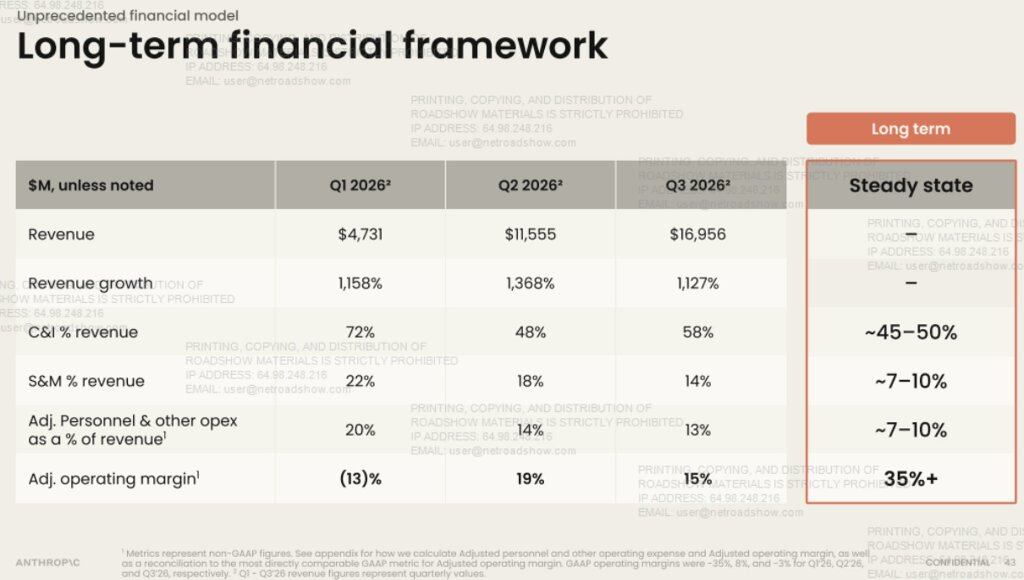
- Long-term target of adjusted operating margin above 35%, with compute and infrastructure costs as a share of revenue declining to 45%-50%; average spending by Fortune 500 customers accounts for less than 0.1% of their total expenses, indicating penetration is still at an early stage.
Original author: Long Yue
Original source: Wallstreetcn
Anthropic officially launched its IPO roadshow on November 10, simultaneously releasing a 42-minute roadshow video and a 57-page roadshow PPT. The price range was set at $70 to $78 per share, with pricing planned for November 18 and listing on Nasdaq on November 19 under the ticker symbol ANT.
In the roadshow video, the first person to appear was CEO Dario Amodei. Within about 30 seconds of his opening, he mentioned that AI could be used to manufacture bioweapons. He simultaneously called AI "the most promising technology in human history," saying it "captures the essence of cognition," and emphasized that safety is the company's top priority. In the video, aside from "Claude" and "model," the most frequently appearing word was "compute," 49 times, with safety-related terms appearing 27 times.
Beyond the video, the company simultaneously released a 57-page PPT. The PPT showed that Q3 2026 revenue was $16.956 billion, more than 12 times the same period last year, with an adjusted operating margin of 15% and a GAAP figure of -3%. Compute commitments totaled approximately $900.9 billion, with a long-term margin target of over 35%.

The Most Mentioned Word in the Roadshow: Compute
Business Insider asked ChatGPT and Claude to separately analyze the video transcript and tally high-frequency words and themes. According to the report, after excluding "Claude" (65 times) and "model" (58 times), "compute" ranked first with 49 mentions, followed by customer (42 times), work (39 times), AI (39 times), and frontier (32 times). Safety-related terms appeared 27 times, ranking tenth.
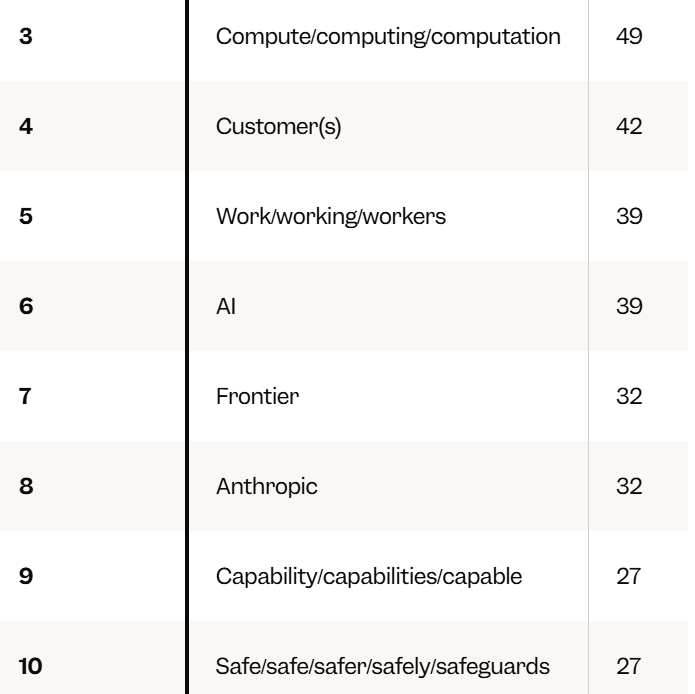
When tallied by combined themes, "models and training" ranked first with 83 mentions, "compute and infrastructure" 81, "financial performance and growth" 77, "efficiency and value" 69, "customers and enterprise" 62, and "safety, alignment, trust and risk" 55, ranking sixth.
The reason compute occupies such a large portion is directly related to the company's capital needs. According to Anthropic's revised S-1, the company expects to spend approximately $895 billion on compute and infrastructure, with nearly half expected to occur before the end of 2030.
Regarding the safety issues that the outside world cares about, the company stated:
We found that safety did not hold us back. Precisely because we can trust Claude's work, we can apply its discoveries to the real world for the benefit of all.
Revenue: About $1.4 Billion in a Single Quarter a Year Ago, Now $17 Billion
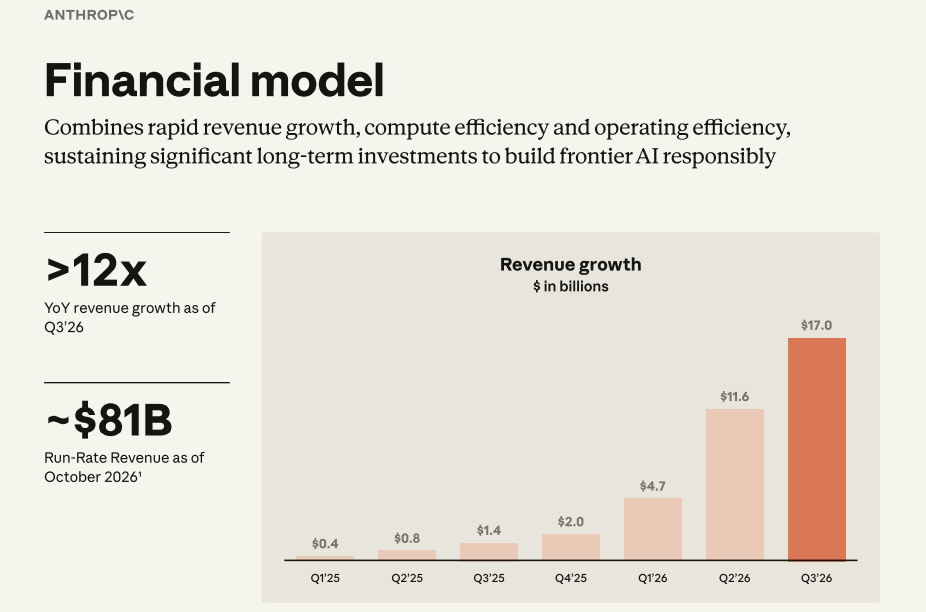
The PPT showed that Anthropic's Q3 2025 revenue was $1.382 billion, and Q3 2026 was $16.956 billion. As of October 2026, annualized run-rate revenue was approximately $81 billion.
By the company's definition, run-rate revenue is the sum of two parts: usage-based revenue over the most recent 28 days multiplied by 13, plus subscription fees for the month multiplied by 12.
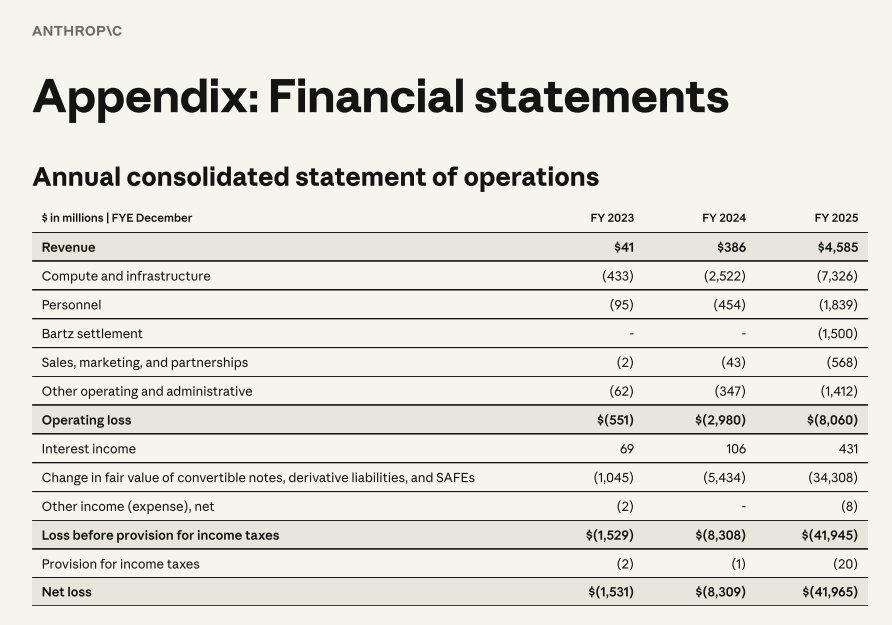
Annual data showed that the company's revenue was $41 million in 2023, $386 million in 2024, and $4.585 billion in 2025. Net loss in 2025 was $41.965 billion, which the appendix said was mainly due to fair value changes in convertible notes, driven by rising enterprise valuation.
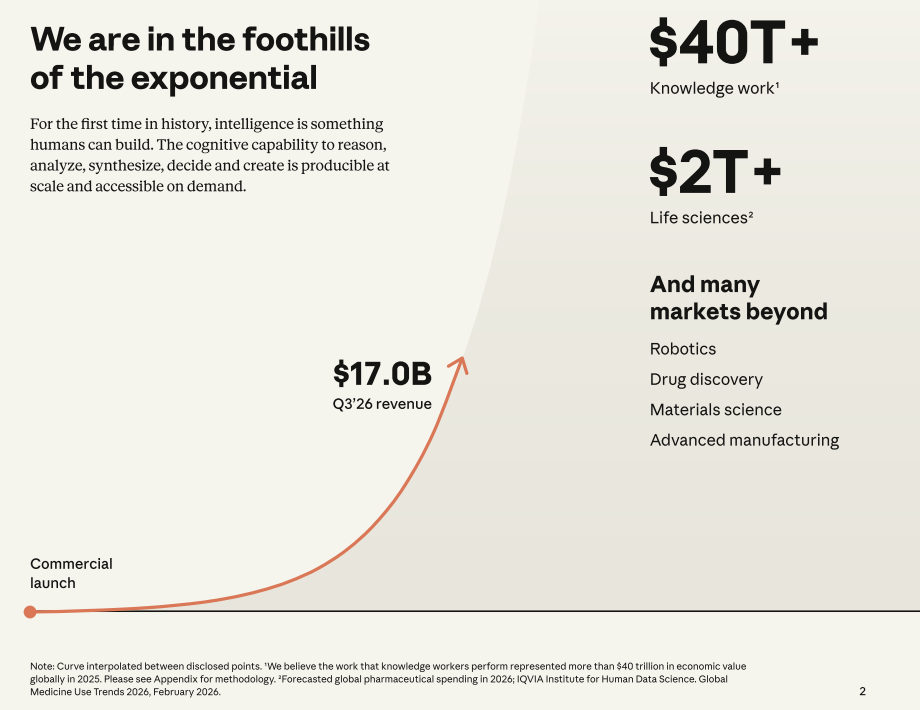
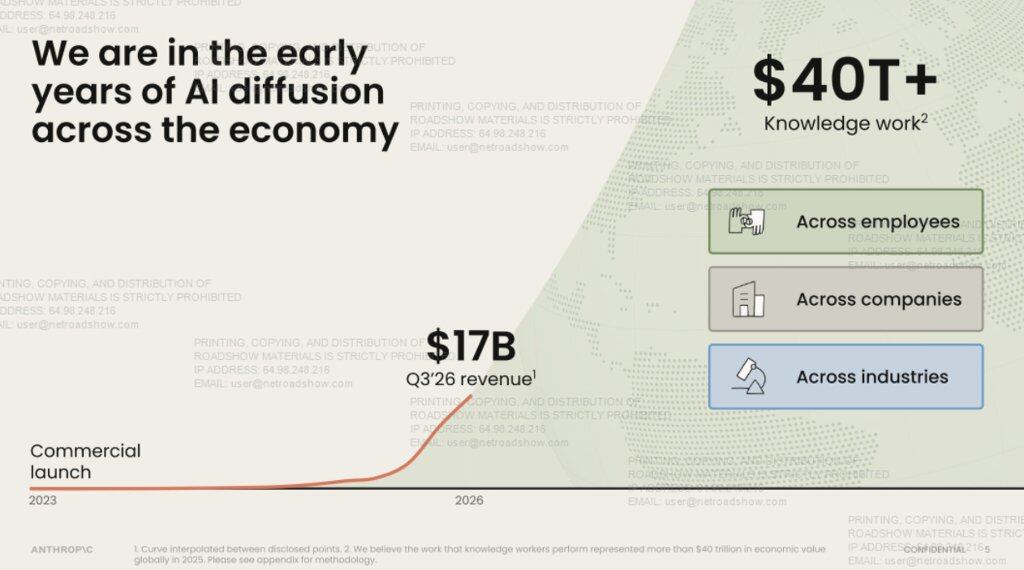
The company's assessment of the market opportunity is: the global economic value created by knowledge work in 2025 exceeded $40 trillion, and current revenue is at an "early stage." This is the company's own estimate (based on U.S. Bureau of Labor Statistics occupational wage data, then extrapolated globally using the International Labour Organization's labor income share of GDP).
Models: 250 Models, Products, and Features Already Released
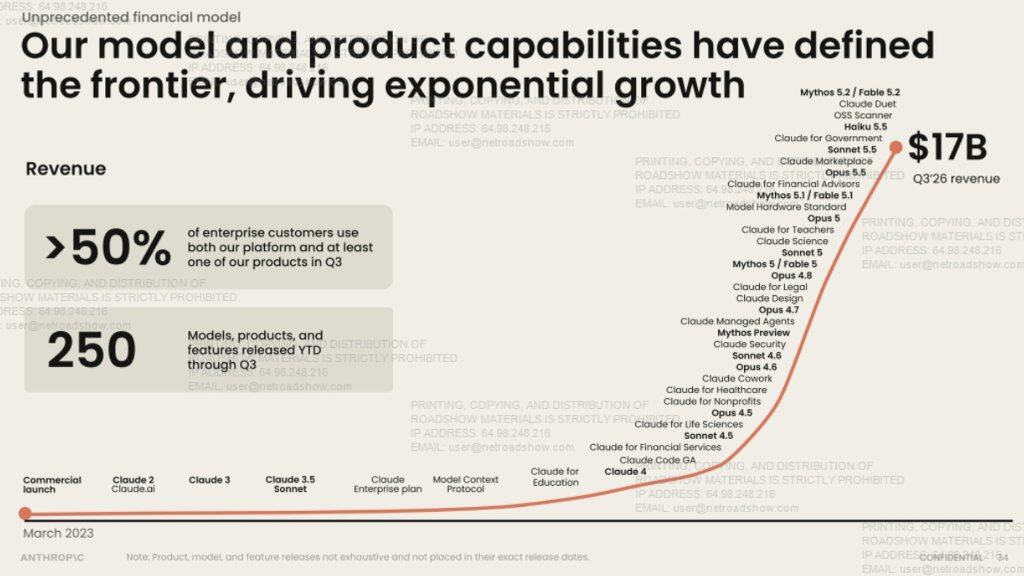
The PPT uses a single curve to describe this growth. The curve starts from commercialization in March 2023, marks nodes such as Claude 2, Claude 3, and Claude Code along the way, and ends at approximately $17 billion in Q3. The company said that as of Q3 2026, it had released 250 models, products, and features.
Customers: Paying Large Customers Grew Nearly 8-Fold in a Year
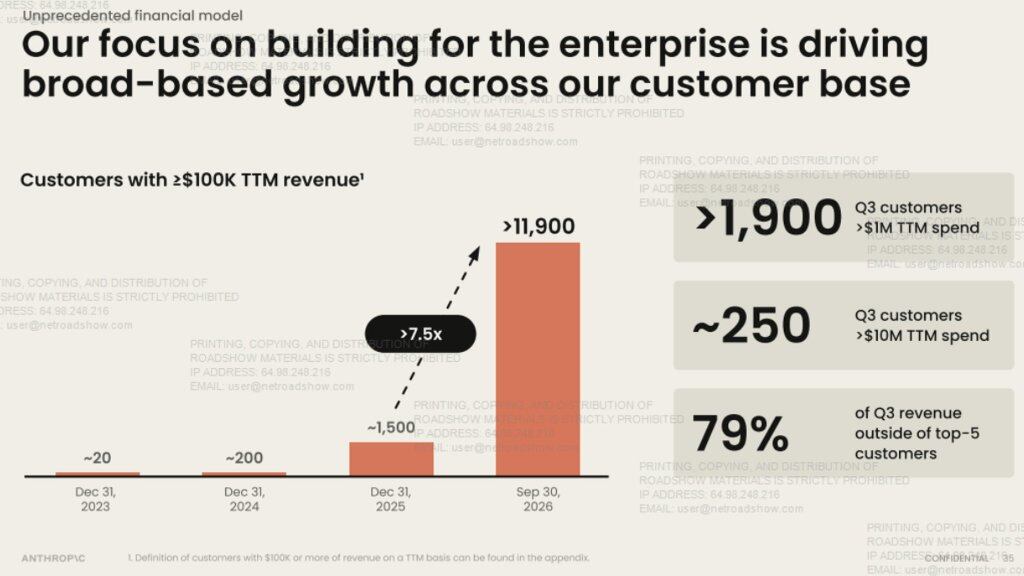
The PPT showed that as of September 30, more than 11,900 customers had contributed at least $100,000 in revenue over the past twelve months. At the end of 2025 there were about 1,500, at the end of 2024 about 200, and at the end of 2023 about 20. More than 1,900 customers spent over $1 million annually, and about 250 spent over $10 million. In Q3, 79% of revenue came from outside the top five customers.
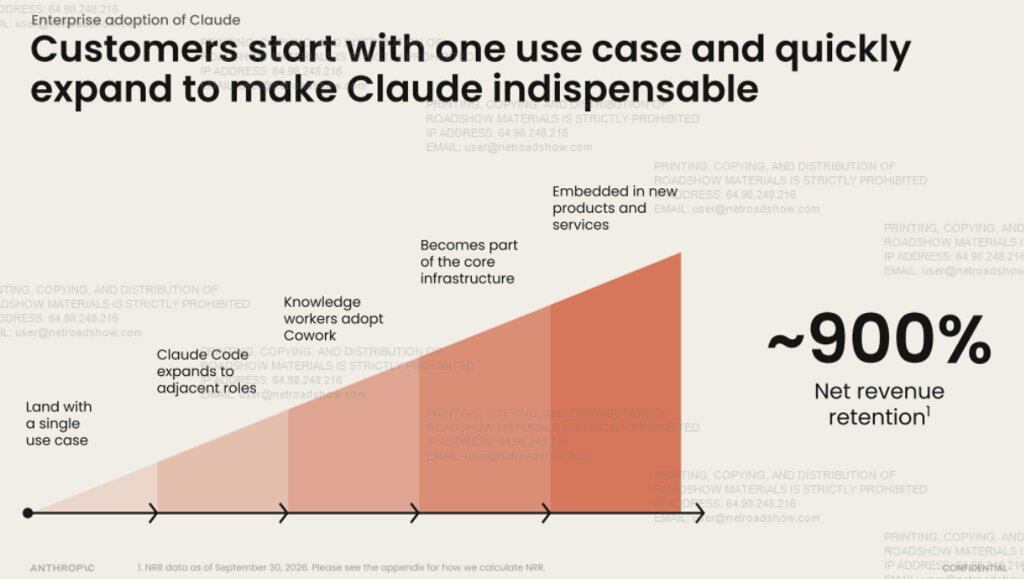
The company disclosed a net revenue retention rate of approximately 900%, meaning the revenue contributed by the same cohort of qualified customers in the current quarter was about 9 times that of the corresponding quarter a year earlier. The statistics exclude fixed-price subscription users such as Pro, Max, and Ultra.
The PPT uses a staircase chart to depict the customer expansion path: first used for one scenario, Claude Code expands to adjacent roles, knowledge workers begin using Cowork, then it enters core infrastructure, and finally it is embedded in customers' own products.
Customers start with one use case and expand rapidly until Claude becomes indispensable.
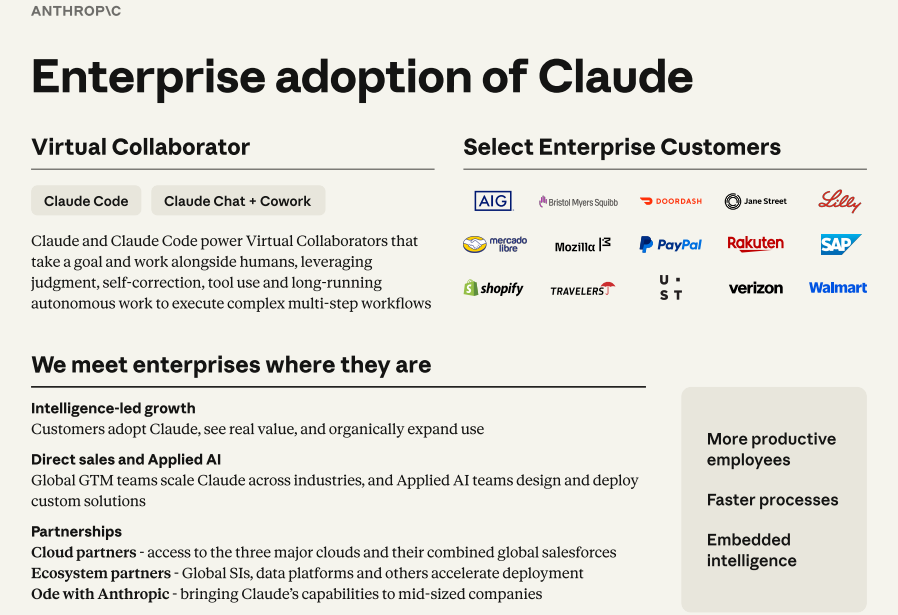
Some of the company's enterprise customers include AIG, Bristol Myers Squibb, DoorDash, Jane Street, Eli Lilly, Mercado Libre, Mozilla, PayPal, Rakuten, SAP, Shopify, Travelers, UST, Verizon, and Walmart. More than 50% of enterprise customers use both the platform and at least one product, up from 30% in Q4 2025.
In terms of sales methods, the company said there are three paths: direct sales and applied AI teams, the three major cloud providers and ecosystem partners, and "Ode with Anthropic" for mid-sized enterprises.
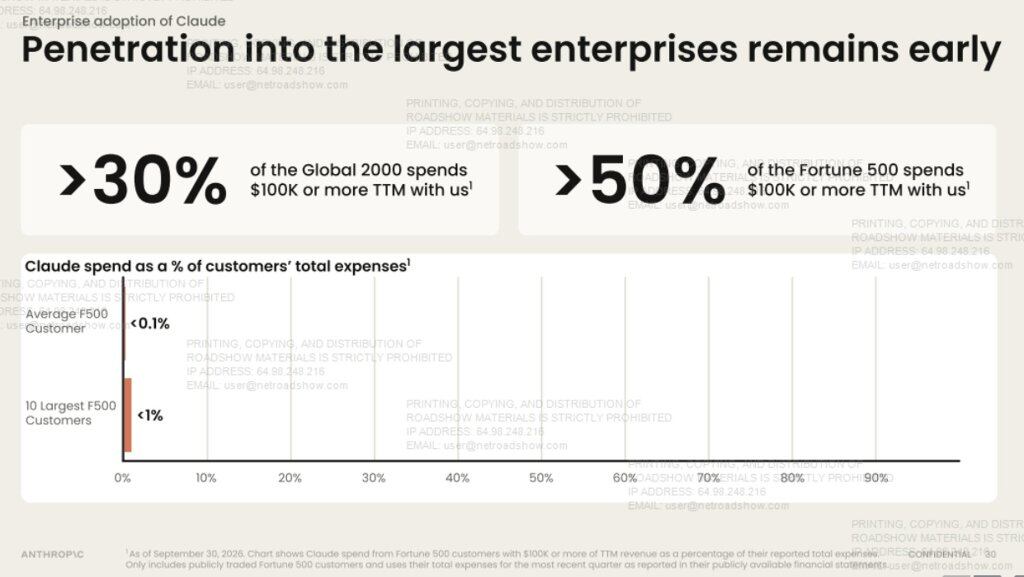
More than 30% of Global 2000 companies and more than 50% of Fortune 500 companies spent no less than $100,000 on Claude over the past twelve months.
But the title of this PPT page is "Penetration of the largest enterprises is still early": the average spending of Fortune 500 customers on Claude accounts for less than 0.1% of their total expenses, and even the top 10 spenders account for less than 1%. The statistics only include publicly listed Fortune 500 customers and use their total expenses for the most recent quarter from public financial reports.
Changes in Model Capabilities
What supports customer expansion is the change in model capabilities.
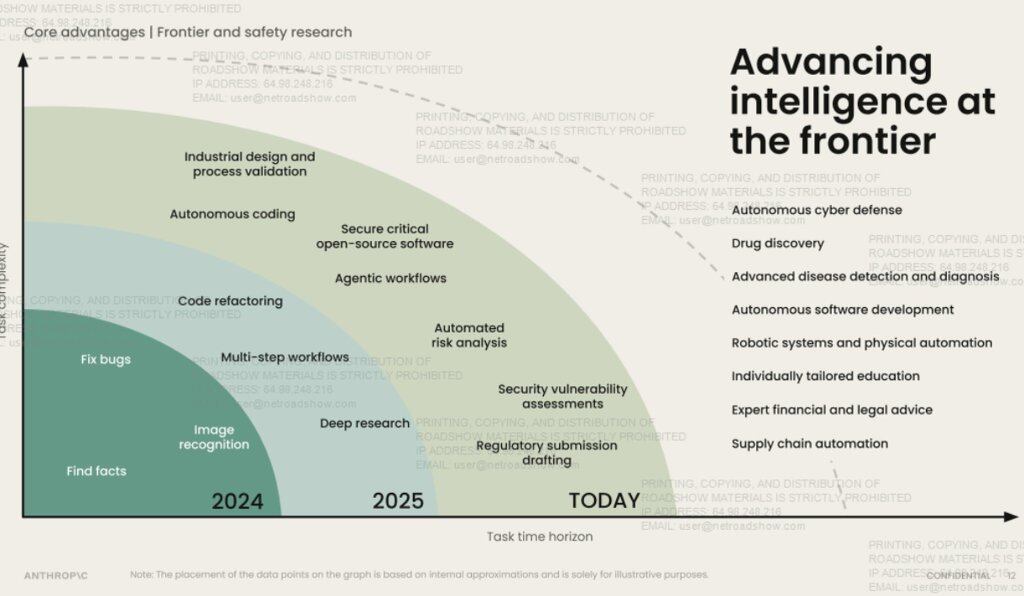
In 2024, the main tasks were fact-finding, bug fixing, and image recognition; in 2025, they expanded to code refactoring, multi-step workflows, and deep research; currently listed tasks include autonomous programming, agentic workflows, security vulnerability assessment, and drafting regulatory filings. Drug discovery, disease diagnosis, and other areas are listed as the next-stage directions.
The product form has also shifted: Claude has gone from a tool that responds to a single prompt to a "virtual collaborator" that can complete long-cycle complex work alongside employees.
Revenue Up 45-Fold, Compute Costs Up About 10-Fold
Since "compute" is the most frequent word in the video, the compute economics in the PPT are the part most worth examining closely.
From Q1 2025 to Q3 2026, revenue grew more than 45-fold, while compute and infrastructure costs grew about 10-fold. The company defines revenue divided by compute and infrastructure costs as "compute efficiency," and this ratio rose from 0.40x to 1.72x, an increase of 4.3-fold.
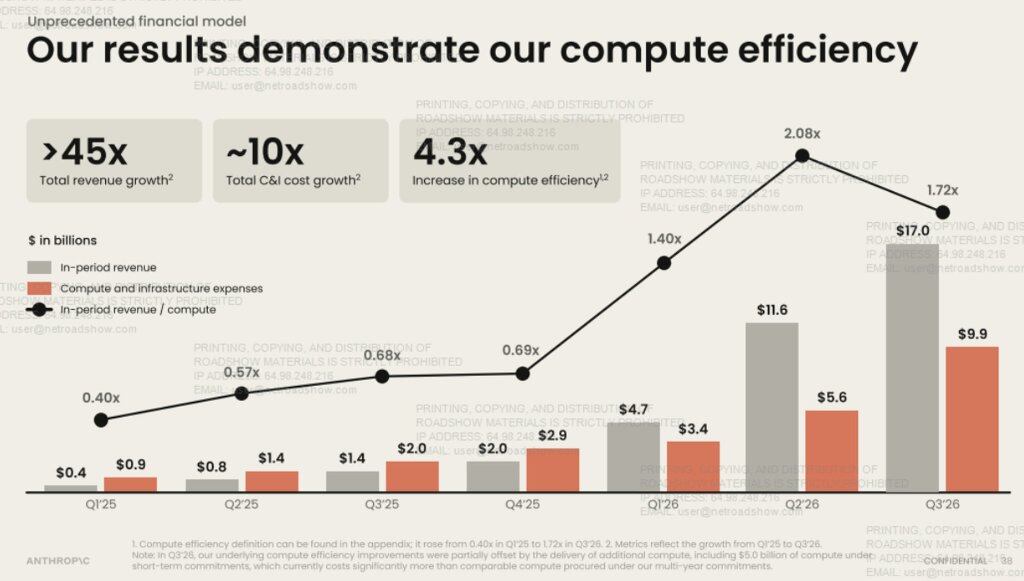
But this ratio did not rise steadily. It was 2.08x in Q2 and fell back to 1.72x in Q3. Q3 compute and infrastructure costs were $9.863 billion.
The company explained that it delivered additional compute during the quarter, including $5 billion of short-term committed compute, whose cost was "significantly higher" than comparable compute procured under multi-year commitments.
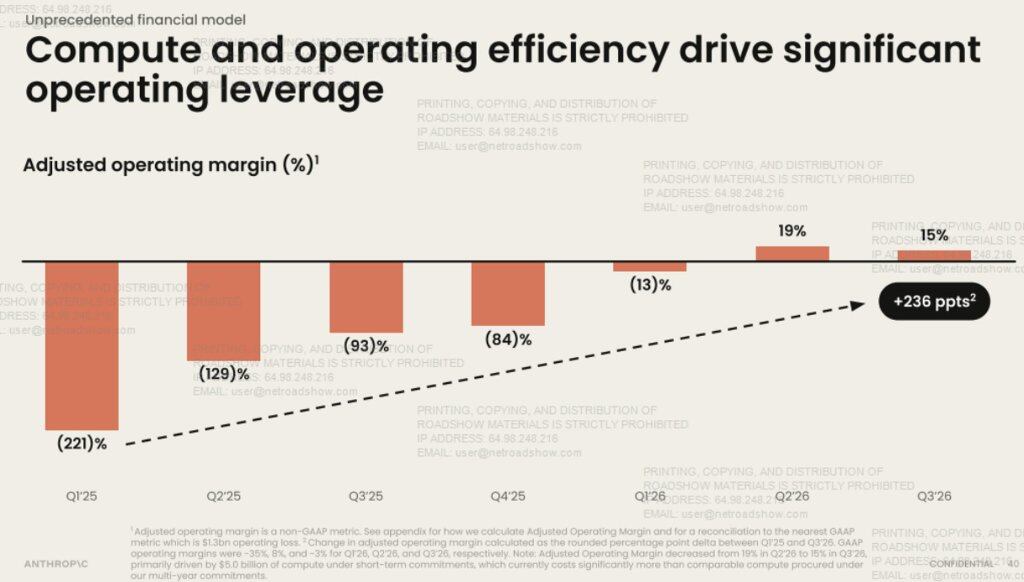
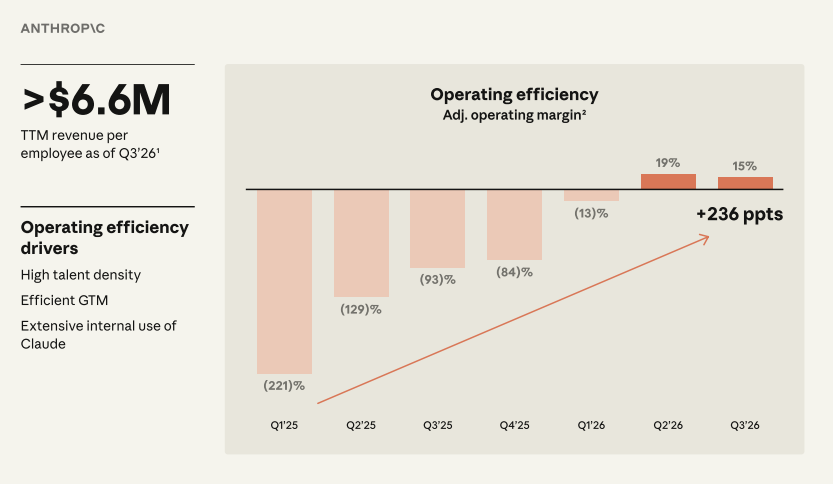
This is directly reflected in margins. Adjusted operating margin rose from -221% in Q1 2025 to 19% in Q2 2026, then fell back to 15% in Q3. In a footnote, the company attributed the decline to the aforementioned $5 billion of short-term compute.
The company views compute as a unified resource pool across multiple partners, involving four types of chips: AWS Trainium, Google TPU, NVIDIA GPU, and AMD GPU, and attributes efficiency gains to compute multiplier research and multi-chip deployment.
The company also disclosed that all seven co-founders are still at the company. The company also describes itself as a public benefit corporation, with a long-term benefit trust currently composed of four trustees with no financial interest, generally empowered to elect a majority of the board. This echoes the "mission" and "safety" repeatedly emphasized in the video.

On the customer side, the company said that improved model efficiency can reduce customer costs. For the same workload, Fable 5.1 costs customers about 25% less than Fable 5, and Opus 5.5 costs about 40% less than Opus 5. The company's statement was:
Higher model efficiency allows us to reduce customer costs while maintaining margins.
Adjusted Margin 15%, GAAP -3%
The "margin" that appears repeatedly in the video and PPT needs to be viewed under two separate measures.
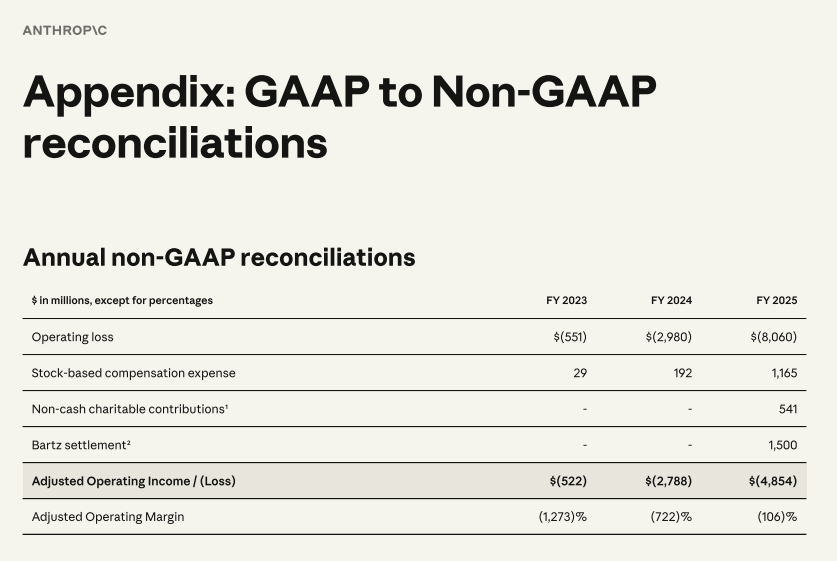
Q3 adjusted operating income was $2.463 billion, corresponding to a 15% margin. On a GAAP basis, operating loss was $567 million, a -3% margin.
The difference comes from adjustments: $1.07 billion in stock-based compensation and $1.96 billion in non-cash charitable donations during the quarter. By the company's definition, adjusted metrics also exclude prior Bartz settlement costs. For full-year 2025, adjusted operating loss was $4.854 billion, with an adjusted margin of -106%.
Q3 net loss was $23.291 billion, including $21.936 billion in fair value changes on convertible notes and similar items.
Long-Term Target: Adjusted Operating Margin Above 35%
On this basis, the company gave a long-term target: adjusted operating margin above 35%. The expense structure is as follows:
As % of Revenue Q3 2026 Long-Term Steady State Compute and Infrastructure 58% ~45%–50% Sales and Marketing 14% ~7%–10% Adjusted Personnel and Other Operating Expenses 13% ~7%–10% Adjusted Operating Margin 15% Above 35%
Itself as the First Customer: Code Output per Engineer More Than 45 Times That of 2024
The company attributes the decline in personnel costs to internal use of Claude.
In Q3 2026, the combined lines of code per active engineer were more than 45 times the 2024 average. This multiple was 1.3x in Q1 2025, 6.2x in Q1 2026, and 10.3x in Q2. The company also said that by September 2026, more than 90% of contributions to its codebase were written by Claude.
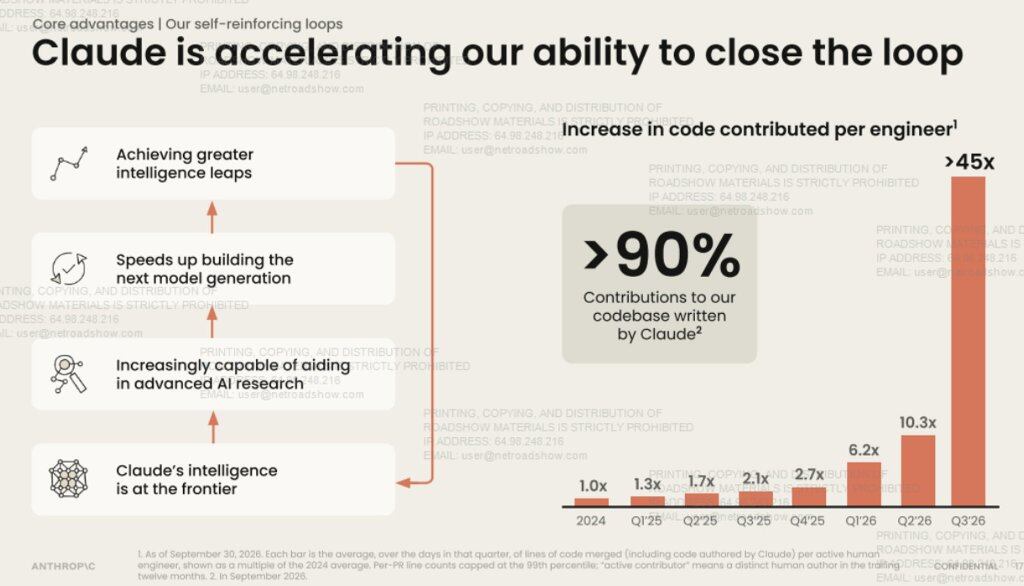
The company calls this logic a "closed loop":
Each generation of Claude helps build the next, continuously accelerating our development pace.
In addition, adjusted non-compute expenses as a share of revenue fell from 70% in Q1 2025 to 27% in Q3 2026. Among them, personnel expenses fell from 30% to 4%, other operating and administrative expenses fell from 33% to 10%, and sales, marketing, and partner expenses rose from 6% to 14%. The page also disclosed that, at list prices, internal use of Claude grew more than 250-fold from January to September 2026.
Revenue per employee over the past twelve months exceeded $6.6 million, including full-time and part-time employees.
Compute Commitments of About $900.9 Billion, Pre-IPO Liquidity of $216 Billion
As of September 30, the company had total contractual obligations of $320 billion, including $313.8 billion in purchase commitments (mainly cloud provider hosting). Signed but not yet commenced leases were $451.2 billion, minimum consumption that can be canceled or is due within 12 months was $17.4 billion, and agreements newly signed after September 30 were $105.7 billion. The total was approximately





