


Brief bull market comeback—which altcoins are worth buying?


- Core Viewpoint: After Democrats won both chambers in the U.S. midterm elections, limiting Trump's policy agenda, the crypto market staged a strong rebound following the "bad news priced in," with BTC breaking above $81,000. This article identifies four altcoin targets that are consistently profitable and have buyback-and-burn mechanisms, from the perspective of protocol revenue.
- Key Elements:
- Hyperliquid generated $66.87 million in revenue over the past 30 days, with a cumulative total of approximately $557 million year-to-date. 99% of fees go to the Assistance Fund for HYPE buybacks and permanent burns, while the project also advances its U.S. market expansion.
- Pump.fun generated approximately $56.97 million in revenue over the past 30 days, with a cumulative total of about $414 million year-to-date, hitting a new yearly high of $62.43 million in October; buyback spending over the past 30 days was approximately $26.16 million, with the buyback ratio already reduced from 100% to 50%.
- Uniswap generated $8.04 million in revenue over the past 30 days, making it the most profitable DEX; after the UNIfication proposal was implemented, Protocol Fees were activated, with revenue flowing into the TokenJar for UNI burns, marking UNI's shift from a pure governance asset to one tied to protocol fees.
- Chainlink generated $4.28 million in revenue over the past 30 days, with a cumulative total of approximately $49.7 million year-to-date. Revenue comes from infrastructure services such as Data Feeds and CCIP, with monthly revenue stable in the $4.4 million to $5.8 million range.
- Through Payment Abstraction and the Chainlink Reserve mechanism, Chainlink automatically converts business revenue into LINK and continuously accumulates it, having facilitated a cumulative transaction value of $36.42 trillion.
Original | Odaily (@OdailyChina)
Author | Asher (@Asher_0210)
Yesterday, the U.S. midterm election results were finalized, with the Democratic Party winning both the Senate and the House. Trump lost majority support in Congress, and his room to push legislation and implement policies over the next two years will be significantly constrained.
As the election results settled, the crypto market, after a brief decline, staged a long-awaited strong rebound last night. BTC briefly broke above $81,000, while ETH approached $2,450. The market seems to be beginning to expect that, as Trump's governance faces more constraints, the shocks from policy flip-flops may weaken, and capital markets may finally have a chance to catch their breath. The earlier fears about Republicans losing both chambers were gradually released, and after the "bad news landed," buying began to return.
The long-dormant crypto market is seeing a rebound, with BTC and ETH leading the charge. Which altcoins should be positioned for next? Protocols that have continued to rake in profits this year may be worth close attention. Below, Odaily starts from protocol revenue and, combined with token buyback, burn, and other mechanisms, outlines four altcoins worth watching.
Hyperliquid: Tens of Millions in Monthly Revenue, Plus U.S. Market Expectations Beyond Buybacks
Aside from the two stablecoin issuers Tether and Circle, Hyperliquid is the most profitable crypto-native project over the past 30 days, with revenue reaching $66.87 million.
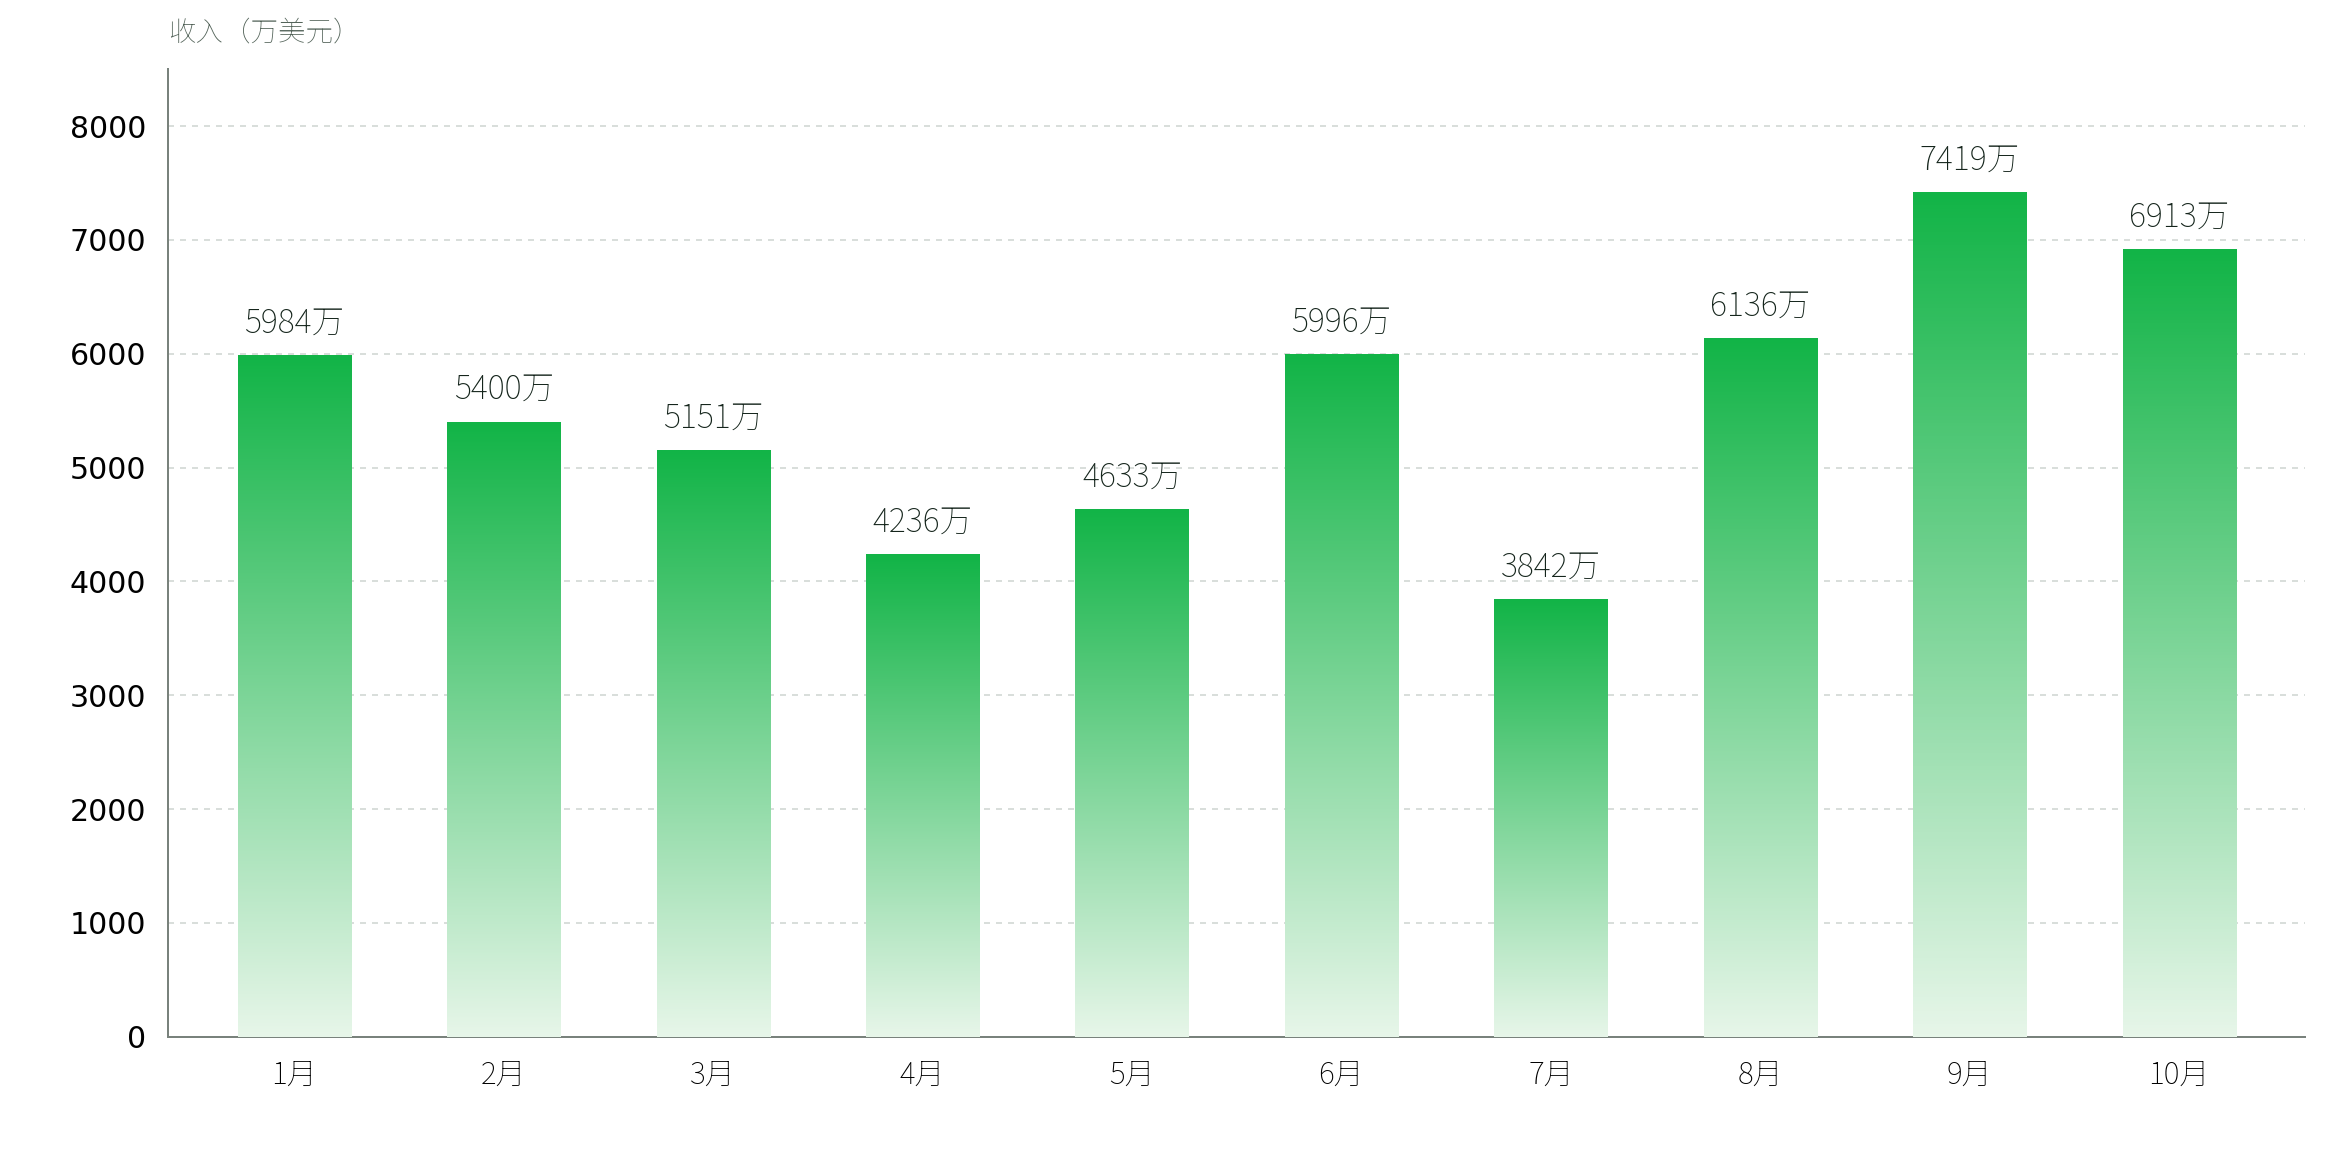
Looking at monthly data, Hyperliquid's protocol revenue from January to October this year was approximately $59.84 million, $54 million, $51.51 million, $42.36 million, $46.33 million, $59.96 million, $38.42 million, $61.36 million, $74.19 million, and $69.13 million, respectively, totaling about $557 million. After revenue fell to its yearly low in July, it climbed back above $60 million in August, hit a new yearly high of $74.19 million in September, and although it pulled back in October, it remained above the levels of every month in the first half of the year.
Hyperliquid's revenue mainly comes from perpetual contract and spot trading fees. The platform currently uses a tiered fee structure. For regular users, the base perpetual contract Taker/Maker rates are 0.045% and 0.015%, respectively, while spot rates are 0.07% and 0.04%. The higher the trading volume and HYPE staking amount, the lower the fees. Funding rates are paid directly between longs and shorts and are not part of Hyperliquid's protocol revenue.
Almost all the money Hyperliquid earns is used to buy back and burn HYPE. Currently, about 99% of the fees generated by the protocol go into the Assistance Fund (SEC filings disclosed that in August 2025, Hyperliquid raised the proportion of protocol fees entering the Assistance Fund from 97% to 99%), which is used to continuously buy HYPE from the secondary market and permanently burn the purchased HYPE.
Beyond existing revenue, Hyperliquid is also advancing its U.S. market presence. In September, Payward, the parent company of Kraken, announced plans to provide on-chain perpetual contract trading for U.S. clients based on Hyperliquid through its licensed entities. In October, Hyperliquid further opened HIP-3* testnet features, supporting deployers in managing trading access through an on-chain whitelist. The related business still requires regulatory approval before launch.
"It earns money, keeps buying back, and now also has the imagination space of the U.S. market" — this may be the most noteworthy investment logic for HYPE at the moment.
Pump.fun: The "Shovel Seller" of the Meme Sector, Profiting from Wave After Wave of Token Launches
Another project with revenue close to Hyperliquid's and that once briefly surpassed it is the leading Meme launch platform Pump.fun — with about $56.97 million in protocol revenue over the past 30 days.
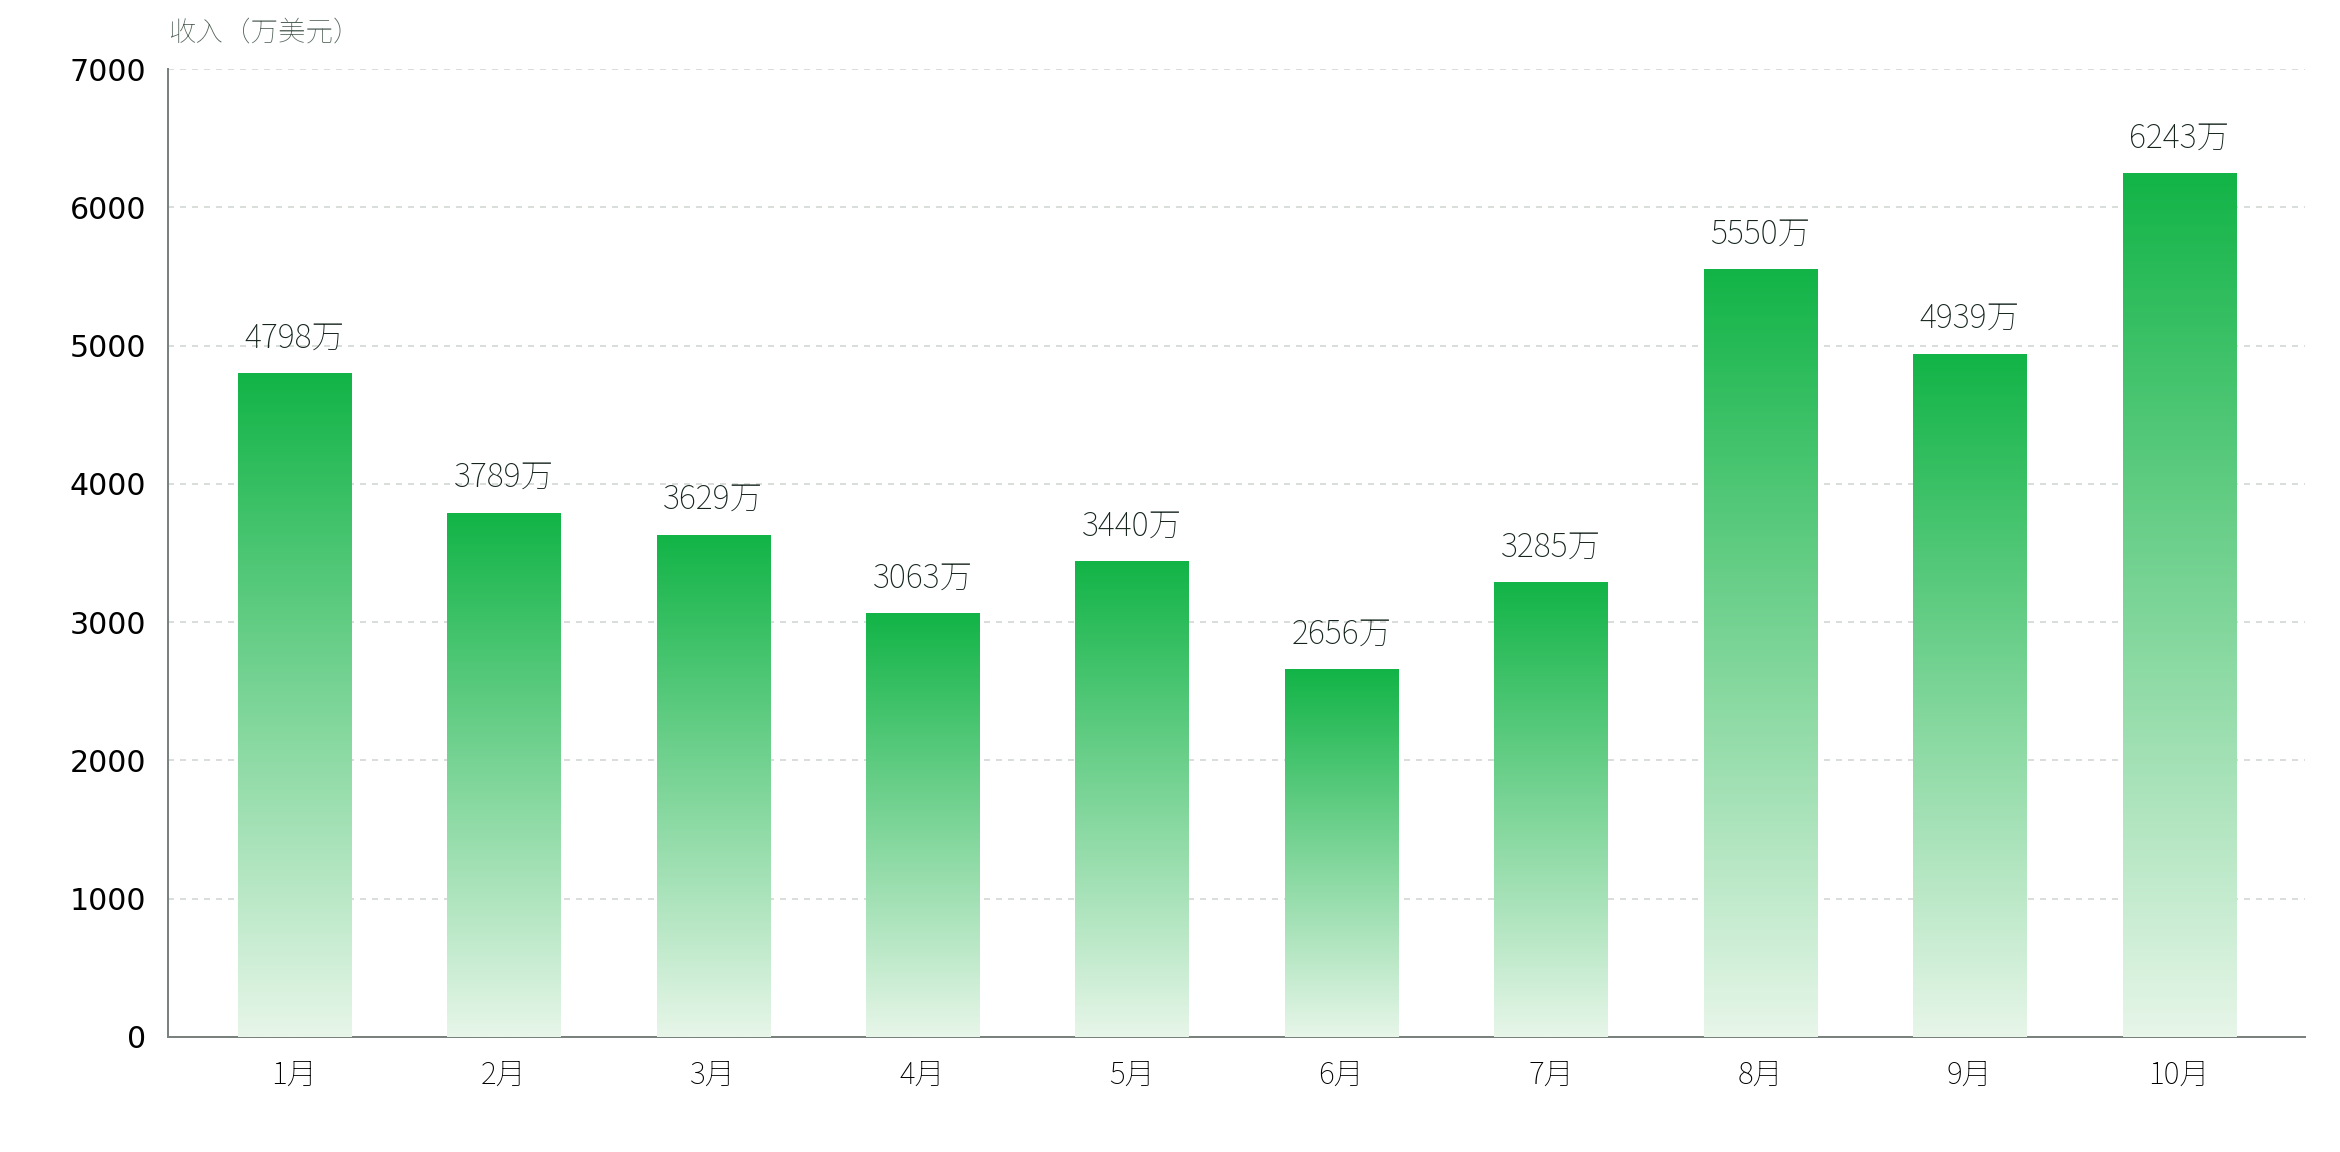
Looking at monthly data, Pump.fun's revenue from January to October this year was $47.98 million, $37.89 million, $36.29 million, $30.63 million, $34.40 million, $26.56 million, $32.85 million, $55.50 million, $49.39 million, and $62.43 million, respectively, totaling about $414 million. Revenue gradually recovered after falling to its yearly low in June, broke through $50 million in August, and hit a new yearly high of $62.43 million in October, up about 26% from September.
Pump.fun's revenue core comes from continuous trading of new coins on the platform. Currently, it is free for users to create tokens, but buying and selling during the Bonding Curve phase requires paying trading fees. According to Pump.fun's latest fee schedule, the total fee rate per transaction on the Bonding Curve is 1.25%, of which 0.95% goes to the protocol and 0.30% is distributed to the token creator. In addition, when a token graduates from Pump.fun to PumpSwap, a graduation fee of 0.015 SOL is also charged.
The money Pump.fun earns is also continuously converted into buy pressure for PUMP. In April this year, Pump.fun lowered its buyback ratio from 100% to 50%, but as platform revenue recovered, buyback spending over the past 30 days still reached about $26.16 million, averaging about $870,000 per day. Although the buyback ratio was halved, the platform is still continuously putting real money into buying PUMP and permanently burning the repurchased tokens.
In September, Pump.fun launched Custom Pairs and Holder Rewards, supporting new coins to pair with assets such as PUMP and tokenized stocks, and allowing creators to share fees with token holders, expanding token issuance and trading玩法.
If you believe the Meme sector will endure, PUMP may be more worth watching than betting on the next Meme coin.
Uniswap: DEX Leader Opens the Fee Switch, UNI Finally Starts "Capturing" Protocol Revenue
Over the past 30 days, Uniswap became the most profitable DEX with $8.04 million in revenue. Although there is still a gap compared with platforms like Pump.fun and Hyperliquid that earn tens of millions of dollars a month, within the DEX sector, Uniswap's profitability has returned to the top tier.
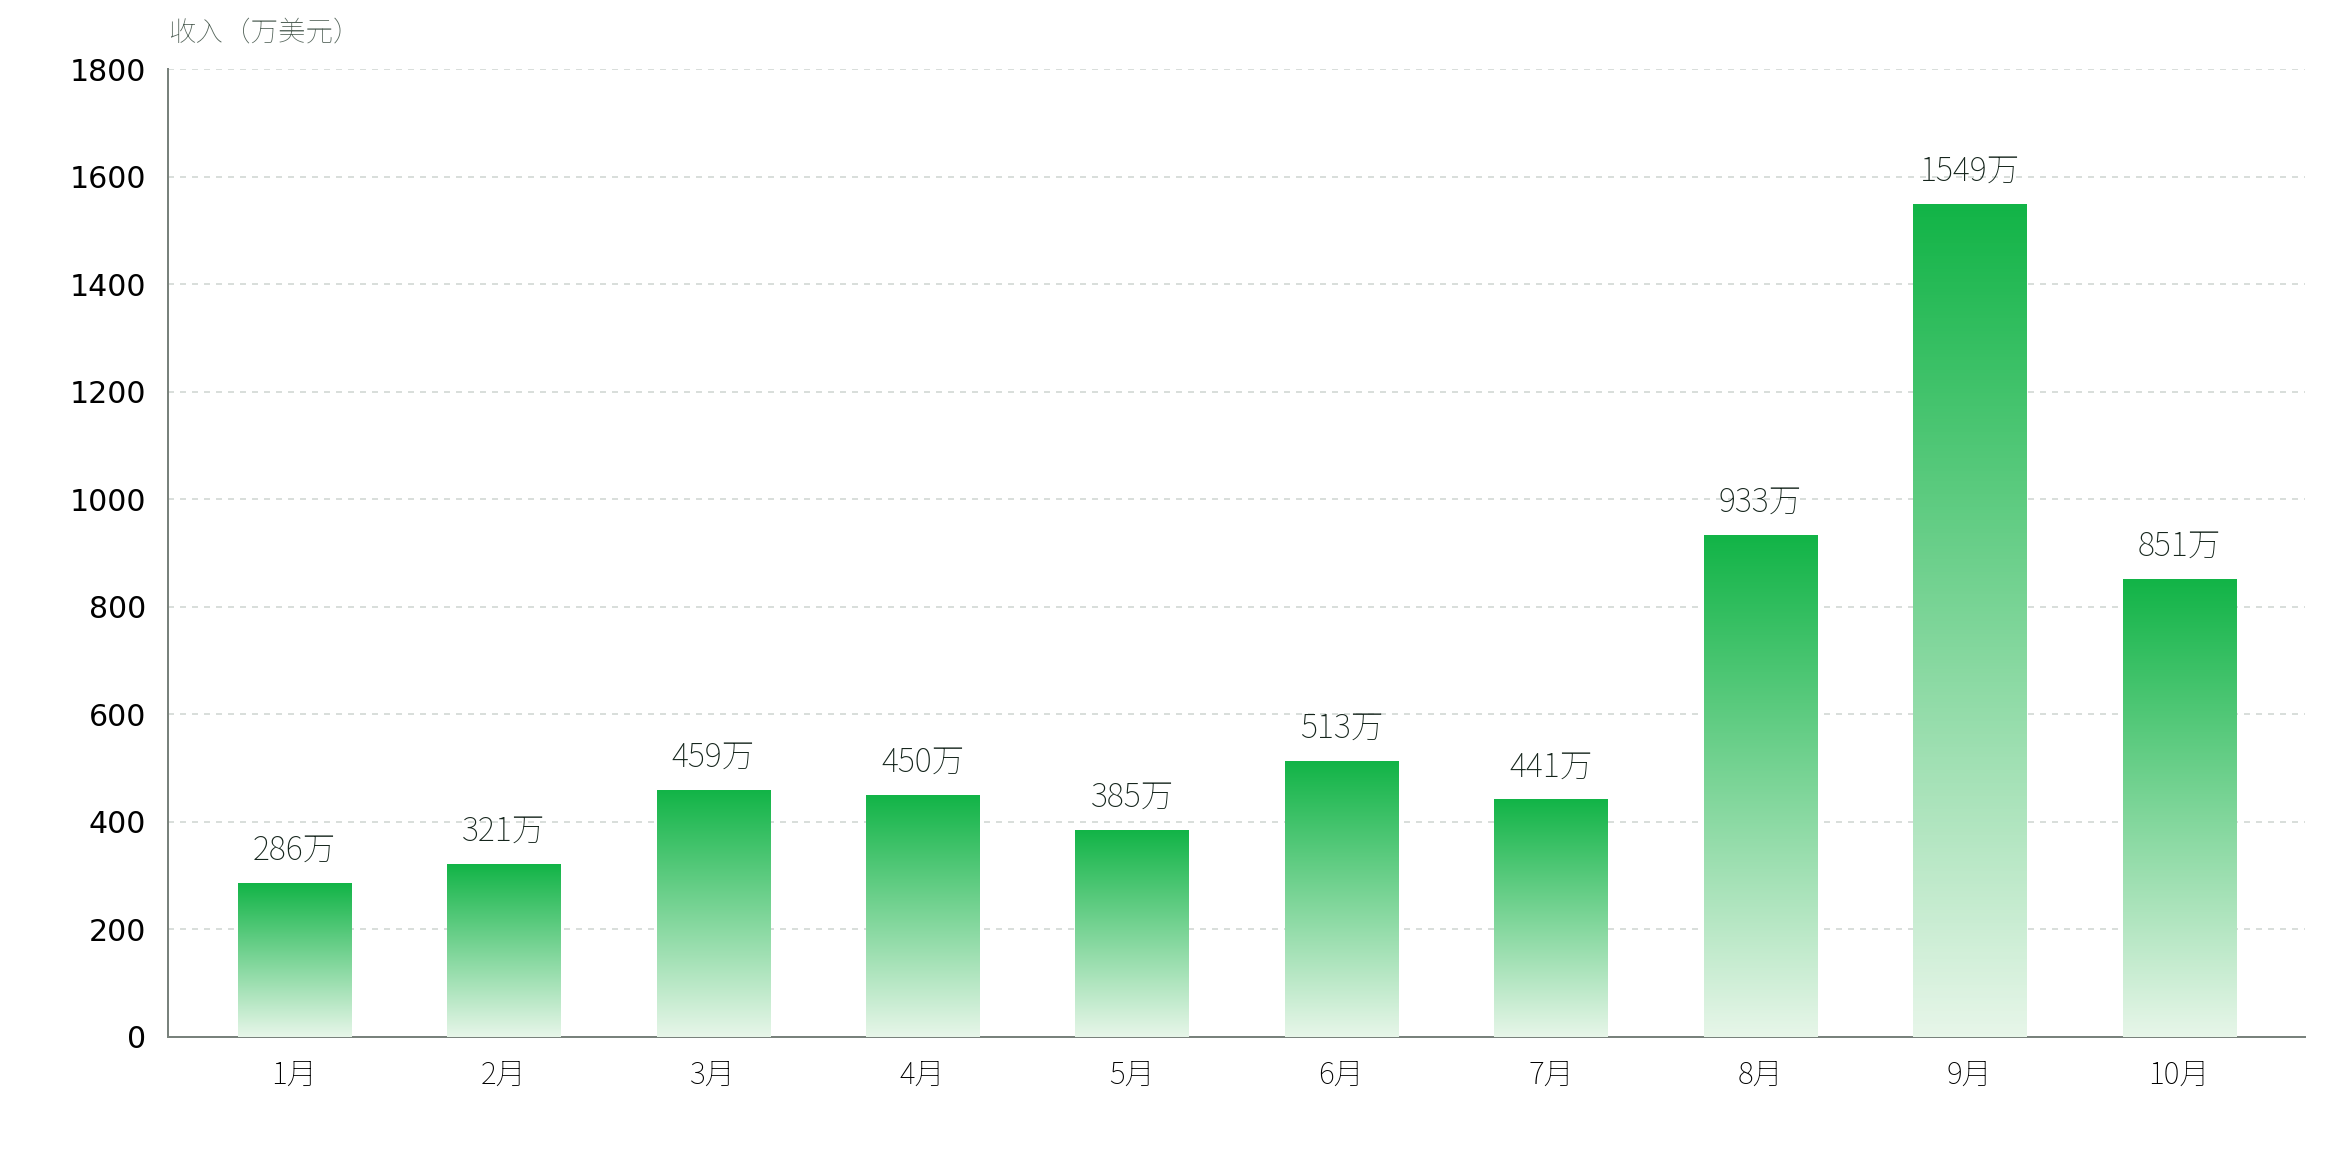
Looking at monthly data, Uniswap's protocol revenue from January to October this year was approximately $2.86 million, $3.21 million, $4.59 million, $4.50 million, $3.85 million, $5.13 million, $4.41 million, $9.33 million, $15.49 million, and $8.51 million, respectively, totaling about $61.88 million. Revenue in the first seven months remained basically around $3 million to $5 million per month, rose noticeably in August, hit a new yearly high of $15.49 million in September, and although it fell back to $8.51 million in October, it remained above the levels of every month in the first half of the year.
Uniswap's revenue comes from the Protocol Fee charged during transactions. Currently, the protocol fee has been activated across all Uniswap v2 pools and some v3 pools, and is gradually expanding from Ethereum to multiple chains including Arbitrum, Base, OP Mainnet, BNB Chain, and Polygon. Taking v2 as an example, users still pay a 0.30% fee per transaction, of which 0.25% goes to LPs and 0.05% enters the protocol; v3 charges the corresponding proportion of protocol fees based on different fee-tier pools.
Since the UNIfication proposal was implemented at the end of 2025, Uniswap officially activated the Protocol Fee and uses the revenue for UNI burning (For more related content, read: After the Uniswap fee switch landed: Is this DeFi transformation's "report card" good enough?). Protocol fees enter the TokenJar, and external participants who want to withdraw the assets accumulated within must simultaneously burn a corresponding amount of UNI.
The UNI token has transformed from a "pure governance asset" into an "asset clearly linked to protocol fees and usage." If DEXs will remain the most fundamental entry point for on-chain trading, dollar-cost averaging into UNI is now at least no longer just an investment in Uniswap's brand and position.
Chainlink: Not Chasing Hype, but Running the "Toll Booth" of On-Chain Finance
Relying neither on Meme hype nor contract trading volume, Chainlink still generated $4.28 million in revenue over the past 30 days. Compared with platforms like Pump.fun and Hyperliquid whose revenue fluctuates with market trading activity, Chainlink is in a more infrastructure-oriented business — as long as on-chain applications such as DeFi, stablecoins, and RWA continue to operate, demand for oracles, cross-chain communication, and data services will not disappear.
Looking at monthly data, Chainlink's revenue from January to October this year was approximately $5.66 million, $4.49 million, $4.45 million, $5.80 million, $4.65 million, $4.60 million, $5.76 million, $4.48 million, $4.46 million, and $5.35 million, respectively, totaling about $49.70 million. Monthly revenue remained basically between $4.4 million and $5.8 million, pulled back in August and September, and rebounded to $5.35 million in October.
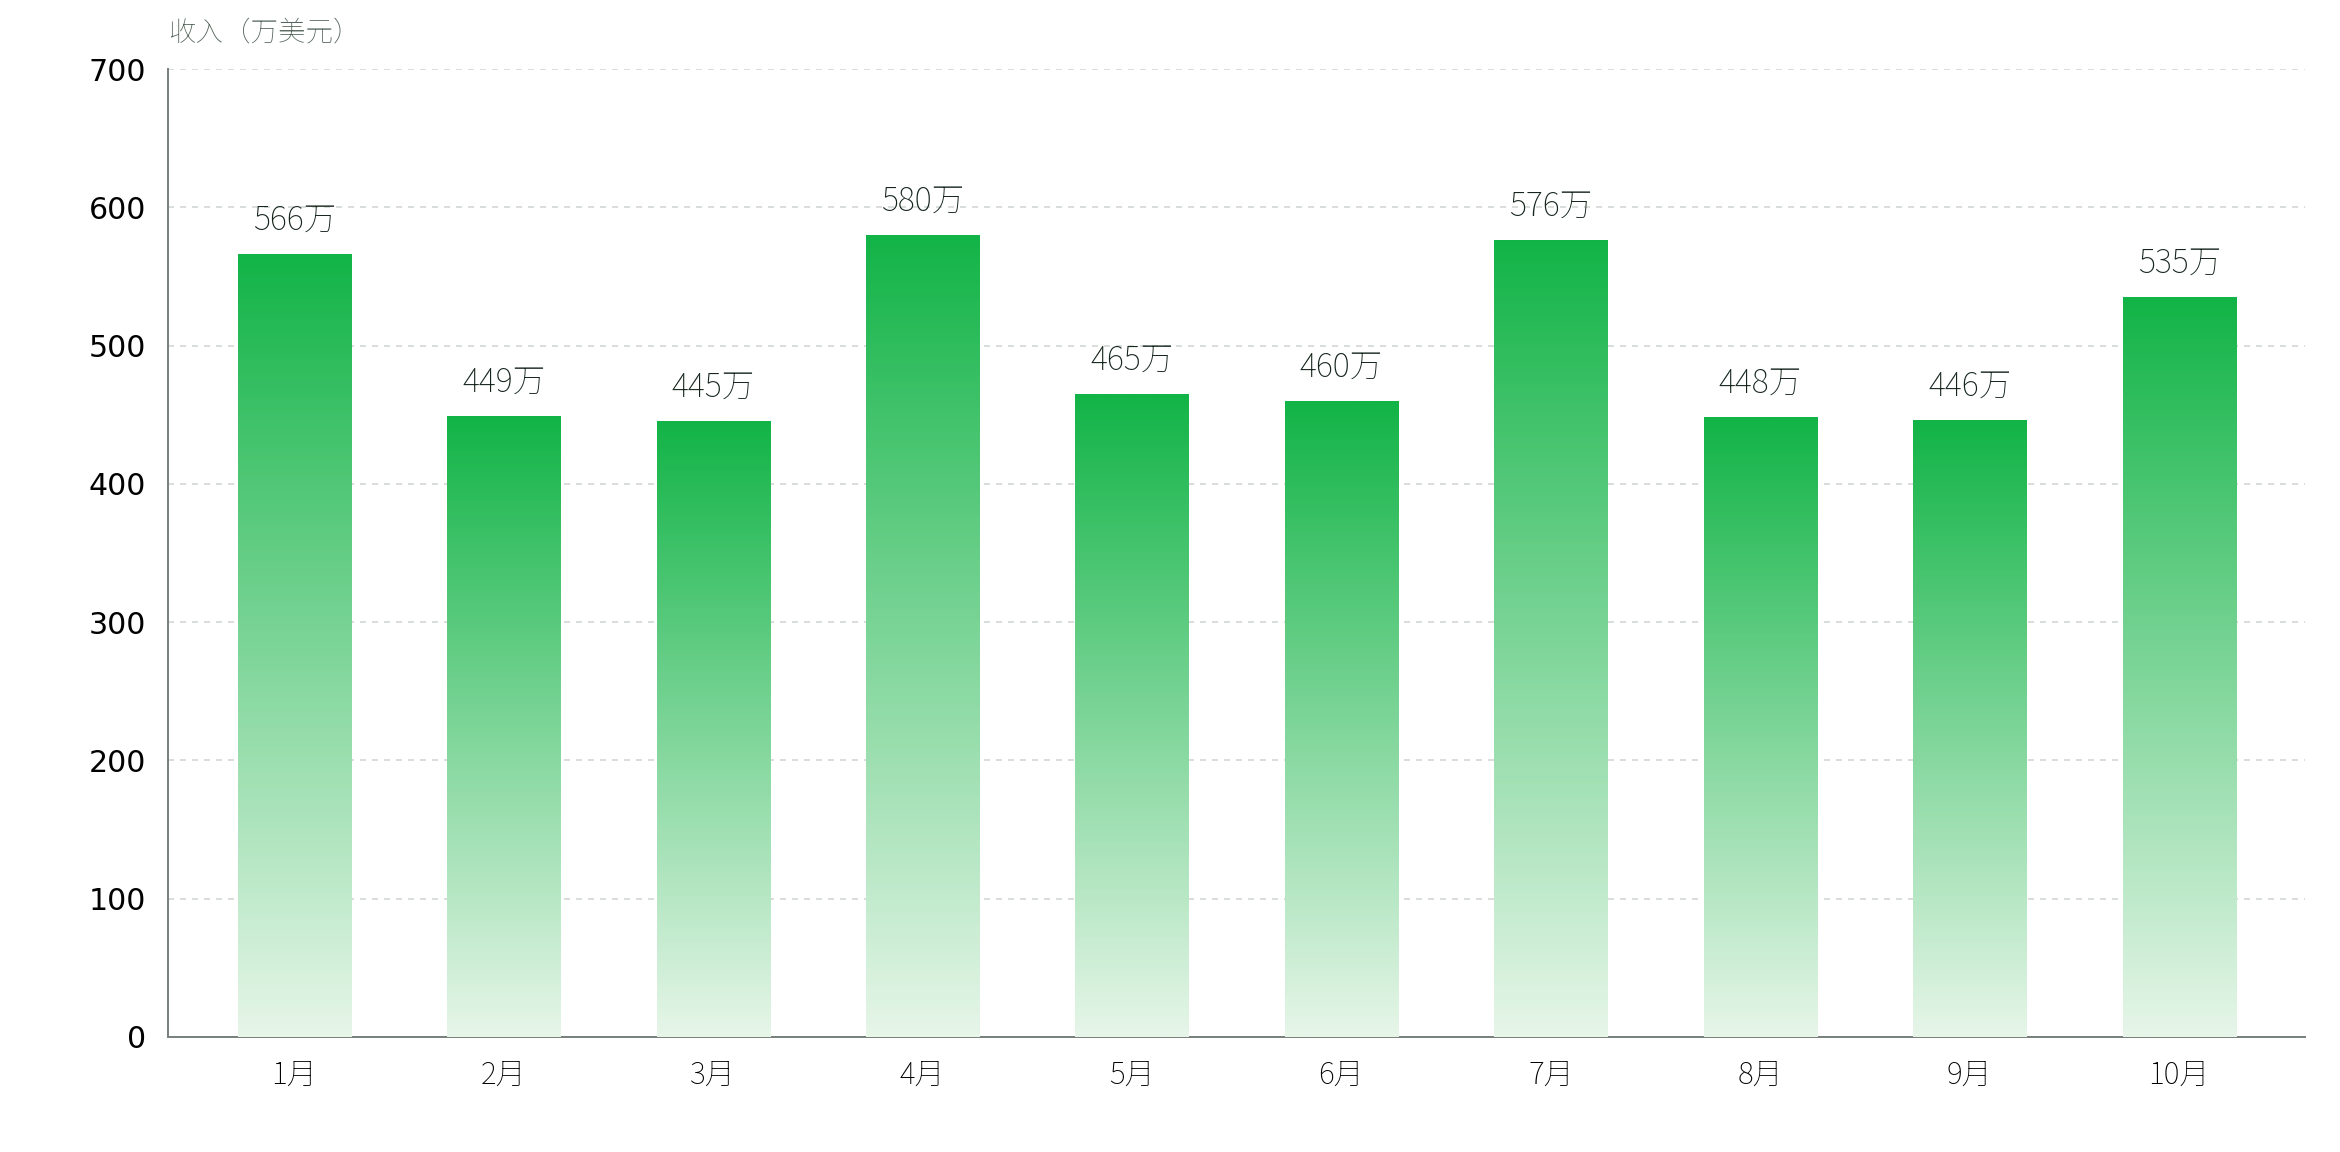
Chainlink's revenue comes from fees paid by developers, protocols, and institutions for using Chainlink services such as Data Feeds, CCIP, Automation, and VRF, covering on-chain foundational needs such as price data, cross-chain communication, and automated execution. Today, Chainlink's services are no longer limited to DeFi and are increasingly entering stablecoin, RWA, and institutional asset tokenization scenarios. Official data shows that as of July 2026, its cumulative Transaction Value Enabled (the value of transactions facilitated by Chainlink) had reached $36.42 trillion.
Currently, Chainlink has launched Payment Abstraction and Chainlink Reserve, gradually converting Chainlink's business growth into sustained demand for LINK. Revenue from on-chain and off-chain services paid by users and enterprises can be automatically converted into LINK through Payment Abstraction and enter Chainlink Reserve for continuous accumulation.
If more financial assets truly move on-chain in the future, Chainlink may not need to bet on which public chain or which DeFi project ultimately wins — as long as on-chain finance continues to expand, this "toll booth" will generate more and more revenue.





