


Has the AI bubble in US stocks already burst?


- Core Viewpoint: In October 2025, the US stock AI sector suffered its most violent sell-off since March, with market value evaporating over $1.5 trillion in a single month. The core market contradiction has shifted to doubts over whether massive AI capital expenditures can generate sustainable commercial returns, with clear signs of the AI trade receding.
- Key Elements:
- The Nasdaq Composite plunged 5.3% in October, with the S&P 500 posting back-to-back monthly declines; the actual top in tech stocks and the semiconductor sector had already formed in June.
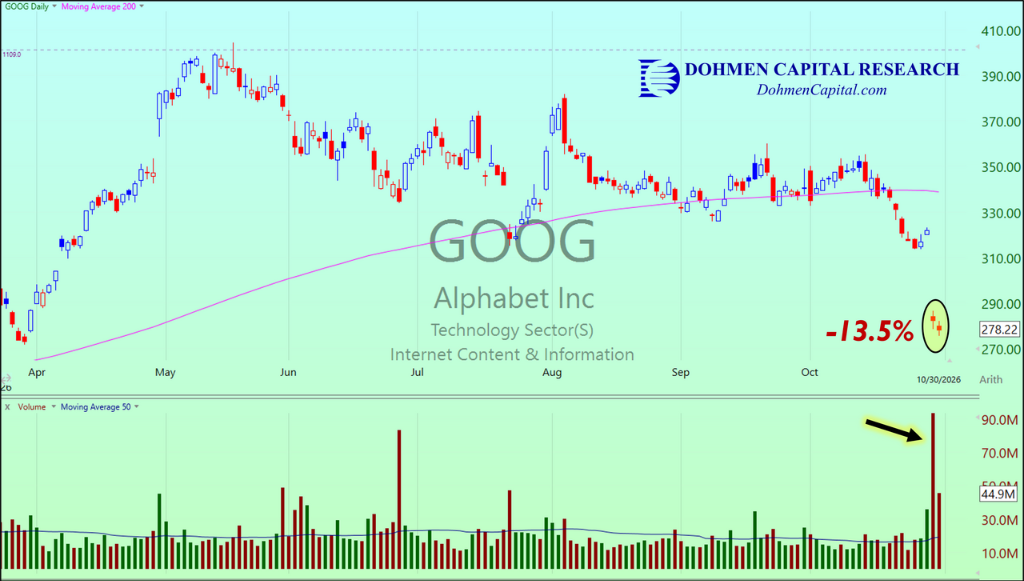
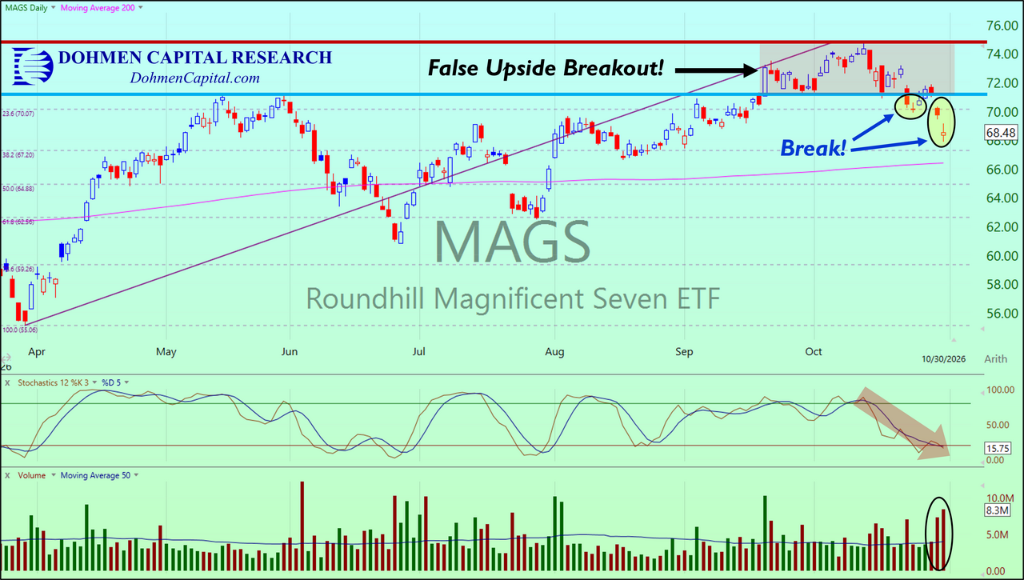
- Alphabet's single-day plunge of 13.5% dragged down mega-cap tech stocks, with MAGS ETF breaking below the key 70-point support, confirming a false breakout.
- Elliott warns of three major hidden concerns in the AI space: circular investments between model companies and infrastructure providers, debt-fueled capital expansion, and the rise of anti-AI social movements.
- Market sentiment could shift from "fear of missing out" to "fear of being destroyed," triggering a chain reaction of leveraged liquidations and margin calls.
- Elliott has already shifted its investment focus to capital preservation, and Dohmen advises against buying the dip in AI stocks.
Author: Dong Jing
Source: Wallstreetcn
Wall Street is going through a costly moment of reckoning. As large-cap tech stocks suffer their most violent monthly selloff since March 2025, doubts about the return on artificial intelligence infrastructure investments are rapidly intensifying, and the retreat from the AI trade is becoming increasingly evident.
On the final trading day of October, U.S. stock market capitalization evaporated by more than $1.5 trillion in a single month, with the Nasdaq Composite plunging 5.3% for the month—its worst monthly performance since March 2025—while the S&P 500 posted back-to-back monthly declines.
In a recent article, Bert Dohmen and Dion Dohmen, senior analysts at market research and investment analysis firm Dohmen Capital Research, wrote that the selloff spread outward from the AI and semiconductor sectors, triggering a chain reaction of mass leveraged liquidations and margin calls, with liquid assets such as gold and silver unable to escape unscathed. Meanwhile, the market's questioning of whether AI capital expenditures can generate meaningful returns has evolved from a fringe issue into the core cloud hanging over the entire sector.
Prominent institutions led by Elliott Investment Management have already sounded the alarm. According to a Wallstreetcn article, the Wall Street Journal reported that Elliott, founded by Paul Singer, stated explicitly in its October letter to investors that "right now, virtually every warning bell that precedes a major bear market is ringing", drawing parallels between the current market environment and the "Roaring Twenties" that preceded the Great Depression.
This assessment resonates strongly with the analysis in Bert Dohmen and Dion Dohmen's latest article—both point to the same core question: Who, exactly, is going to pay for AI?
Hundreds of Billions in Market Value Wiped Out, AI Takes the Brunt
The destructive force of October's market was stunning. Bert Dohmen and Dion Dohmen noted in their article that the $1.5 trillion in U.S. stock market value erased in a single month is three times the roughly $500 billion lost in a single day during the "Black Monday" crash of 1987.
The triggers were ignited one after another. After Meta's Q3 earnings were released after the close on October 21, market sentiment took a sharp turn; on October 28, Microsoft and Google reported results in succession, with Google's parent company Alphabet plunging 13.5% in a single day, dragging down the entire mega-cap tech cohort.
The MAGS ETF, representing the "Mag 7," saw its momentum rapidly decay from its October 13 peak, closing below the key 70-point support level for two consecutive days at the end of October, confirming that the earlier upside breakout was a false breakout.
What is worth noting is that the actual top of the tech and semiconductor sectors had already formed back in June of this year, when the market did not attract widespread attention. Dohmen and Dohmen emphasized in their article that real market tops often emerge months before a dramatic crash, and by the time most investors become aware of the risk, they are often already trapped.
Who Pays for AI? The Core Contradiction Emerges
The fundamental driver behind this AI trade retreat is that the market has begun to confront a long-avoided question: can massive AI infrastructure spending be converted into sustainable commercial returns?
Dohmen wrote in the article that concerns surrounding AI financing continue to fester, "a giant dark cloud hanging over the market."
In its letter to investors, Elliott listed three specific concerns about the AI space:
Circular investments between AI model companies and AI infrastructure manufacturers, debt-fueled capital expenditure expansion, and a rising anti-AI social movement.
Elliott warned that once AI product pricing comes under challenge, or market expectations for AI buildout contract, the impact on the market "could be historic, at least as severe as any bear market in the past several decades."
This logical loop is now manifesting in the market: mega-cap tech stocks enjoyed substantial premiums on the AI narrative, and when the commercial realization of that narrative comes under question, the valuation framework faces restructuring pressure. Once leveraged funds heavily positioned in these stocks begin to retreat, margin calls are triggered, forcing investors to sell other assets to raise cash, forming a chain reaction.
Compounding Signals: The Emotional Shift from FOMO to FOGO
The underlying structure of market sentiment may be undergoing a qualitative shift.
Elliott believes the current bull market is supported by multiple factors, which is precisely what constitutes systemic risk—if any one or two pillars among expanding U.S. budget deficits, stubborn inflation, hidden private credit risks, and the AI bubble begin to waver, market sentiment could abruptly shift from "fear of missing out" (FOMO) to "fear of getting obliterated" (FOGO), triggering a self-reinforcing chain of collapse.
Elliott further characterized the increasingly prevalent zero-day options trading and meme stock bets in the current market as behavior "closer to gambling," and believes these speculative activities are distorting the market's normal pricing mechanisms.
Elliott managing partner Jesse Cohn recently wrote on X:
"The stock market feels different now, because it is different. Winners keep winning, losers get crushed, and market reactions during earnings season are increasingly difficult to predict, with ever-larger swings."
Institutions Turn Defensive, Waiting for the "Tide to Turn"
Faced with the above risk assessment, some leading institutions have begun actively reducing risk exposure and shifting into defensive mode.
Elliott has shifted its investment focus to capital preservation. Singer and co-CEO Jonathan Pollock wrote in the letter:
"In Elliott's fifty-year history, quiet periods have indeed existed, but these periods have historically been accompanied by market turbulence and subsequently followed by rare windows of opportunity. Our goal is to be fully prepared—protected on the downside while holding capital that can buy cheap assets at market lows—waiting for the tide to turn once again."
Dohmen and Dohmen likewise explicitly advised in their article: avoid buying the dip in AI and related stocks. They used a poker table adage as a metaphor—"If you can't spot the sucker at the table, then you are the sucker."
Historical Reference: Tops Never Announce Their Arrival
Both Dohmen and Elliott are pointing to a counterintuitive market principle: the real top of the market often forms when the public has yet to notice.
Dohmen noted in the article that the top of the AI and semiconductor sectors quietly took shape in June of this year, but did not arouse sufficient vigilance at the time. Investors who only added positions after the market had already reached highs now face substantial unrealized losses and the psychological battle of "refusing to cut losses"—this is the classic pathway by which trapped positions accumulate in a bear market, and the root cause of why every future rally will encounter heavy selling pressure.
Elliott compared the current situation to the "Roaring Twenties" before the Great Depression, when debt-driven risk appetite similarly overlapped with enthusiasm for new technology. History does not repeat itself exactly, but it often rhymes.





