US Stock Market Daily | Philadelphia Semiconductor Index Surges 3.6%, AI Enthusiasm Reignites US Stocks (October 28)


- Key Takeaways: Anthropic has submitted an S-1 to list on the Nasdaq at a valuation of $1.5-2 trillion, reigniting AI investment enthusiasm and driving a rally in chip stocks; the Fed's FOMC meeting is underway, with the market expecting rates to remain unchanged but December rate hike expectations rising; in the crypto market, spot Bitcoin ETFs have ended their net outflow streak, and BTC has held the $80,000 level.
- Key Elements:
- Anthropic reported H1 revenue of $16.3 billion (+1258% YoY), with quarterly operating profit turning positive for the first time, net revenue retention at approximately 900%, Goldman Sachs and Morgan Stanley leading the underwriting, targeting a listing in the week of November 16.
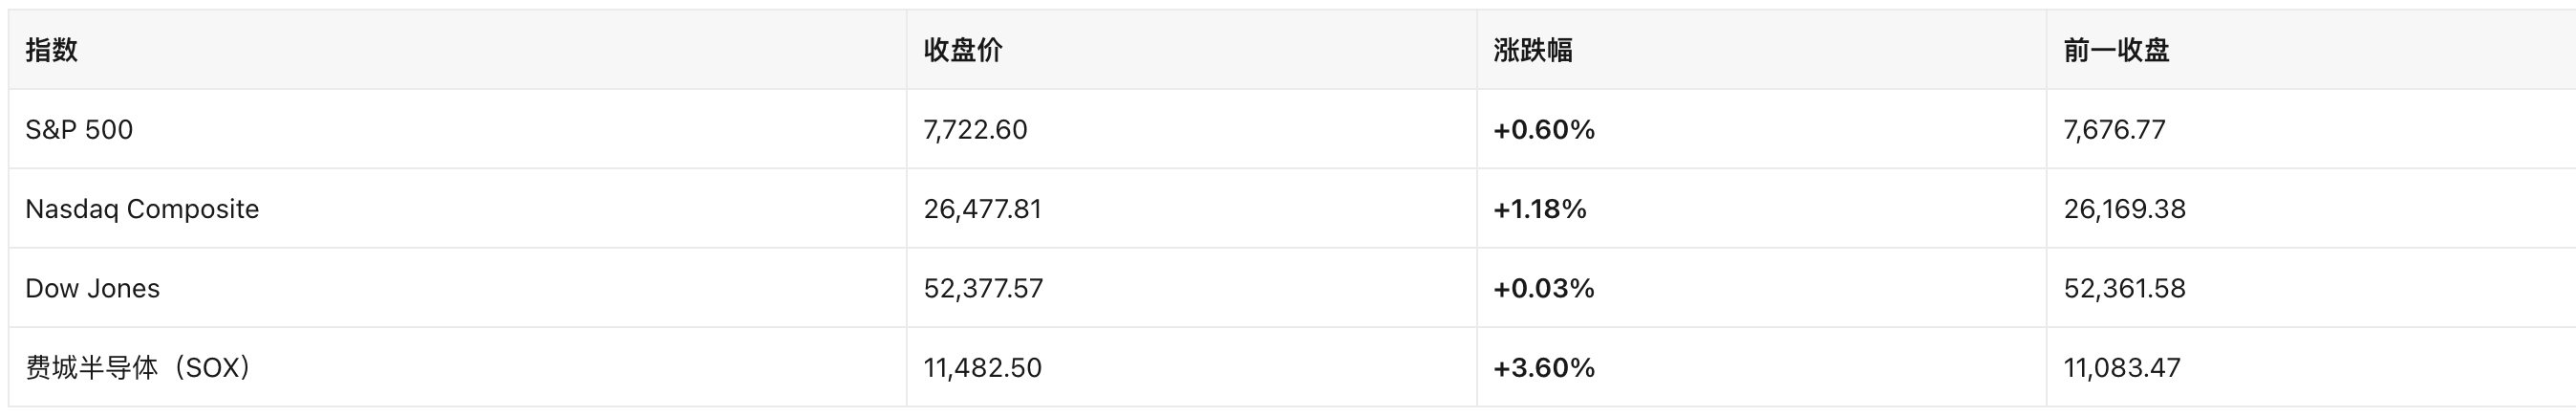
- The Philadelphia Semiconductor Index surged 3.6% to 11,482.50 points, marking its largest single-day gain in nearly a month, with leaders such as Nvidia and Broadcom rallying across the board, while the Nasdaq rose 1.18%.
- The Fed's current rate stands at 3.75%-4.00%, with 94 economists expecting no change in October, but September CPI rising to 3.7% and elevated energy prices make a 25bp rate hike in December a high-probability event.
- WTI crude fell below $100/barrel as Iran and Oman made progress in negotiations over a framework for navigation through the Strait of Hormuz; the IEA forecasts Q4 global oil demand to decline by 2.5 million barrels/day YoY.
- Spot Bitcoin ETFs saw net inflows of $110 million on Monday, ending the prior week's net outflows, with BlackRock's IBIT capturing all of the inflows and holding approximately 814,263 BTC; BTC is trading at $80,777.
- Strategy holds 848,517 BTC (average cost approximately $75,446), has paused coin purchases for consecutive periods, and instead repurchased $205 million in STRC preferred stock; new MSCI rules may exclude it from indices.
- Risk factors: an unexpectedly hawkish Fed, disappointing tech earnings (MSFT and GOOGL report after market close on October 28), collapse of Middle East negotiations, and BTC losing the $80,000 level.
1. Top Stories
- Anthropic officially files S-1 with the SEC, plans to list on Nasdaq under the ticker "ANT," with a valuation potentially reaching $1.5-2 trillion, poised to become one of the largest IPOs in history. The company reported first-half revenue of $16.3 billion (up 1258% year-over-year), with Goldman Sachs and Morgan Stanley leading the underwriting, targeting a listing in the week of November 16.
- Chip stocks surge for a second consecutive day, with the Philadelphia Semiconductor Index (SOX) soaring 3.6% to 11,482.50 points, marking the largest single-day gain in nearly a month. The Anthropic IPO news rekindled AI investment enthusiasm, with chip leaders including Nvidia and Broadcom rallying across the board, driving the Nasdaq up 1.18%.
- The Federal Reserve's October 27-28 FOMC meeting is underway, with the rate decision scheduled for release at 2:00 AM Beijing time on October 29. 94 economists expect rates to remain unchanged (currently 3.75%-4.00%), but September CPI rising to 3.7% and elevated energy prices have heightened expectations for a December rate hike. The October dot plot indicates another 25bp hike before year-end is the most likely scenario.
- WTI crude retreats from a six-month high, falling below $100/barrel. Iran and Oman are negotiating a framework agreement to restore navigation through the Strait of Hormuz, easing supply disruption concerns; the IEA previously projected Q4 global oil demand to decline 2.5 million barrels per day year-over-year.
- Spot Bitcoin ETFs saw net inflows of $110 million on Monday (October 26), ending the prior week's net outflow trend, with BlackRock's IBIT accounting for all net inflows. Bitcoin held the $80,000 level, trading at $80,777.
2. U.S. Stock Market and Macro
Three Major Indices Closing (US Eastern Time 2026-10-27 16:00)
Source: Yahoo Finance
Key drivers: Anthropic's S-1 filing rekindled AI investment enthusiasm, with chip stocks rallying across the board to lead the tech sector higher. The Nasdaq's +1.18% marked its best single-day performance in nearly a month. The Dow was dragged down by weight stocks such as UnitedHealth, gaining only 0.03%, with no clear sign of a style shift from tech to defensive. The S&P 500 closed higher for a second consecutive day.
Macro and the Federal Reserve
- Federal funds rate: Current target range 3.75%-4.00% (effective after the 25bp hike on September 17, 2026, the first hike since July 2023).
- FOMC meeting: The October 27-28 meeting is underway, with the rate decision to be announced at 14:00 US Eastern Time on October 28 (02:00 Beijing time on October 29). No Summary of Economic Projections (SEP) or dot plot will be released at this meeting.
- Market expectations: The vast majority of the 94 economists expect rates to remain unchanged in October; CME FedWatch previously showed about a 50% probability of an October hike, but weaker-than-expected September nonfarm payroll data shifted market expectations toward another 25bp hike in December.
- Inflation: September CPI rose 3.7% year-over-year (released October 14), a recent high, primarily driven by surging energy prices. August CPI was +3.4% year-over-year.
Bonds, Currencies, and Commodities (10-27)

Source: Yahoo Finance API
3. Hot Stocks and Sectors
1. AI/Semiconductor Sector — Anthropic IPO Ignites Enthusiasm
- Philadelphia Semiconductor Index (SOX) +3.60%, surging for a second consecutive day.
- Anthropic's S-1 filing disclosed first-half revenue of $16.3 billion (+1258% year-over-year), with quarterly operating profit turning positive for the first time, and net revenue retention of approximately 900%, validating strong enterprise AI willingness to pay.
- On the news front, tech stocks rallied collectively on October 26 following the IPO announcement: Nvidia (NVDA) +2.4%, Microsoft (MSFT) +1.5%, Micron (MU) +3%, Broadcom (AVGO) +2.3%. (Source: Yahoo Finance, Reuters)
- NVDA closed at 216.00 on 10-26, after-hours at 217.94 (+0.90%); MSFT closed at 532.60 on 10-26, after-hours at 531.33 (-0.24%).
- Watch: MSFT and GOOGL will report earnings after the close on October 28, the highlight of this week's tech earnings season.
2. Mega-Cap Tech — Earnings Week Kicks Off
- AAPL closed at 343.91 on 10-26, after-hours at 347.10 (+0.93%).
- GOOGL closed at 316.80 on 10-26, after-hours at 320.58 (+1.19%); reports earnings after the close on October 28.
- META closed at 630.56 on 10-26, after-hours at 620.19 (-1.64%).
- This week is a密集 period for mega-cap tech earnings: MSFT, GOOGL (after close 10-28), META, AMZN, and others will report in succession, with the market focused on AI capex guidance.
3. Crude Oil and Energy Sector — Falling Oil Prices Ease Inflation Concerns
- WTI fell below the $100 mark, with Brent retreating in tandem.
- Drivers: Progress in Iran-Oman consultations on a Strait of Hormuz navigation framework; the IEA monthly report projects Q4 global oil demand to decline 2.5 million barrels per day year-over-year.
- The energy sector is under pressure, but oil prices remain well above year-start levels (WTI was around $72 at the start of the year), and the pass-through to the energy component of CPI remains a focus for the Fed.
4. Crypto-Related U.S. Stocks
4.1 DAT (Digital Asset Treasury) Company Developments
Strategy (MSTR) — Pauses Bitcoin Purchases, Prioritizes Preferred Stock Buybacks
- Holdings: As of October 25, Strategy holds 848,517 BTC, with a cumulative purchase cost of approximately $64.02 billion and an average cost of approximately $75,446 per coin.
- This week's activity: During the week of October 19-25, Strategy neither bought nor sold any Bitcoin, nor did it issue shares through its ATM program. This marks another consecutive week of pausing Bitcoin purchases.
- Capital allocation shift: The company used USD cash reserves last week to repurchase 2,068,459 shares of STRC series perpetual preferred stock for approximately $205 million, with no repurchases of other security classes. The strategic focus has shifted from accumulating BTC to maintaining preferred stock prices and shareholder confidence.
- Prior purchase pace: The company had resumed small-scale purchases in mid-October — buying 250 BTC and repurchasing $192 million of STRC during the week of October 12; buying approximately $22 million of BTC and repurchasing $193 million of STRC during the week of October 19.
- Q3 earnings preview: Strategy expects Q3 digital asset fair value gains of approximately $20.9 billion (non-cash), primarily reflecting mark-to-market gains from rising BTC prices. The company will report Q3 earnings shortly.
- MSCI index risk: MSCI officially finalized new index rules on October 15, which could exclude DAT companies like Strategy whose core business is crypto assets from MSCI indices. Strategy Executive Chairman Michael Saylor and CEO Phong Le previously publicly criticized the decision as "discriminatory" policy.
- MSTR stock price: Daily close on 10-26 was 139.82 (down 4.24% from the 10-23 close of 146.01). After-hours at 141.40 (+1.13%). BTC's recovery above $80,000 provided support for after-hours pricing.
Crypto U.S. Stock Watchlist Changes: No new companies announced a transition to DAT or began purchasing BTC/ETH as treasury assets this week. Smarter Web Company (UK-listed) previously raised £10 million for a Bitcoin treasury strategy, worth monitoring for further developments. (Source: Crypto Times, October 27)
4.2 Broad Crypto U.S. Stocks
Mining Sector — BTC Recovery Drives Strong After-Hours Rebound
Source: Yahoo Finance API daily series
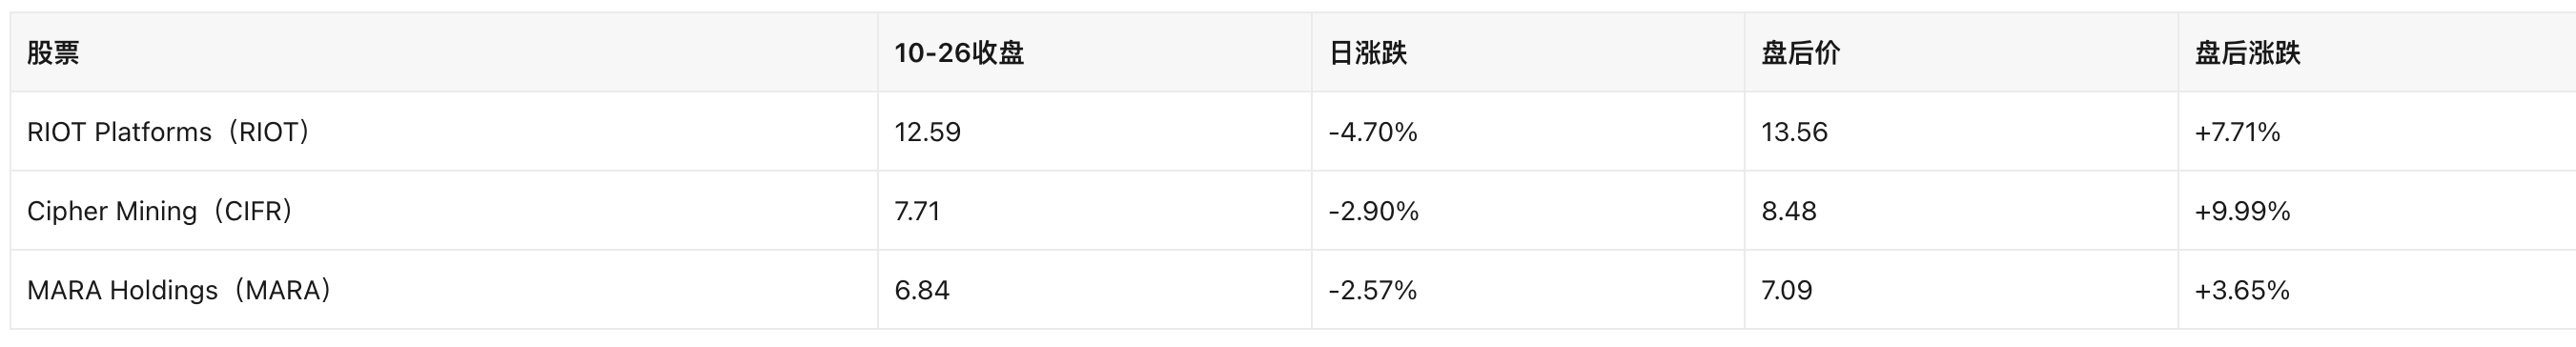
The mining sector pulled back with the broader market on 10-26, but rebounded strongly after-hours on 10-27 as BTC recovered to $80,777. RIOT and CIFR both posted after-hours gains approaching or exceeding 10%, demonstrating the high beta of mining stocks to BTC prices.
Exchanges and Platforms
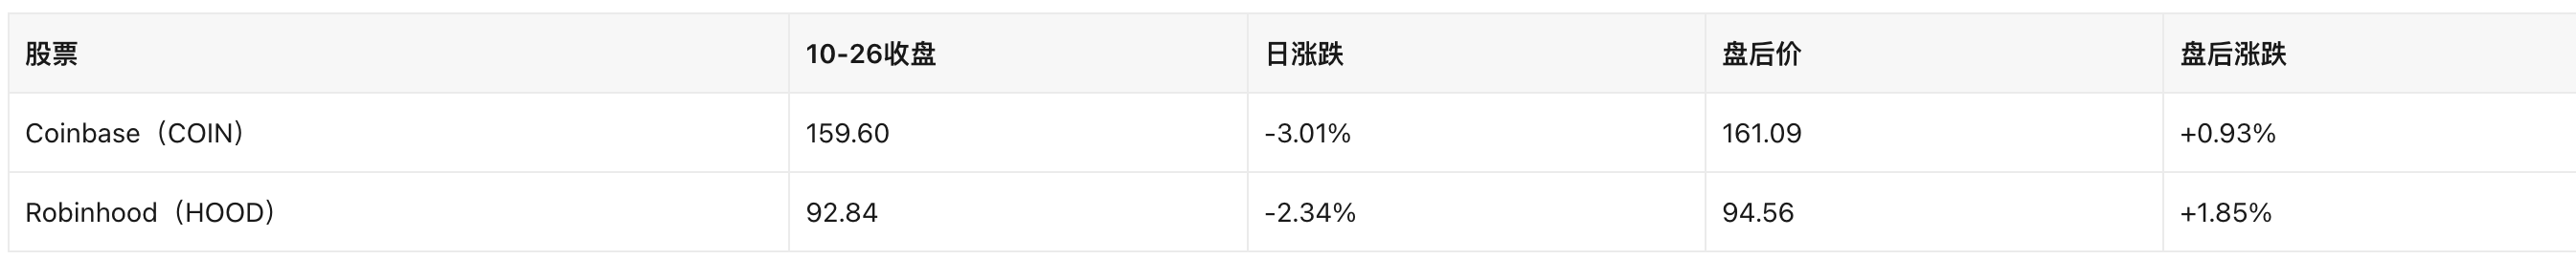
COIN and HOOD declined during regular trading on 10-26 but both recovered slightly after-hours. As the largest U.S. crypto exchange, Coinbase's trading volume is highly correlated with BTC prices.
Spot Bitcoin ETF Fund Flows
- October 26 (Monday): Total net inflows into U.S. spot Bitcoin ETFs were +$110 million, with BlackRock's IBIT alone recording net inflows of $110.3 million; no other funds saw net inflows that day.
- Past week review: After previously experiencing approximately $774 million in net outflows, the $110 million return on October 26 marked a marginal improvement in fund flows.
- IBIT holdings: BlackRock's IBIT currently holds approximately 814,263 BTC, with cumulative historical net inflows of $66.244 billion.
- Total scale: Total net asset value of U.S. spot Bitcoin ETFs is approximately $102.84 billion, with ETF net assets representing approximately 6.41% of BTC's total market cap and cumulative historical net inflows of $57.293 billion.
- ETH spot ETFs: Ethereum spot ETFs saw net inflows of +$16.1 million on October 26; Solana ETFs saw net outflows of -$8.2 million.
- Institutional moves: Cathie Wood's Ark Investment reduced its Bitcoin ETF holdings (specific size undisclosed), occurring during BTC's continued October pullback.
IBIT/FBTC Latest Quotes
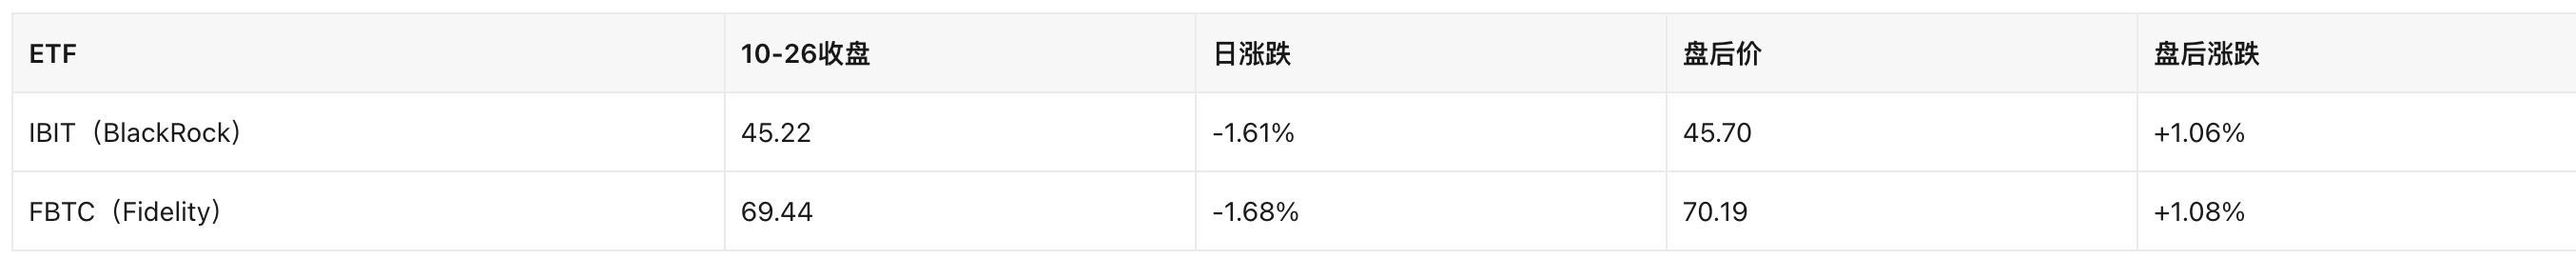
Source: Yahoo Finance API. The after-hours recovery in IBIT and FBTC reflects BTC price strength during Asian and early European trading hours.
4.3 Regulatory and Accounting Drivers
- MSCI index rule update (October 15): MSCI officially finalized new index inclusion rules that could exclude companies whose core business is crypto asset treasury (such as Strategy). The rules aim to address whether companies whose "primary business is holding crypto assets" are suitable for inclusion in traditional stock indices. Strategy executives previously criticized the decision as "discriminatory" against the digital asset treasury model.
- Impact assessment: If Strategy is excluded from MSCI indices, passive funds (ETFs, etc.) would be forced to sell MSTR, potentially creating short-term selling pressure on the stock. However, actively managed funds would be unaffected. MSCI has not yet executed the exclusion, and the specific implementation timeline remains to be confirmed.
- Bitcoin Treasury Permanence Act: The U.S. Senate Banking Committee previously advanced the "2026 American Reserve Modernization Act" by a 28:21 vote, providing a legal framework for corporate Bitcoin holdings. The final vote timing and content revisions of the bill are still in progress.
4.4 Crypto U.S. Stock Correlation Signals
- BTC price recovery → mining sector after-hours rebound: BTC recovered from an intraday low of approximately $79,830 to $80,777, with RIOT, CIFR, and MARA all posting after-hours gains exceeding 3%, demonstrating the high beta characteristics of mining stocks to BTC prices.
- Anthropic IPO → AI concept correlation: The AI enthusiasm revival not only boosted chip stocks but also benefited names related to AI/blockchain crossover concepts. CoreWeave (AI compute company, already public) rose 1.8% on October 26.
- Pre-Fed decision wait-and-see sentiment: Crypto U.S. stocks entered wait-and-see mode alongside the broader market, with broad pullbacks during regular trading on 10-26, followed by after-hours rebounds on BTC recovery and AI news tailwinds.
5. Geopolitical Impact
1. Middle East Situation: Iran Nuclear Issue and the Strait of Hormuz
- Latest developments: Iran and Oman are consulting on a "temporary framework" to restore shipping through the Strait of Hormuz. Pakistan's Army Chief of Staff concluded a visit to Iran, with Iranian media citing "valuable results." Market expectations for a diplomatic resolution to the Iran nuclear issue are rising. (Source: Reuters, Oman News Agency, October 26-27)
- Transmission to U.S. stocks: Improved expectations for Strait of Hormuz navigation → reduced risk of crude supply disruption → WTI falls below $100 → easing inflation expectations → favorable for a Fed rate pause → positive for equity risk appetite. The October 27 oil price decline and stock market rally formed a positive feedback loop.
- Transmission to crypto markets: Falling oil prices → cooling inflation expectations → marginally reduced safe-haven demand for BTC as "digital gold," but improved risk appetite is favorable for risk assets including BTC. Current BTC price action is more driven by ETF fund flows and Fed policy expectations.
- Uncertainty: Iranian officials deny having approved any preliminary memorandum of understanding draft, and differences remain on key issues. If negotiations break down, oil prices could quickly rebound above $110, re-igniting inflation expectations.
2. U.S.-China Trade and Tariffs
- Latest developments: U.S. companies' new investment plans in China have fallen to historic lows (Source: AP News). U.S.-China trade friction continues, but no new major tariff escalation measures have been announced.
- Impact on U.S. stocks: Trade uncertainty continues to weigh on multinational corporate earnings expectations, particularly in the tech and manufacturing sectors. However, the market has largely priced in current tariff levels, and the marginal impact is diminishing.
3. Energy and Supply Chains
- The IEA October monthly report projects 2026 Q4 global oil demand to decline 2.5 million barrels per day year-over-year, with a full-year average decline of 2.6 million barrels per day, the first annual demand decline since 2009. Diesel demand is expected to fall 25% due to product supply constraints caused by the Iran conflict and economic deterioration. (Source: IEA)
- High oil prices are constraining the pace of rate cuts by global central banks — "High Oil Prices Disrupt the Pace of Interest Rate Cuts by Global Central Banks" (SunSirs, October 27).
6. Today's Focus (Next 24 Hours)
High-Priority Events
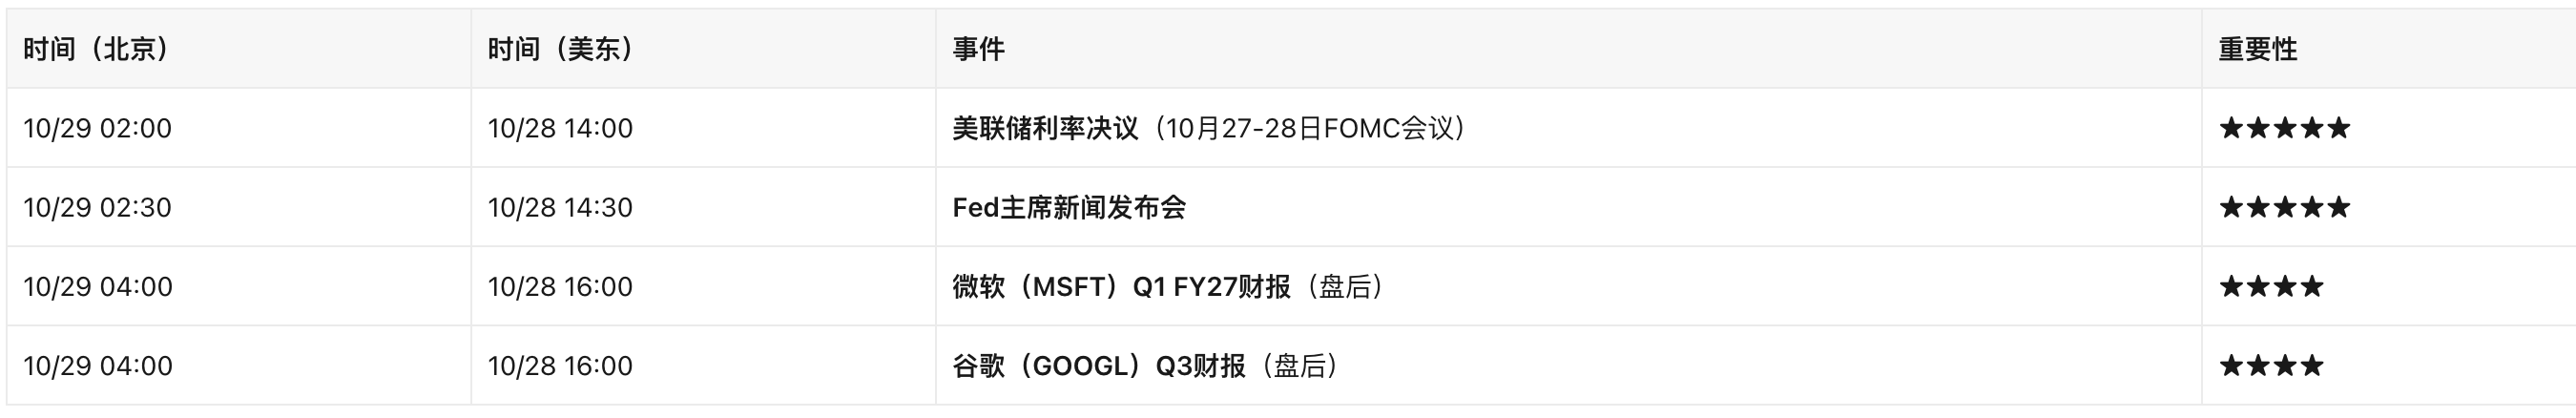
Other Items to Watch
- Economic data (10/28): U.S. October consumer confidence index (expected 16.8K vs prior 18.5K); U.S. September retail sales month-over-month (expected +0.5% vs prior +0.3%); U.S. September housing starts. (Source: Nasdaq Economic Calendar)
- investUS stocksWelcome to Join Odaily Official CommunityRecommended Articles