






AI Bubble Under Pressure: Is This the End of the Selloff, or the Next Buying Opportunity?


- Core View: Tech stocks are experiencing extreme selling pressure, with tightening AI financing conditions and credit risk contagion intertwined, putting the AI boom under severe funding strain. The market is at a critical window where positioning is being cleared out but conditions for bottom-fishing are not yet ripe.
- Key Elements:
- Goldman Sachs data shows approximately $20 billion in net global tech stock selling over the past two weeks, with selling intensity reaching an extreme -3.3 standard deviations.
- AI infrastructure debt financing has exceeded $500 billion year-to-date, with hyperscaler financing costs rising by approximately 120 basis points.
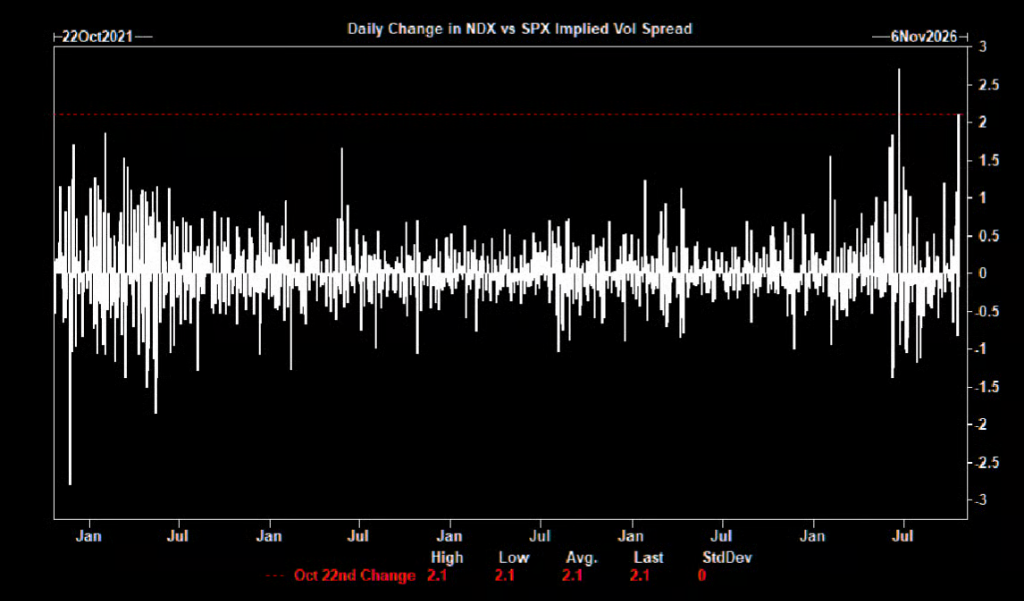
- The volatility spread between NDX and SPX has widened to the 98th percentile of the five-year range, indicating a highly concentrated fear premium in the tech sector.
- The financing linkage between Nvidia and GPU customers is viewed as a credit risk transmission chain, with pressure on operators like CoreWeave potentially feeding back to upstream suppliers.
- Tech exports account for nearly 20% of GDP in South Korea; a contraction in AI capex will asymmetrically impact Asian export economies.
- JPMorgan believes a buying window may emerge in early November, but requires conditions such as sufficiently cleared positioning and cloud providers confirming capex direction.
Original Author: Zhang Yaqi
Original Source: Wallstreetcn
The technology sector is under multiple pressures: hedge funds are aggressively cutting exposure, volatility warning signals are flashing, and at the same time, AI financing costs are climbing and credit risks are spreading, putting this AI boom under increasingly severe funding scrutiny.
Over the past two weeks, according to Goldman Sachs data, global tech stocks saw roughly $20 billion in net selling, with the intensity of the selloff reaching an extreme level of -3.3 standard deviations. The Nasdaq 100 Index (NDX) remains trapped in its range since May, with the 29,000-point futures threshold and the 200-day moving average around 28,500 points below it forming the most critical technical support zone at present.

At JPMorgan, analyst Privorotsky noted that although AI demand remains strong, the financing environment is tightening—AI infrastructure debt financing has exceeded $500 billion year-to-date, and the financing costs for hyperscale cloud service providers have risen by about 120 basis points. The financing relationship between Nvidia and its GPU customers is being viewed as a potential credit risk transmission chain; once GPU operators face tighter funding, the pressure could feed back to upstream suppliers.
Position Washout: Strikingly Similar to July
The scale and intensity of this round of tech stock selling has reminded the market of the pullback in July this year.
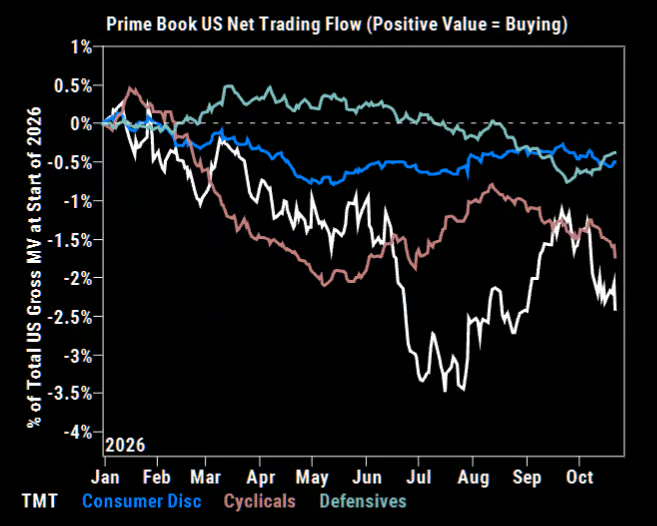
Goldman Sachs data shows that over the past two weeks, the TMT sector saw cumulative selling of about $20 billion, approaching the $23 billion during the July selloff. The most heavily hit trading instruments have shown almost identical price trajectories. The difference is that the S&P 500 Index fell only about 2.4% this round, less than the 3.4% decline in July, with volatility at the index level relatively contained.
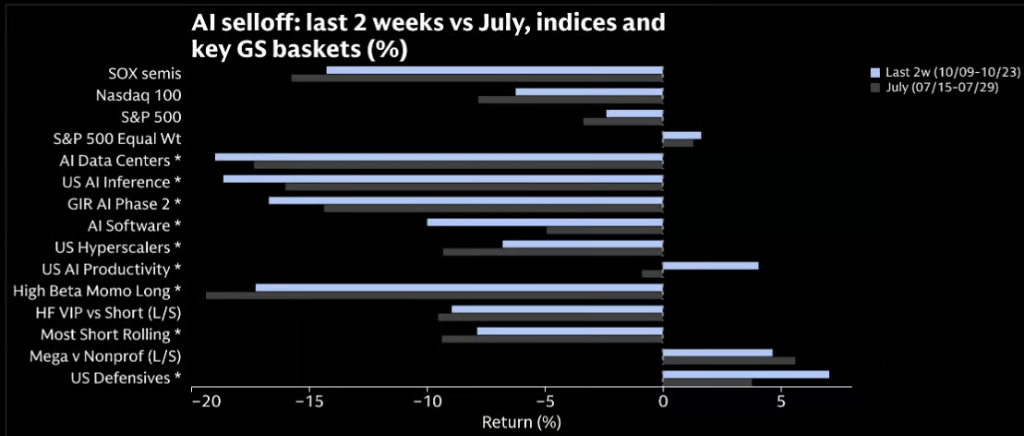
Meanwhile, Goldman Sachs' risk appetite indicator recorded one of the largest single drops on record, falling to its lowest level since April 2025. Net fundamental exposure in the TMT sector fell to a year-to-date low, although gross exposure remains at the 63rd percentile—meaning that while net positioning has been compressed, total leverage remains the current potential pain point.
Tech Panic Premium: As High as the 98th Percentile
Panic sentiment is not evenly distributed across the market but is highly concentrated in the technology sector.
Goldman Sachs analysis shows that the volatility spread between NDX and SPX has rapidly expanded to the 98th percentile of the five-year range, with last Thursday's single-day expansion marking the second-largest in five years. Volatility pricing specific to the tech sector is at abnormally expensive levels relative to overall market volatility, thereby creating potential relative-value trading opportunities. Correlation among AI-related stocks has strengthened significantly, but volatility at the index level remains relatively restrained overall.
AI Financing Test: Hyperscalers Become the Key Variable
This week, earnings from Google, Microsoft, and Amazon are being disclosed in quick succession, and the market's focus has moved beyond capex guidance itself.
According to JPMorgan, AI infrastructure debt absorption has exceeded $500 billion year-to-date, with hyperscale cloud service providers' financing costs up about 120 basis points. Against this backdrop, the question the market truly cares about is: whether backlog orders can be effectively converted into revenue, and how the next round of investment expansion will be financed.
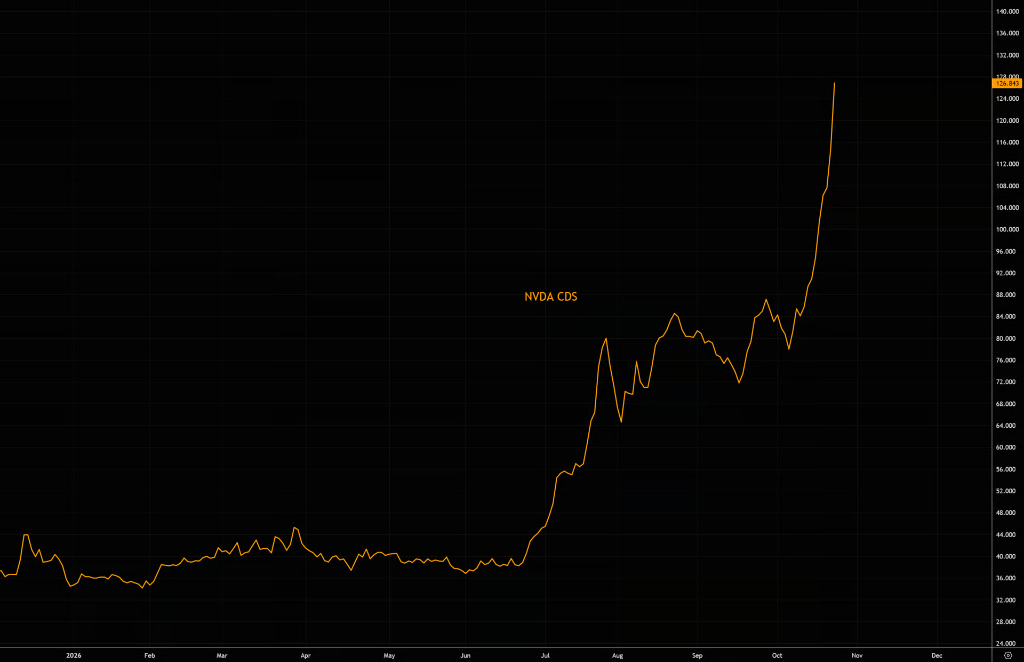
Notably, AI-related credit default swap (CDS) spreads have widened significantly recently, but JPMorgan believes this largely does not reflect deteriorating fundamentals, but rather banks actively buying protection to hedge their own expanding data center exposure. The widening spread between CDS and cash bonds may be creating new relative-value opportunities.
Credit Transmission Risk in the Nvidia Ecosystem
The financing relationship between Nvidia and its GPU customers is being identified by JPMorgan as a potential transmission path for AI credit stress.
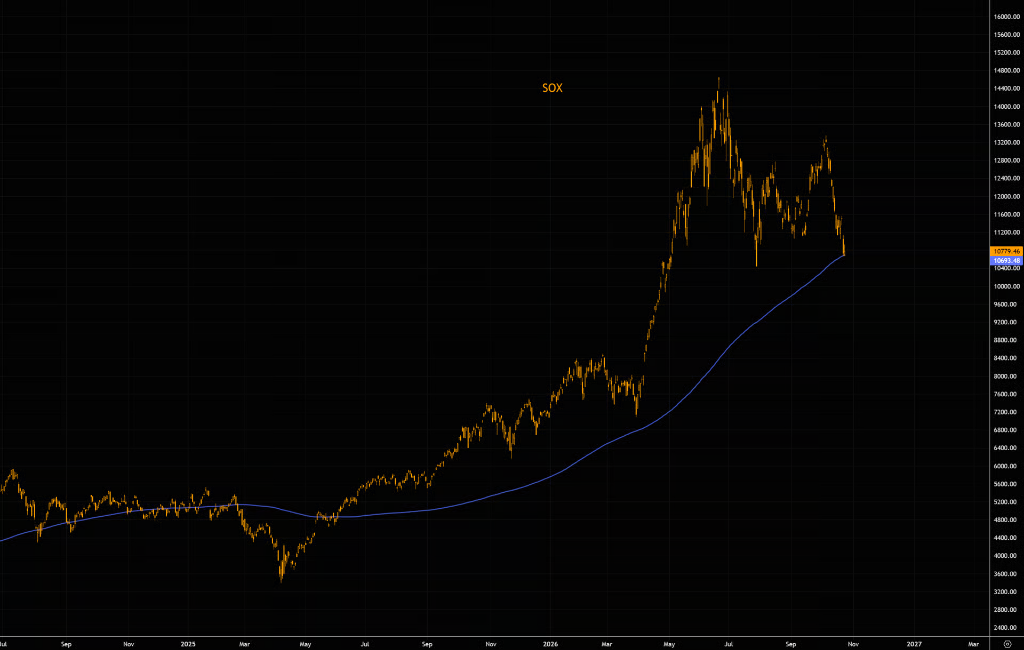
GPU operators represented by CoreWeave rely on customer financing and credit support to sustain AI infrastructure expansion. While this model supports growth, it also creates highly correlated downside risk: once GPU operators face a financing squeeze, pressure will transmit up the supply chain and ultimately feed back to upstream suppliers such as Nvidia. The Philadelphia Semiconductor Index (SOX) is currently testing 200-day moving average support, adding an important technical reference point to this risk path.
US Investment, Asia Benefits—and Is Hit First
While the AI capex boom drives domestic US demand, a large amount of capital is flowing overseas, creating asymmetric spillover effects.
According to TS Lombard data, tech exports as a share of GDP are close to 20% for South Korea. This means that if AI capex contracts sharply, Asian export economies will bear the brunt and suffer disproportionate impact, while the actual boost to the US domestic economy may be far smaller than the headline investment scale suggests.
The AI Collapse Paradox: Rate-Sensitive Sectors May Benefit Unexpectedly
TS Lombard economist Dario Perkins has proposed a counterintuitive logic: the end of the AI investment boom is not necessarily an all-out economic disaster.
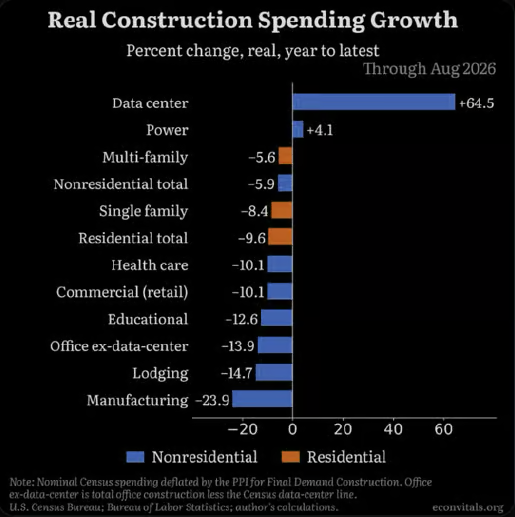
He argues that the current rapid expansion of AI capex is fueling inflation and keeping interest rates at higher levels, continuously squeezing rate-sensitive sectors such as real estate. If AI capex falls sharply, the Fed will gain room to cut rates more aggressively, thereby reactivating demand in non-tech areas and providing a buffer against an overall economic downturn. In other words, the beneficiaries after the end of the next AI boom may precisely be the sectors that were marginalized during this wave.
Potential Buying Window: Conditions Not Yet Fully Ripe
JPMorgan maintains a constructive view on tech sector fundamentals, but also flags risks including insufficient sustainability of semiconductor pricing and financing pressure on emerging cloud providers (neoclouds), with the software sector showing relatively stronger resilience.
The bank believes a potential buying window may emerge in early November, but the conditions have not yet been fully met: positioning must be further flushed out, hyperscalers must confirm their capex direction, semiconductor earnings need to withstand the test, and credit spreads also need to return to tightening. If any one of these conditions is missing, the sustainability of a rebound would be in doubt. For investors, the current market is neither a clear-cut liquidation signal nor an unconditional bottom-fishing opportunity—the answer may lie in the earnings reports of several tech giants this week.





