






Galaxy Letter to Clients: Now Is the Best Time to Buy Bitcoin


- Key Takeaways: Galaxy Research believes the Bitcoin bear market ended in June of this year, and the market is currently in an accumulation phase. Technicals, positioning structure, and fundamentals all support buying and holding, and Bitcoin has reason to return to $125,000.
- Key Points:
- The June low held the 200-week moving average, with the worst weekly close only 4.7% below it; in September, Bitcoin reclaimed the 50-week moving average and held it for five consecutive weeks. Historically, similar rebounds have been followed by significant gains within a year.
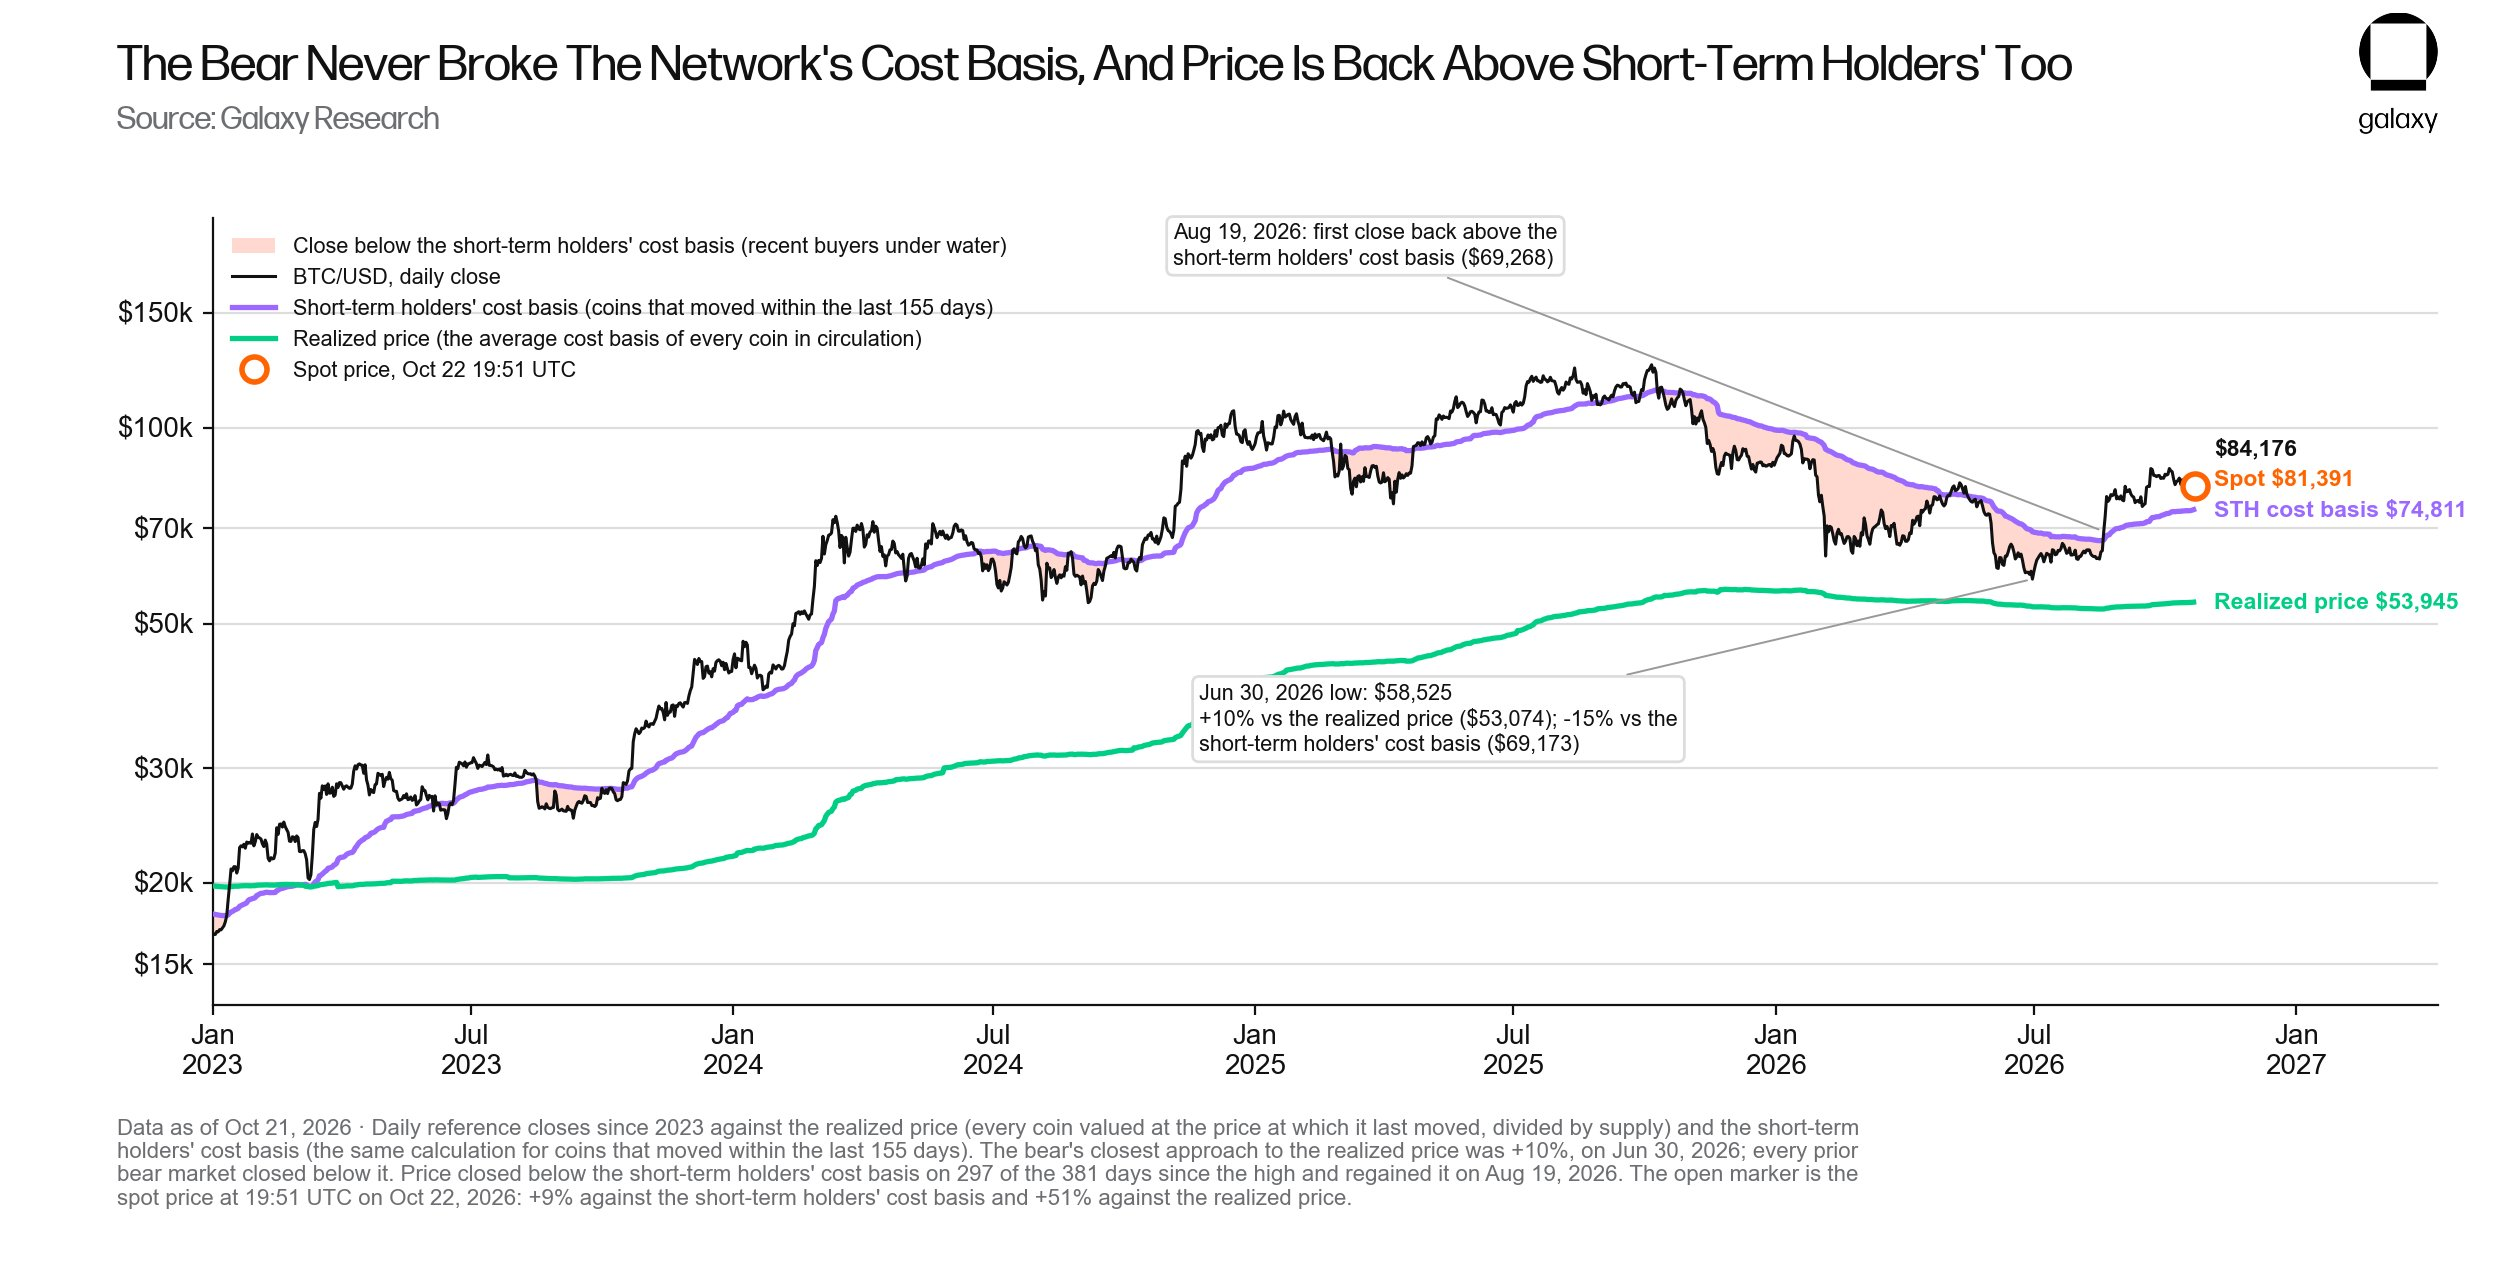
- This bear market saw a decline of only 53%, the shallowest on record, and for the first time it never broke below the network cost basis throughout, with MVRV bottoming at 1.10.
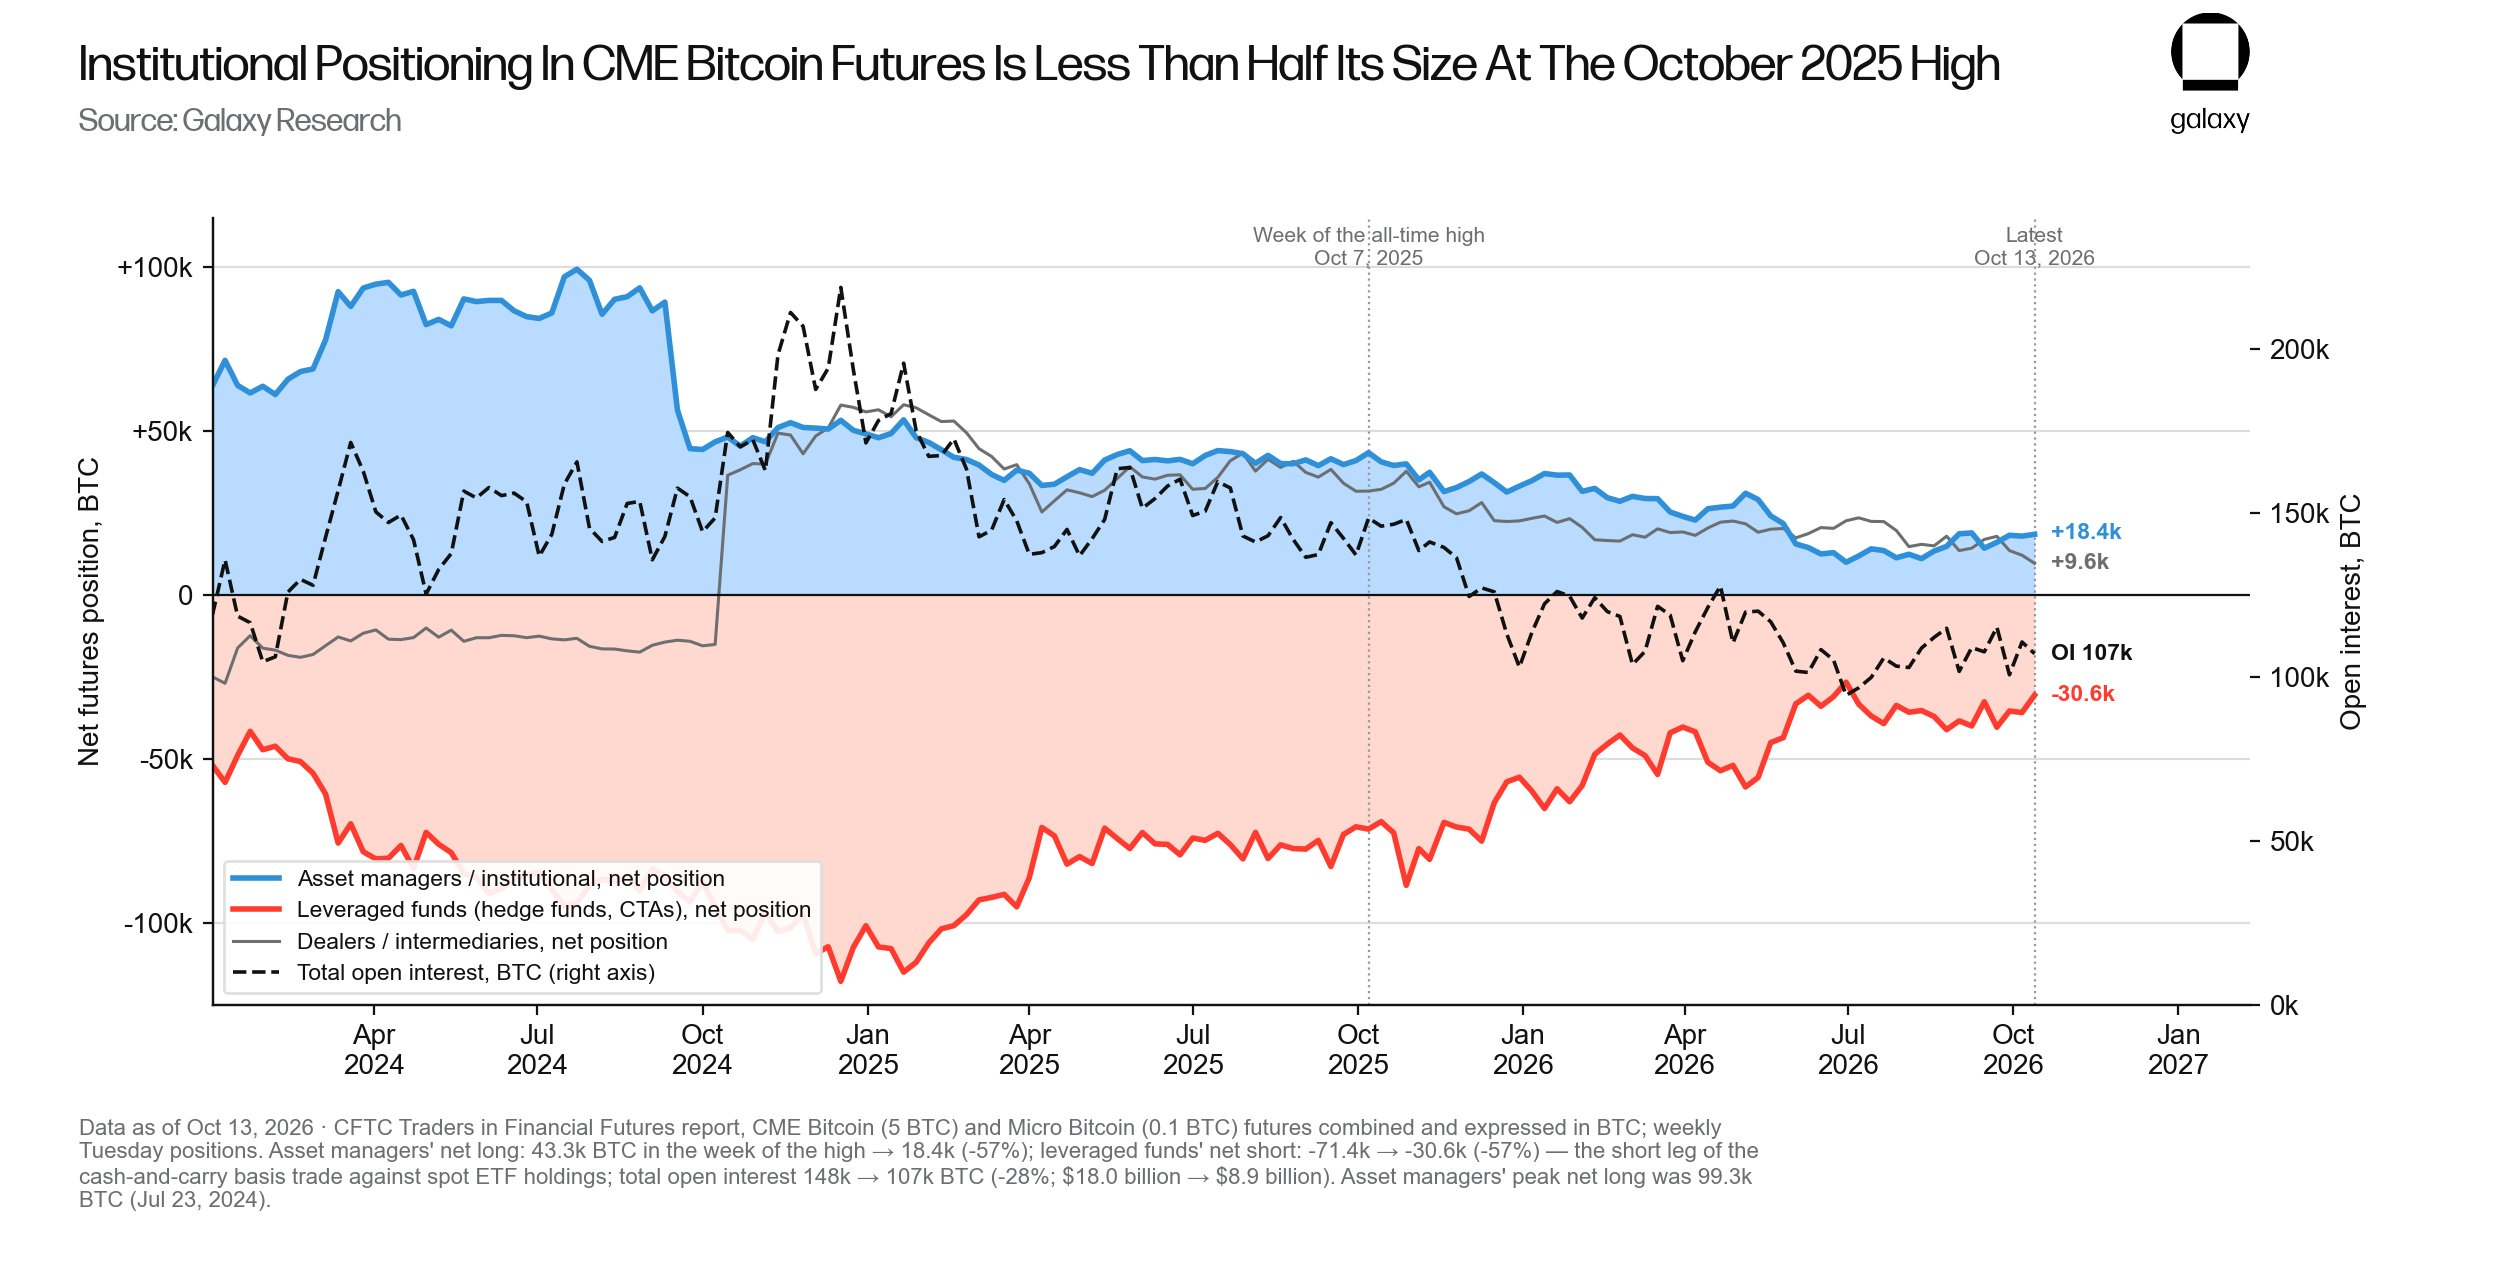
- Short-term selling pressure is fading: CME asset manager net longs fell 57%, leveraged fund net shorts fell 59%, and basis trade yields dropped from 7.9% to 4.8%, with arbitrage capital largely exiting.
- Spot ETF holdings fell only 11% (while price dropped 53%), with reductions concentrated among nine multi-strategy and macro funds, while wealth management platforms and sovereign funds increased holdings to absorb the selling.
- U.S. debt stands at $40.44 trillion, the FY2026 deficit is $1.99 trillion, or 6.2% of GDP, and the 10-year Treasury yield has risen to 5.31%, reinforcing the Bitcoin thesis amid currency debasement pressure.
- Market sentiment has turned for the third time toward "wanting blockchain/stablecoins rather than Bitcoin." Historically, when such shifts occurred, Bitcoin was less than a year away from its cycle low.
- Quantum risk is now recognized and being addressed: BIP-360 has been merged into the protocol, and multiple institutions have committed funding to support the quantum-resistant migration.
Original article from Galaxy
Compiled by Odaily Golem (@web 3_golem)
Editor's note: Galaxy originally sent this research report to its clients on October 22.The report's core thesis is that it believes the bear market ended this June, and that Bitcoin is currently in an "accumulation phase," a phase that has appeared before every previous rally.
From a technical perspective, the 200-week moving average has provided effective support, and the 50-week moving average has now been successfully reclaimed for five consecutive weeks; from a positioning perspective, short-term selling pressure has largely dissipated, with basis traders and macro speculators having cut their ETF and futures positions by more than half; Bitcoin's fundamental logic is also becoming more solid, as the US faces a $2 trillion fiscal deficit and Treasury yields sit at 5%, increasing the likelihood of currency debasement.
In addition, the market narrative has shifted for the third time toward "blockchain over Bitcoin" (the previous two narrative shifts both occurred when the market was at a bottom). As a result, Galaxy believes now is a good time to buy and hold Bitcoin. The article also outlines the conditions that would be sufficient to trigger Galaxy to change its view.
The Simplest Indicator: When the Narrative Ignores Bitcoin — Buy
At the end of last month, I attended a blockchain conference in Korea. It was an excellent conference that fully demonstrated Korea's growing interest and enormous market potential in digital assets. Despite the enthusiasm on the ground, the core theme of the event was very clear: a "great convergence" is underway between digital assets and traditional capital markets. Dozens of panel discussions were held during the conference, covering tokenization, RWA, stablecoins, and upgrades to payment infrastructure. I participated in one discussion focused on Bitcoin and the crypto asset market.
This reminded me of the Consensus conference held in New York in 2018, when the venue was full of suit-wearing attendees from the Big Three consulting firms, eager to talk about enterprise blockchain, such as R3's Corda and IBM's Hyperledger. After Bitcoin's price surged wildly in 2017 and then fell sharply, the market's direction shifted dramatically: people stopped focusing on Bitcoin and cryptocurrencies and turned their attention to the more mature and safer concept of blockchain technology.
From 2015 to 2016 (another deep bear market trough), I worked at Fidelity and observed a similar sentiment. At the time, no one wanted to talk about Bitcoin, but bankers were flocking to blockchain. Back then, influenced by the Silk Road incident and the ICO boom, and because the underlying technology itself did have practical value, financial institutions shied away from concepts like bearer assets, censorship resistance, and permissionlessness, and instead turned to more "respectable" territory.
Of course, Bitcoin and cryptocurrencies did not die, but as is the case today, attention had shifted substantially away from the core spirit of decentralization and toward a less revolutionary concept: upgrading the technological architecture of the financial system.
Although Wall Street's efforts to embrace blockchain in 2016 and 2018-2019 did not achieve notable results, this time could well be different. Today, institutional acceptance of digital assets and blockchain technology is an indisputable fact, and it will likely lead to a more efficient financial system. Even so, we should not forget the idea of "non-sovereign, censorship-resistant hard money," because it will never disappear.
Technicals: Bitcoin Has Bottomed
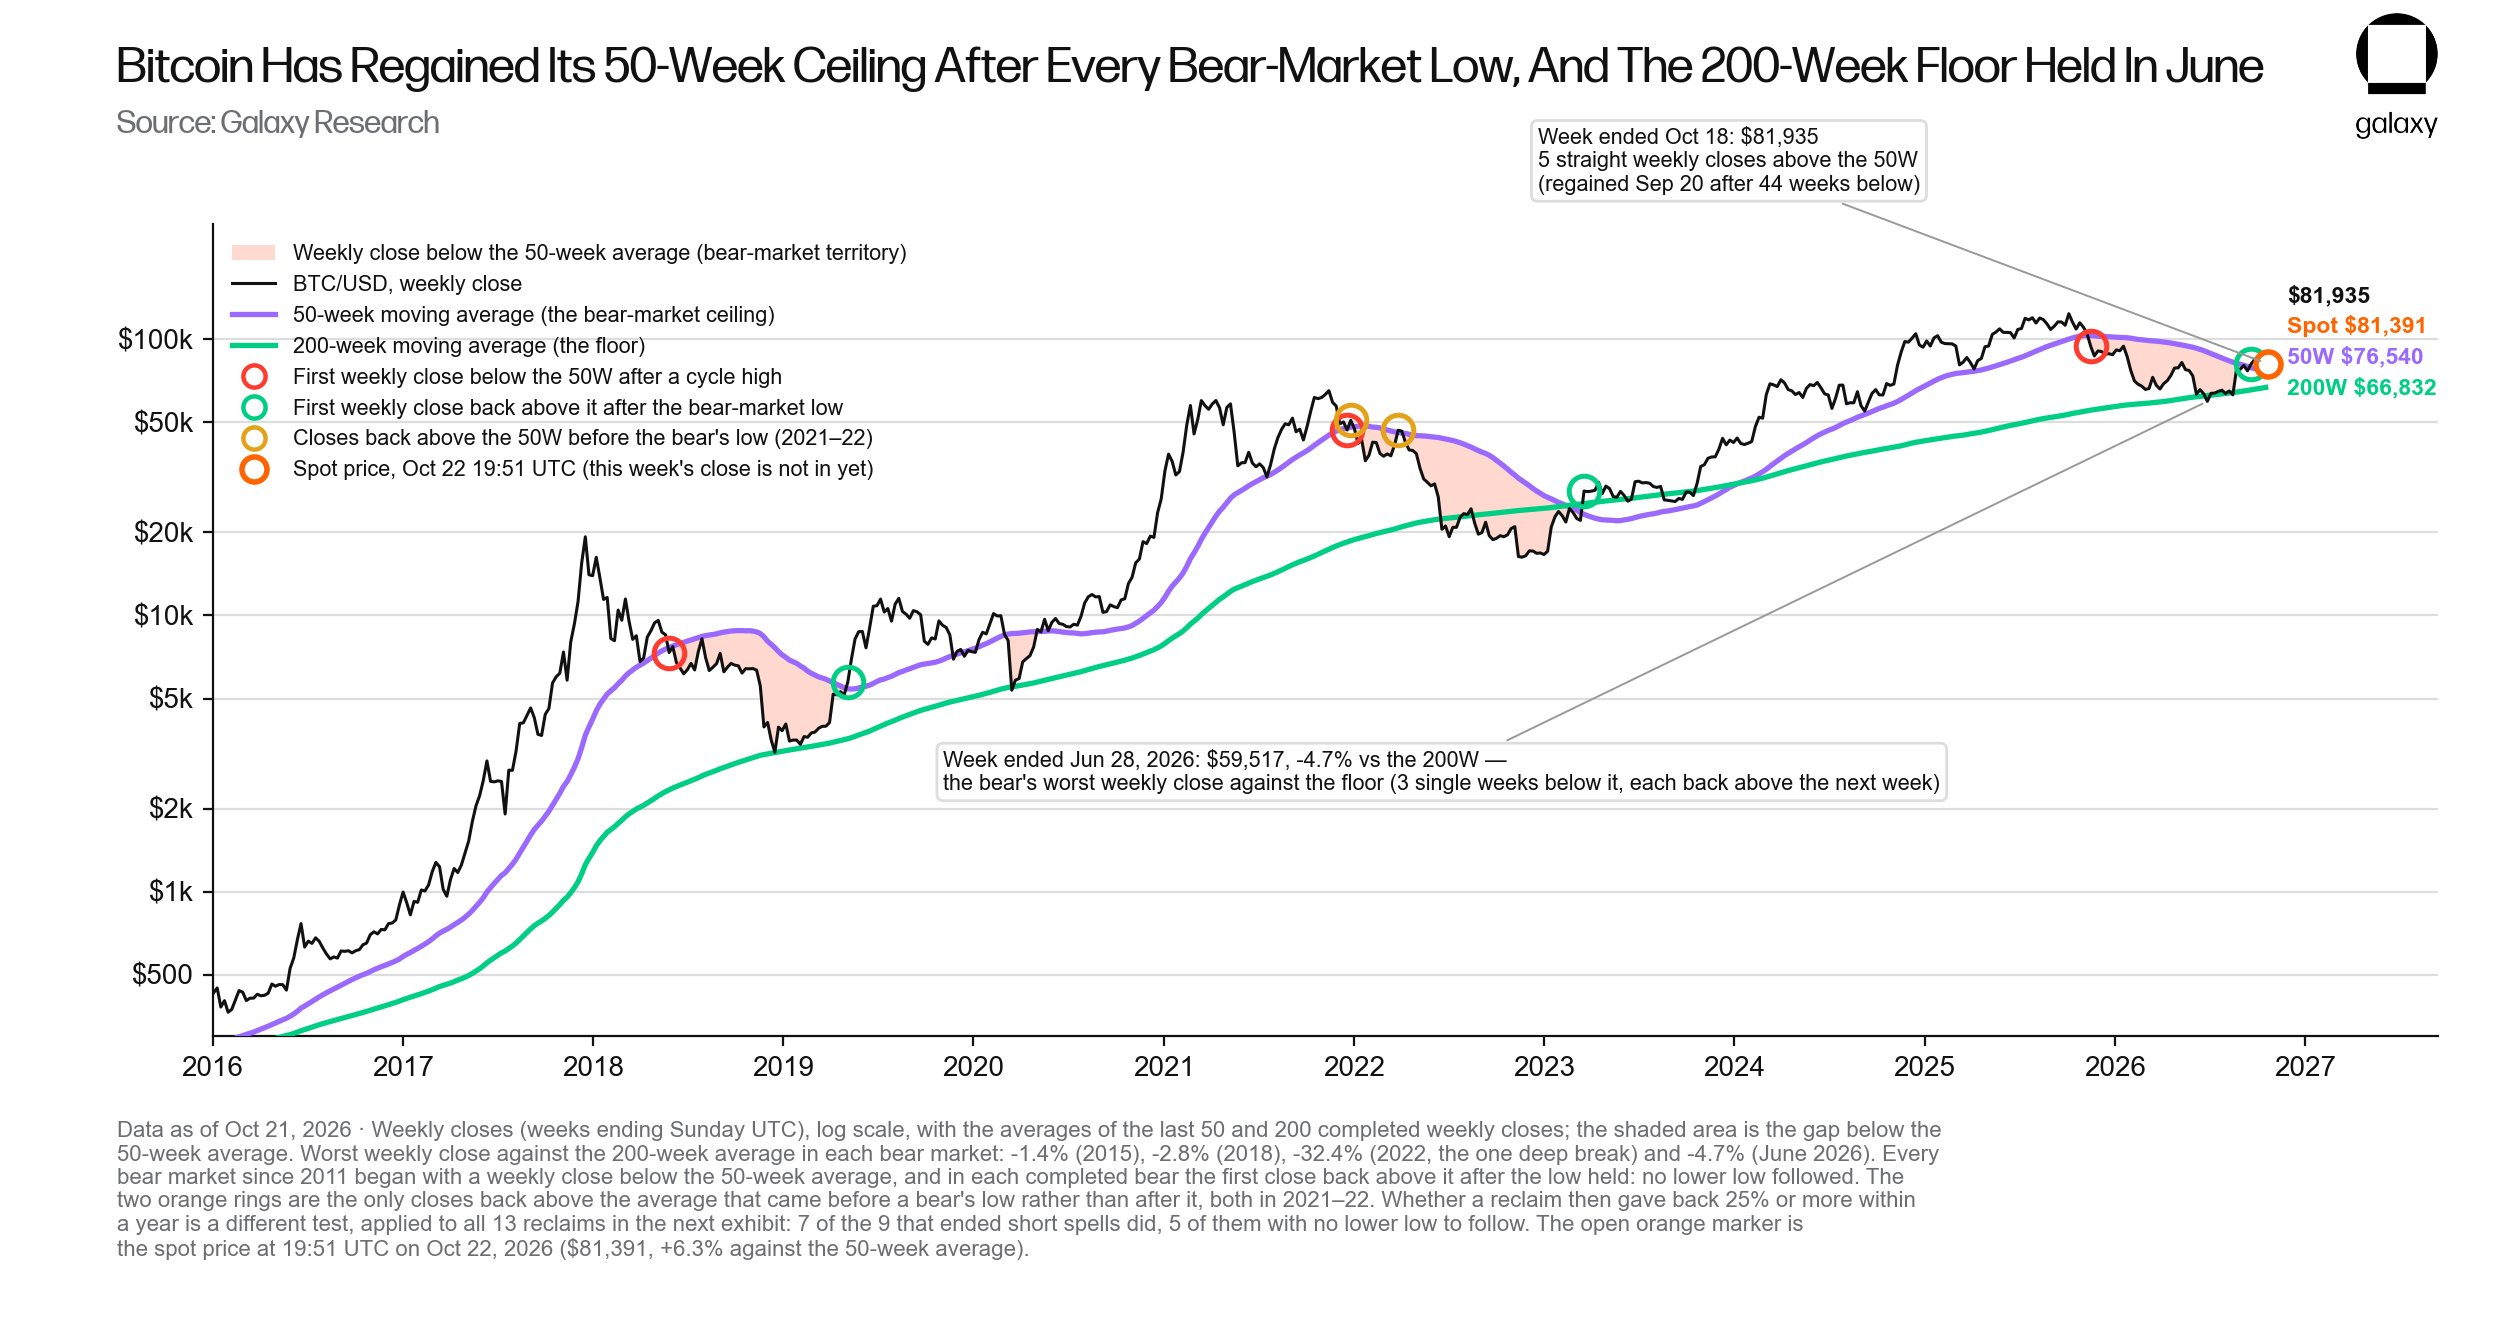
In Bitcoin bear markets, there is a reliable reference indicator: the 200-week moving average forms "bottom" support, while the 50-week moving average forms "top" resistance.
Bitcoin's price fell below the 50-week moving average in the week ending November 16, 2025, and remained below that average for 44 weeks thereafter. The June low touched the 200-week moving average support and successfully held it, with the worst weekly close only 4.7% below the 200-week moving average (for comparison, this figure was 1.4%, 2.8%, and 32% in 2015, 2018, and 2022, respectively).
In the week ending September 20, 2026, Bitcoin's price closed back above the 50-week moving average; as of the week ending October 18, it had closed above that average for five consecutive weeks. In every complete bear market since 2011, Bitcoin has tended to begin a sustained move back above the "top" resistance level after hitting a low (see chart below).
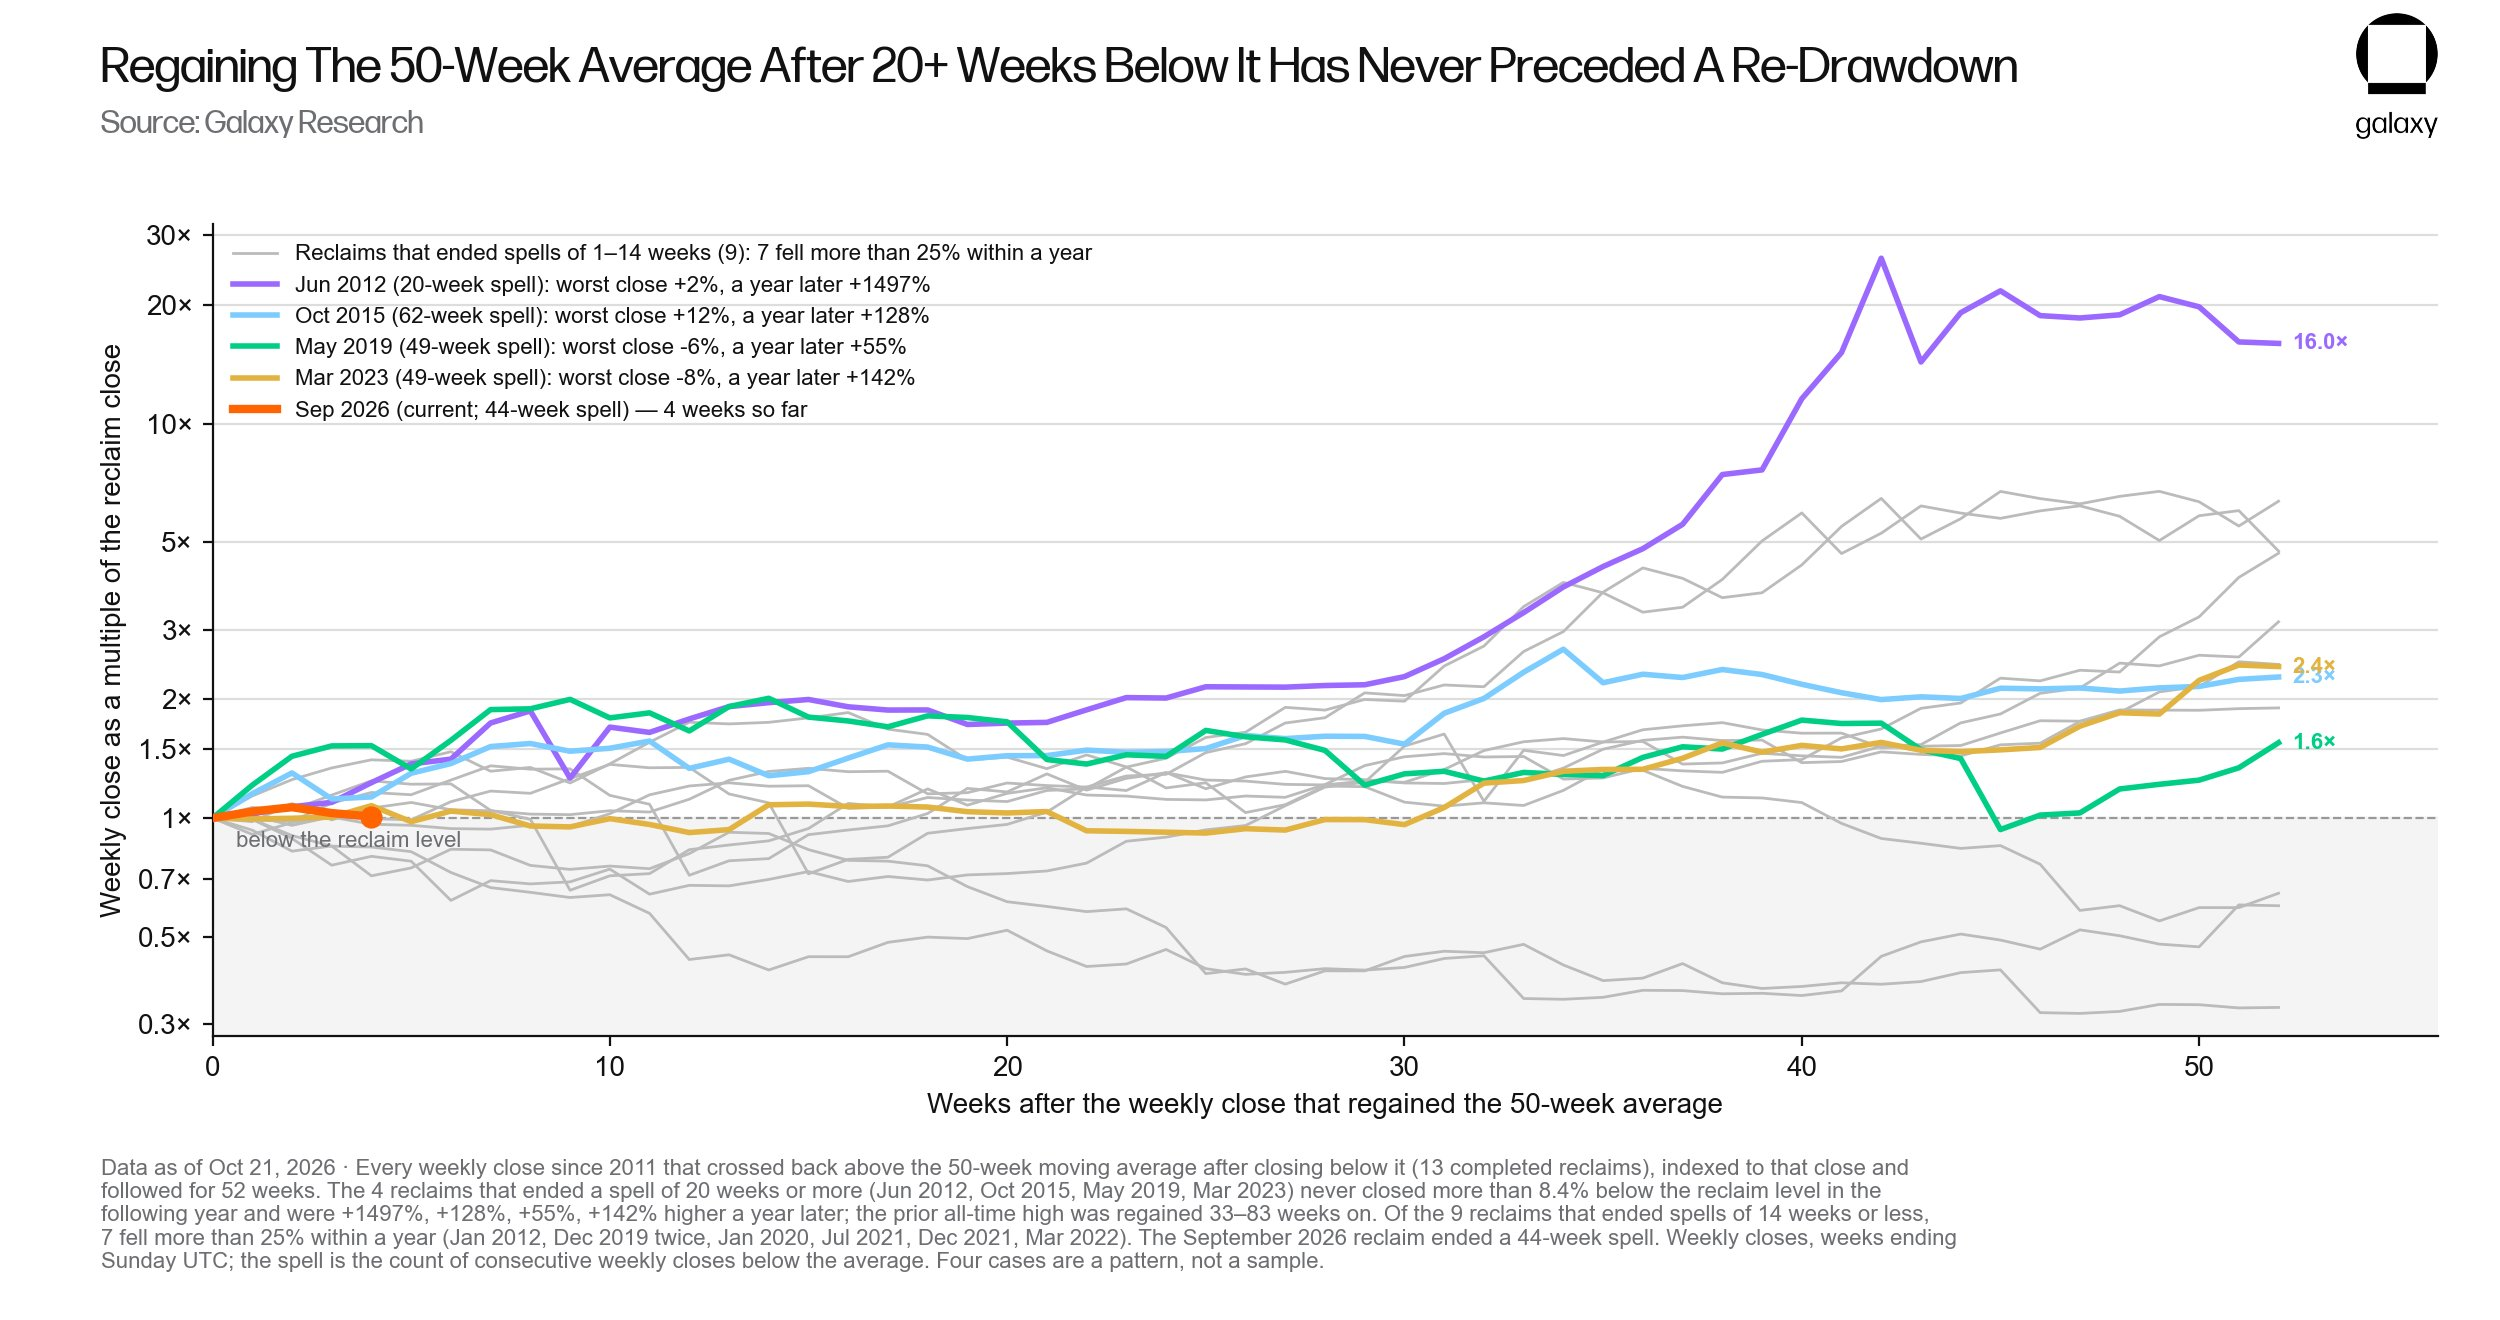
How often does Bitcoin experience a new leg down after a rebound? Since 2011, there have been 13 cases of rebounds (i.e., recovering from below the moving average to above it), and based on how long the price remained below the average, these cases showed different subsequent trajectories.
In 4 of these cases, the price remained below the moving average for more than 20 weeks. In the following year after these 4 rebounds, the price never fell more than 8.4% below the reclaim level; one year later, Bitcoin had risen 1497%, 128%, 55%, and 142%, respectively; within 33 to 83 weeks, the price retested its previous all-time high.
In the other 9 cases, Bitcoin's price remained below the moving average for no more than 14 weeks, and in 7 of those cases the decline exceeded 25% over the following year. This September's "reclaim" of the moving average ended a prior 44-week "low-range period" (see chart below). This constitutes a pattern.
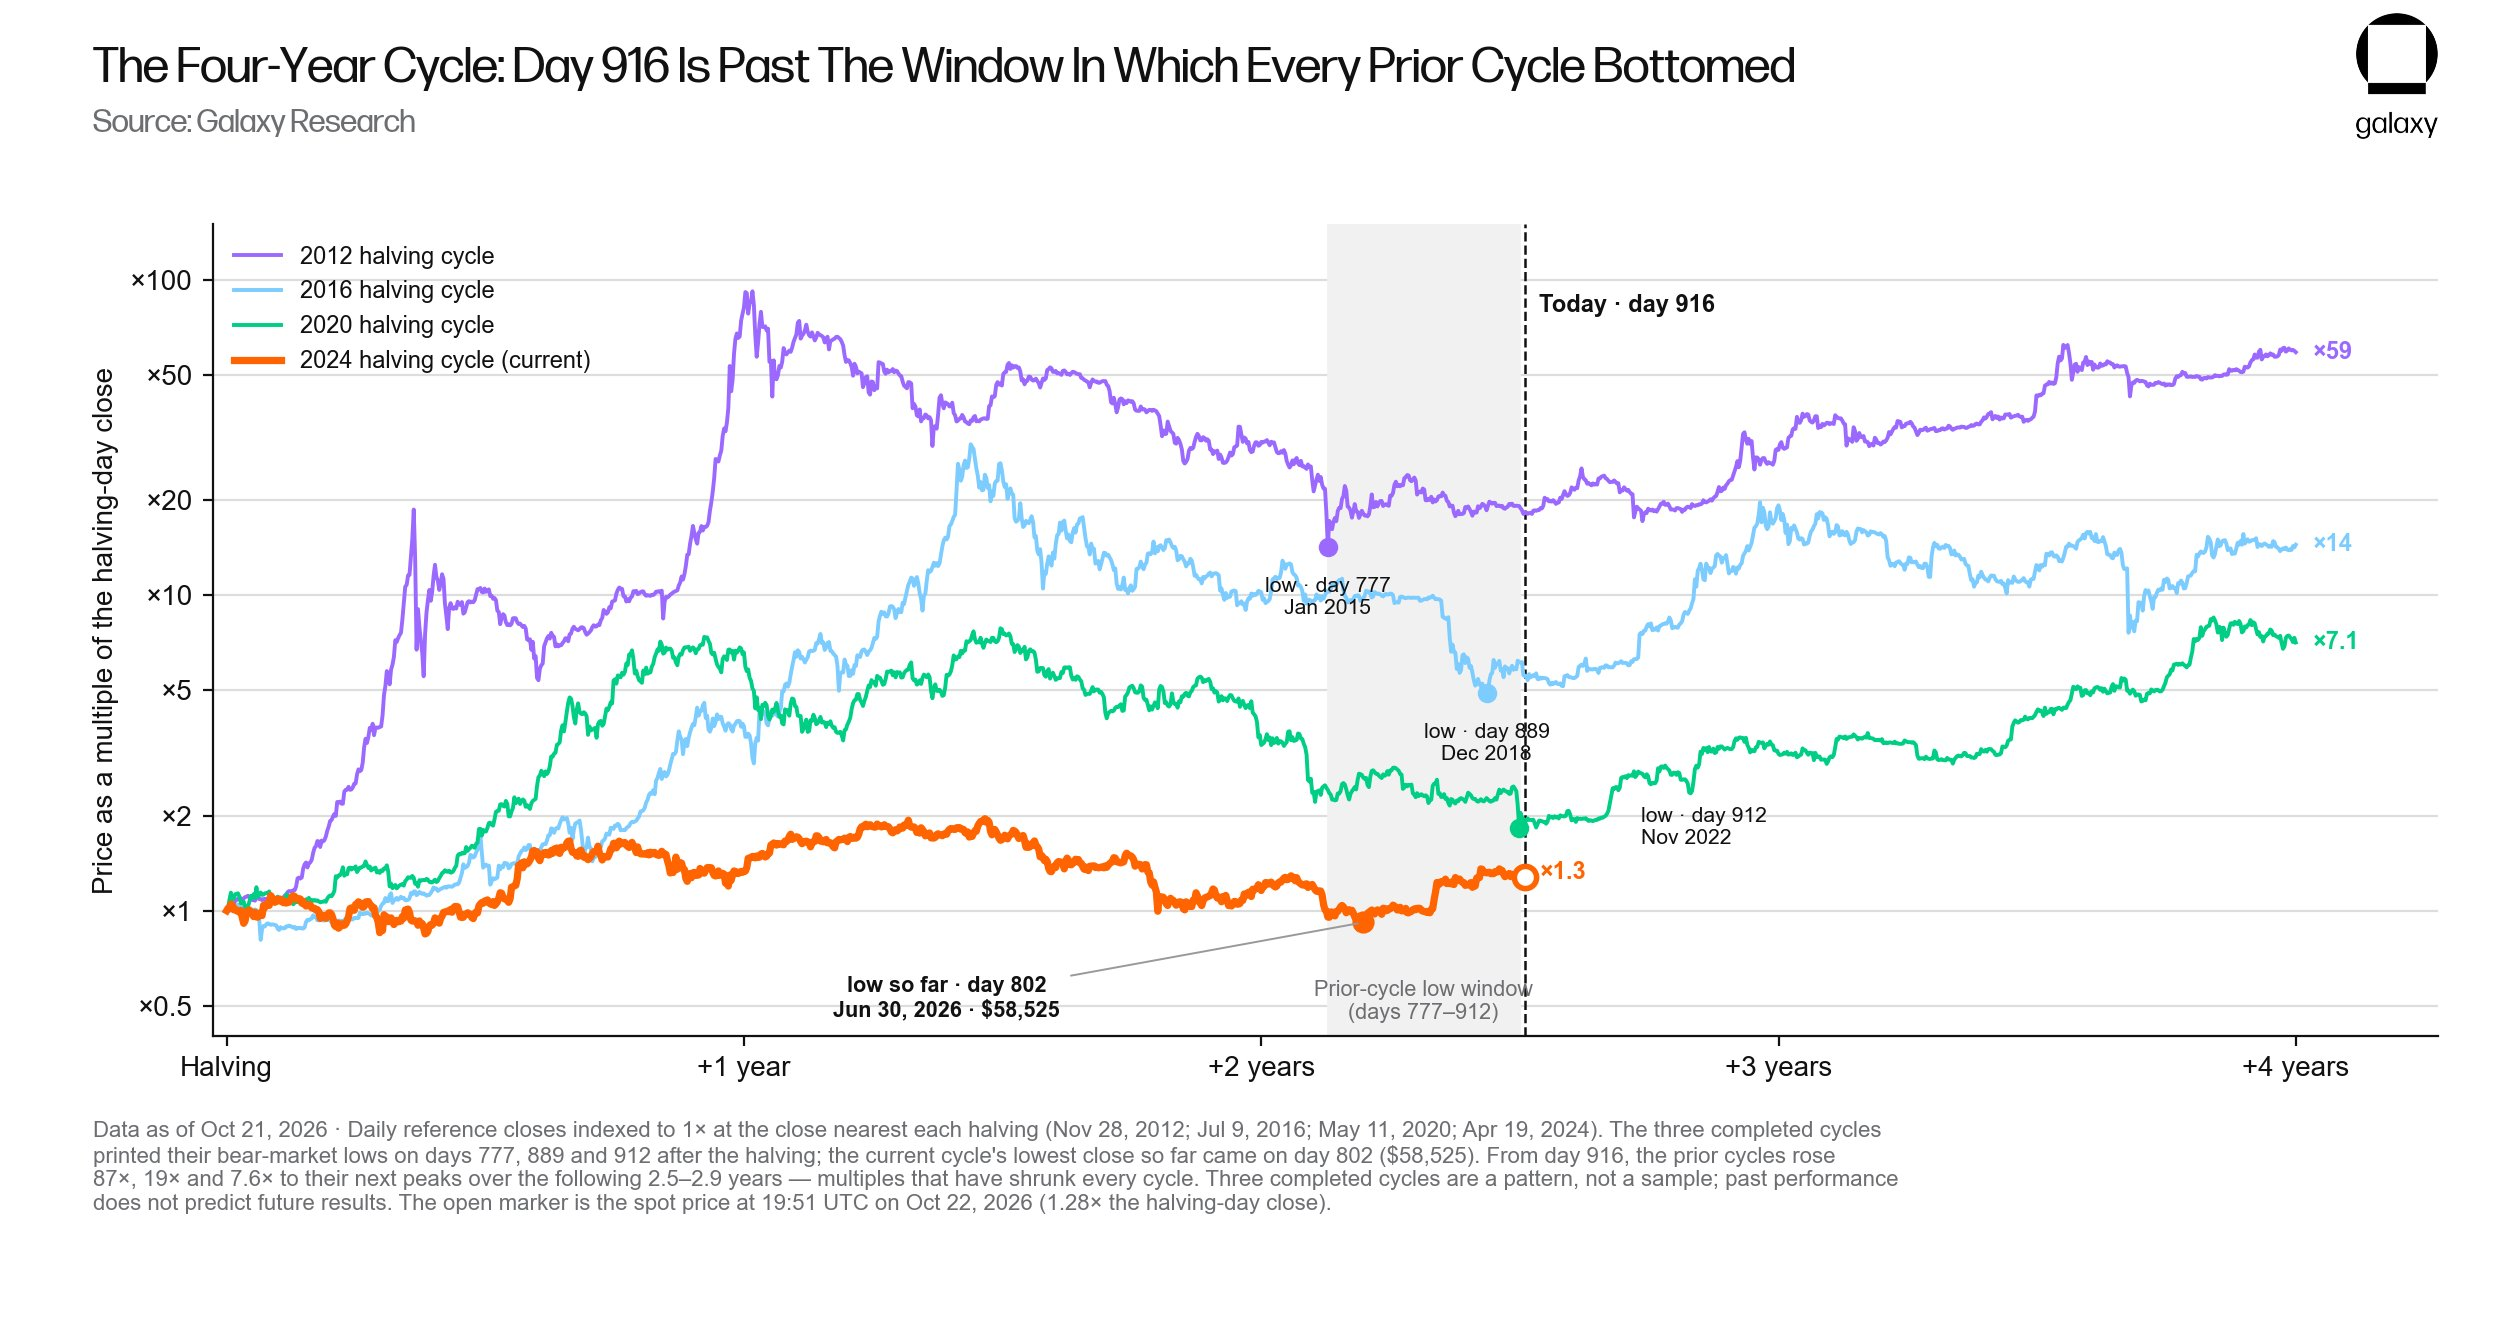
The four-year cycle theory also corroborates this. In the first three cycles, Bitcoin hit its low on day 777, day 889, and day 912 after the halving, respectively; the low in the current cycle so far occurred on day 802. Based on this day count, in previous cycles the price gains from low to next peak were 87x, 19x, and 7.6x, respectively. Although the multiple decreases with each cycle, the directional pattern of price movement has not broken down.
This cycle is the shallowest bear market on record (a drawdown of -53%, compared with -93%, -85%, -84%, and -77% in previous bear markets). It is also the first bear market in which the price never fell below the network cost basis at any point, with a market cap to realized value ratio of 1.10, compared with 0.56, 0.69, and 0.75 at the lows of the previous three cycles.
The average cost of the coins that drove Bitcoin's rebound from $58,525 was $74,811, and the price first recovered above that cost basis on August 19. As of October 22, holders of these coins were up 9%, with a spent output ratio of 1.009 and no profit-taking, consistent with a typical accumulation pattern.
In addition, the selling pressure that formed resistance at the 2025 high is weakening.
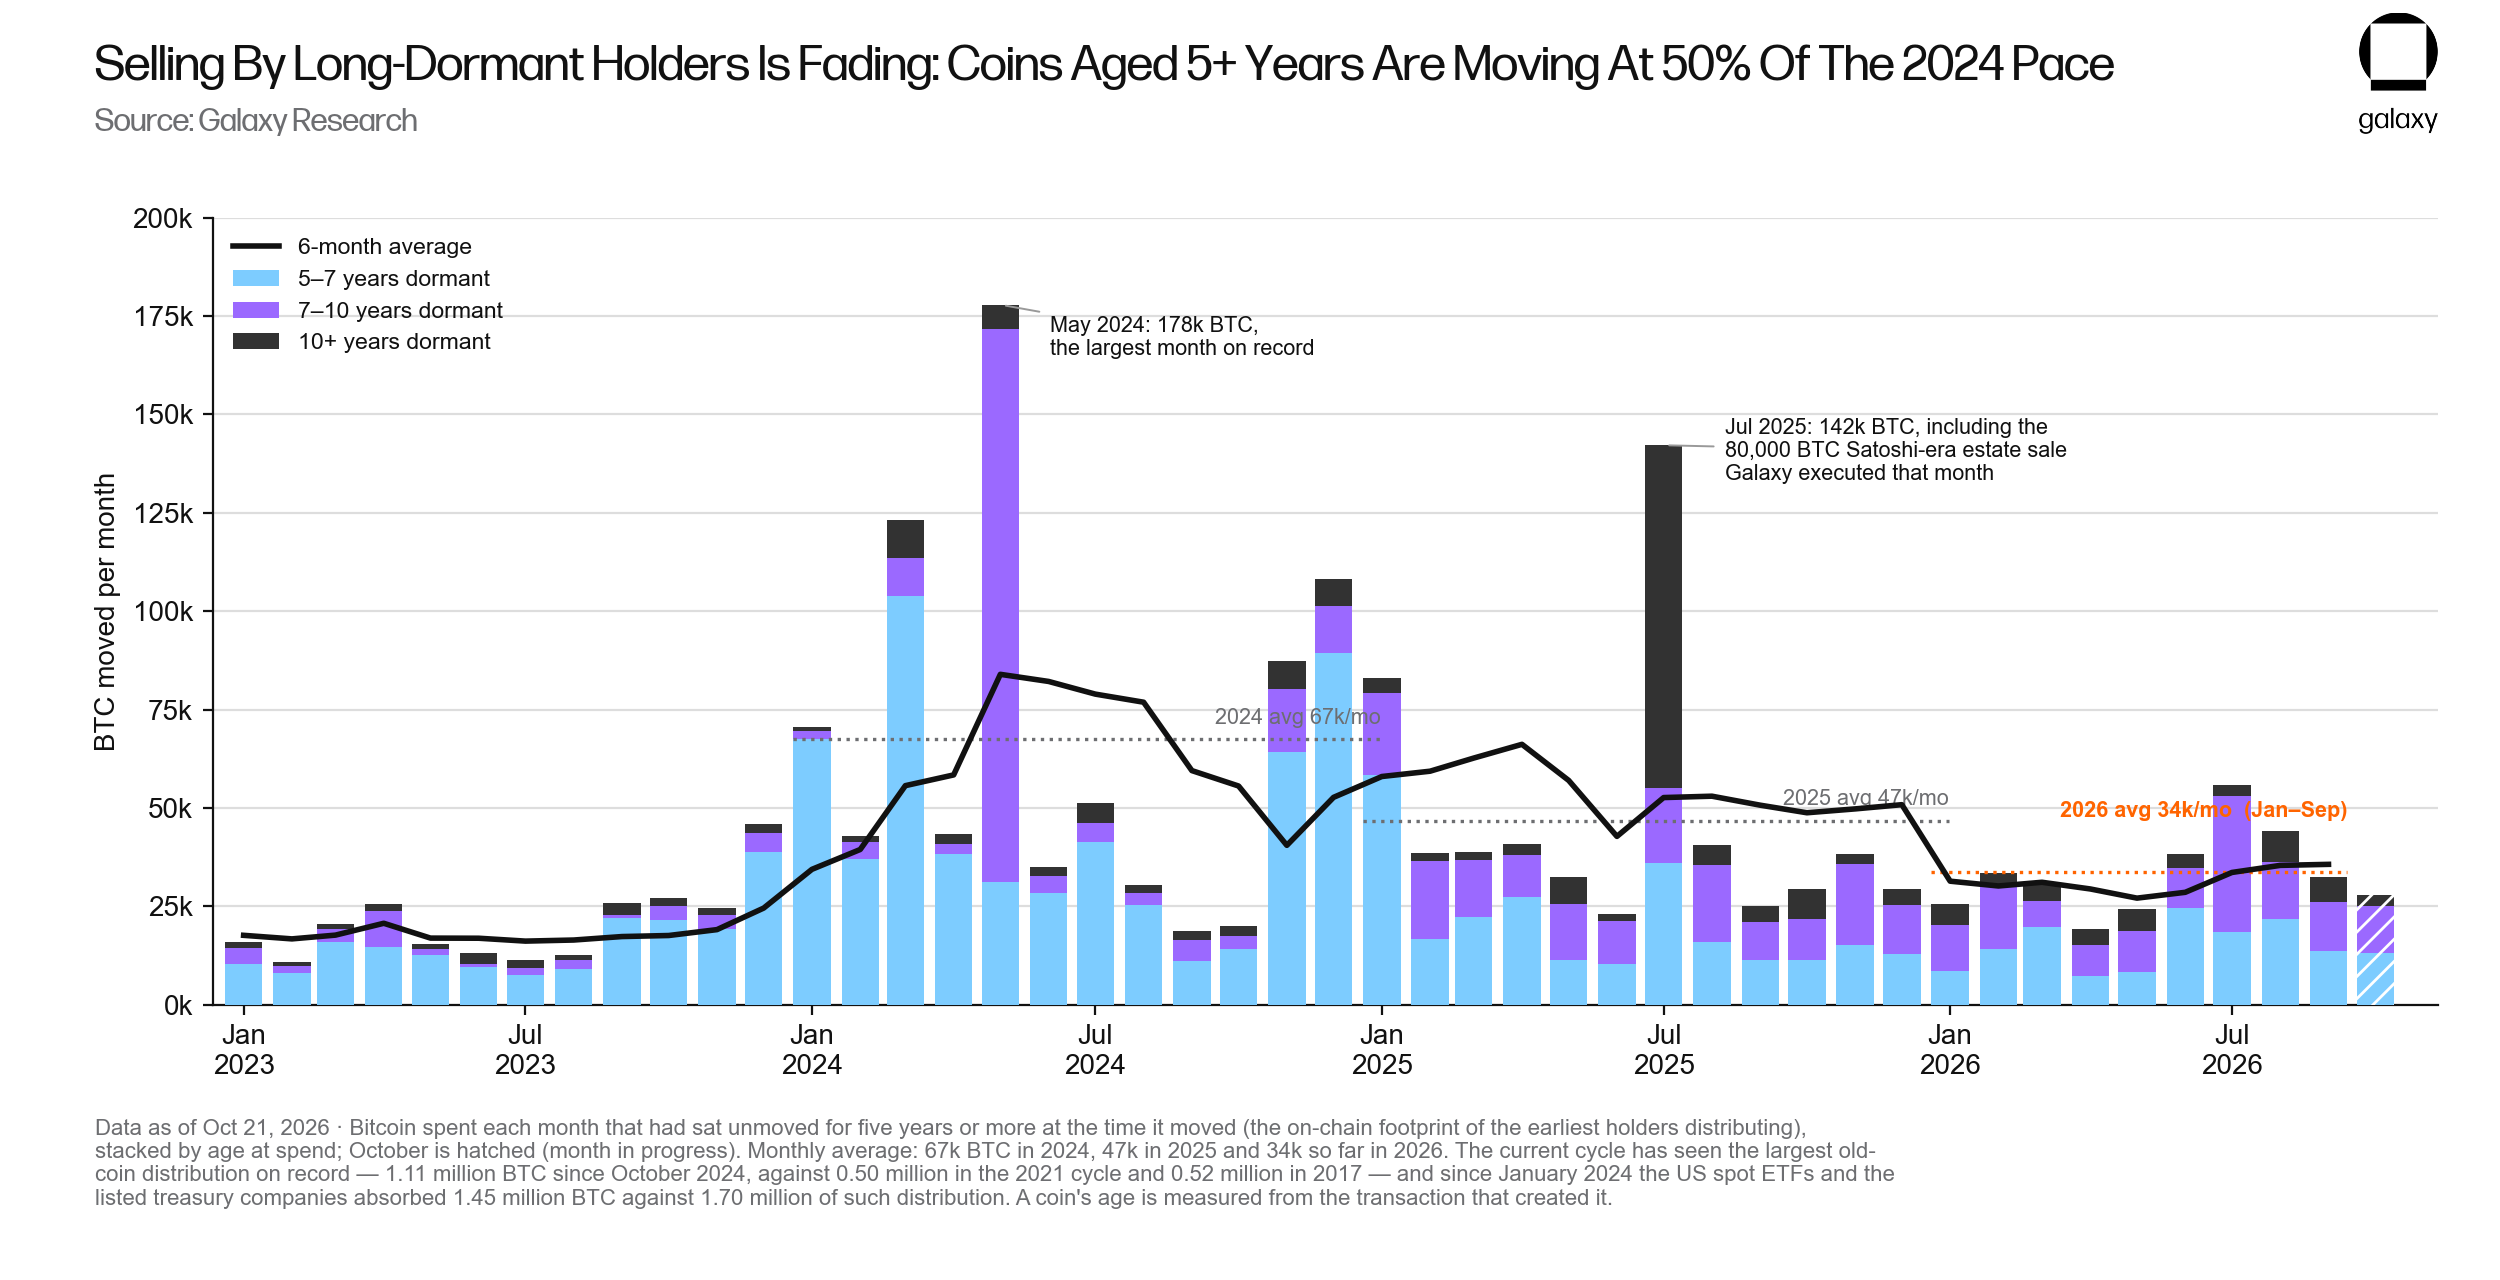
In 2024, Bitcoin that had not moved for five years or more had an average monthly turnover of 67,000 coins, versus 47,000 coins in 2025. Since October 2024, total turnover of such "old coins" has reached 1.11 million coins, the largest distribution in any cycle, most of which has been absorbed by spot ETFs and DAT companies holding Bitcoin. In 2026, this turnover rate fell to 34,000 coins per month, only 50% of the 2024 level.
Market Positioning: "Fast Money" Has Left, Long-Term Holders Remain
Futures market data shows that macro investment funds currently hold a very low share of Bitcoin.
According to US CFTC financial futures trader data, in the week Bitcoin's price hit an all-time high, asset managers' net long positions in CME Bitcoin futures were 43,300 coins, and have now fallen to 18,400 coins (a decline of 57%); leveraged funds' net short positions (i.e., the futures leg of the spot ETF cash-and-carry trade) also shrank from 74,100 coins to 30,600 coins; total dollar-denominated open interest fell by 51%.
The arbitrage yield supporting these short positions has almost entirely disappeared. In the 30 days before Bitcoin hit its all-time high, the annualized average basis of the front-month contract was 7.9%, 3.9 percentage points above the 3-month Treasury yield; in the 30 days ending October 21, that basis was 4.8%, only 0.6 percentage points above the Treasury yield.
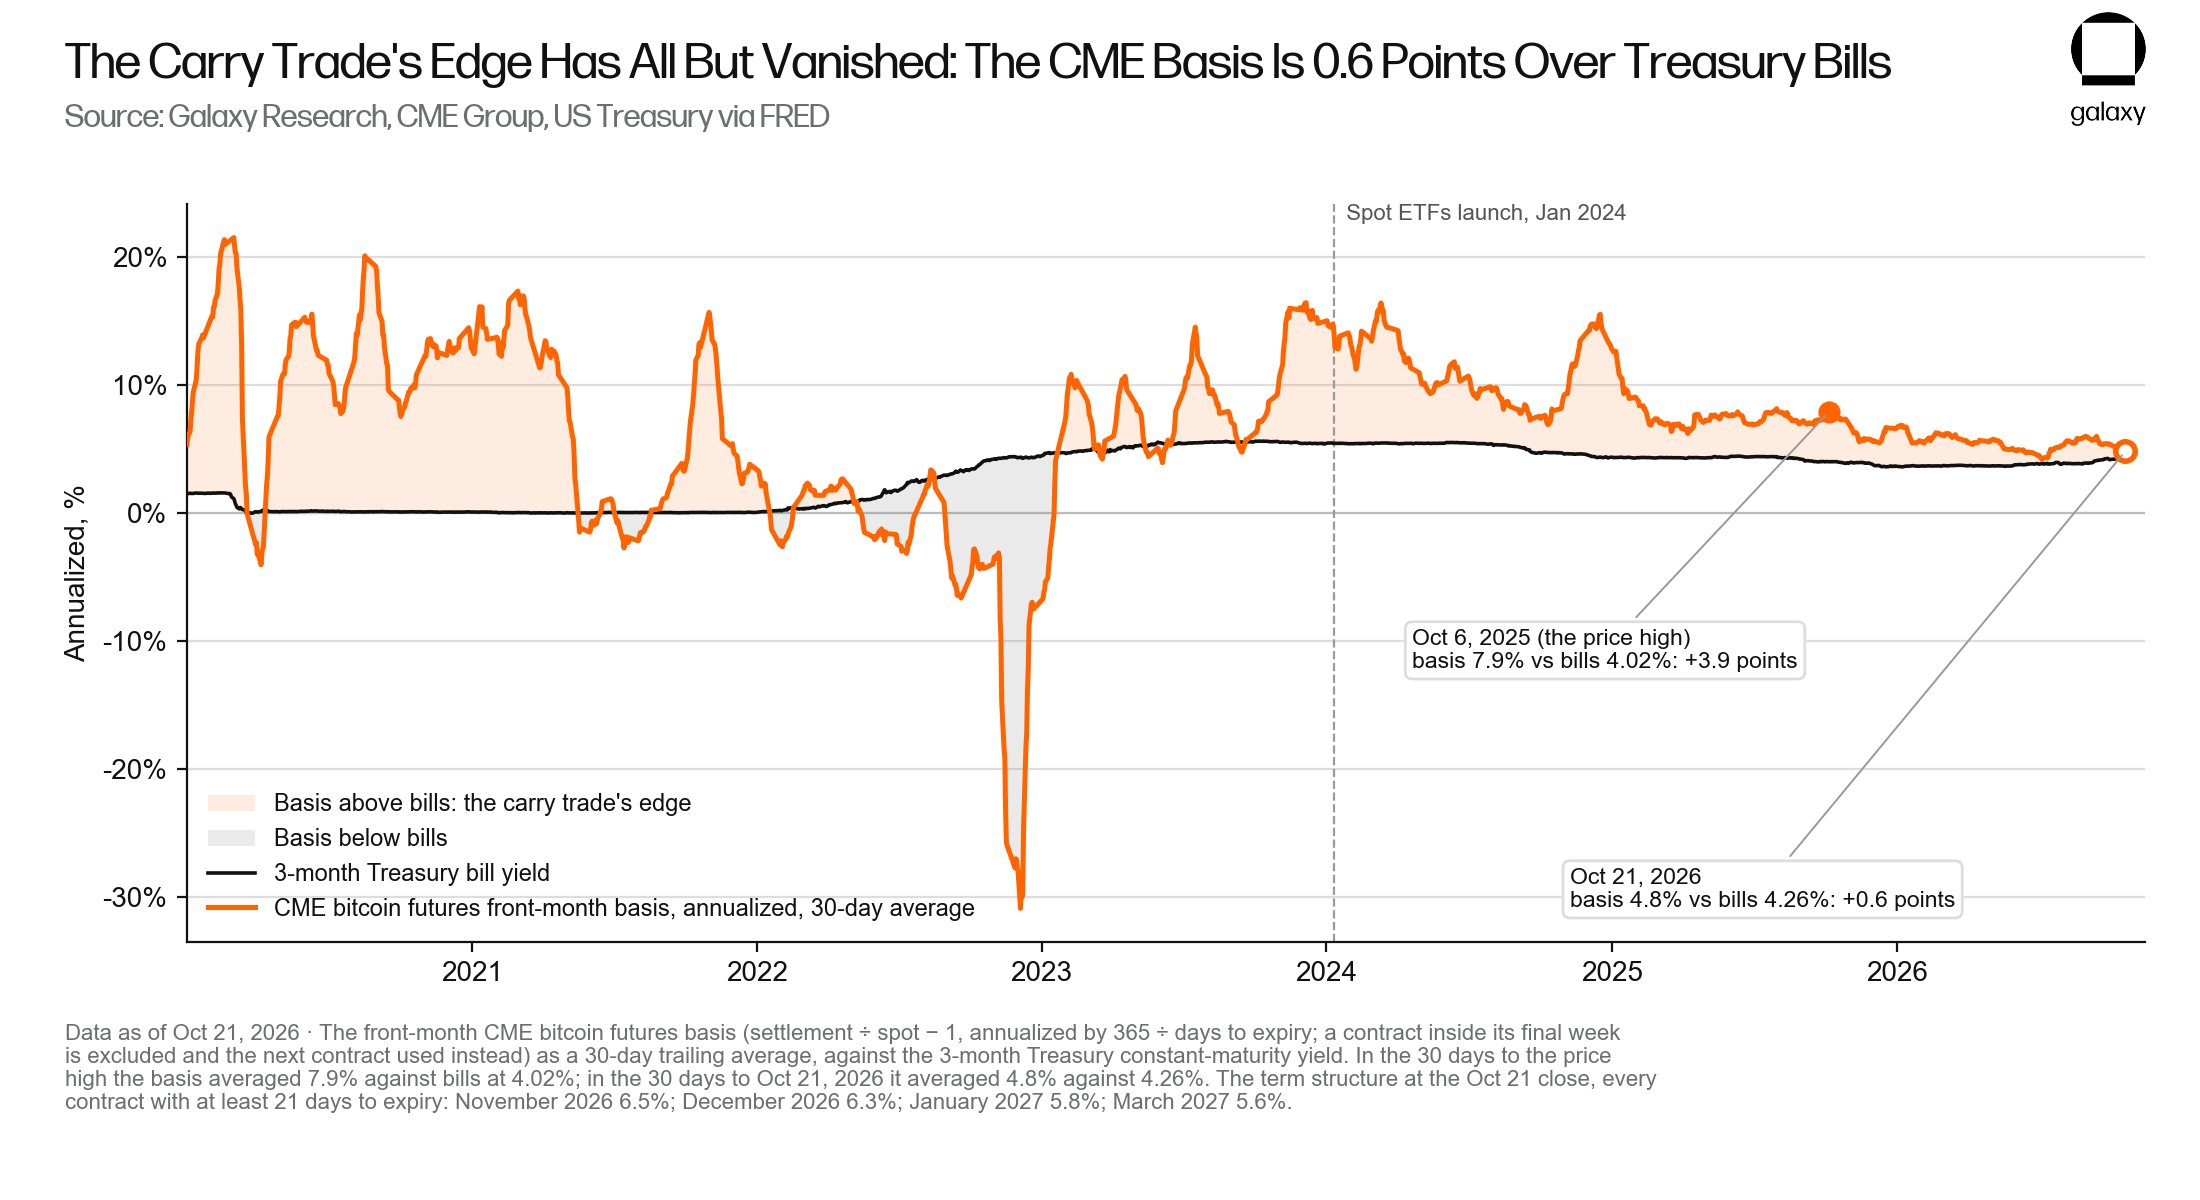
At the far end of the futures curve, although some yield can still be captured, arbitrage traders cannot fully capture these gross returns. ETF management fees, monthly roll costs, and margin that must be posted at the clearinghouse consume about 1 percentage point of the yield, leaving traders with perhaps only about 1.5 percentage points of excess return (relative to spot). By comparison, when the price hit its all-time high, the same calculation produced about 3 percentage points of excess return, and if looking only at the 9.8% annualized yield offered by the front-month contract at the time, the return was even higher.
Once the financing cost of long positions is set at SOFR (Secured Overnight Financing Rate) plus a spread, the additional return that leverage can generate becomes minimal. And after deducting financing costs, the remaining return cannot even cover the tail risk this trade may face, such as the basis inversion in December 2022, when the annualized rate reached -31% (see chart above).
It is this economics, rather than the Bitcoin price itself, that has driven multi-strategy trading teams away.
Macro Speculators Cut Positions, Long-Term Funds Buy
The 13F filings of asset management institutions reveal the situation of many institutional sellers, mainly including institutions engaged in basis trading and macro speculators. As of September 30, 2025 (the last quarter-end before the price peak), reporting institutions held spot ETF positions equivalent to 355,000 Bitcoin; by June 2026, that figure had fallen to 307,000 coins (a decline of 14%).
This reduction came almost entirely from multi-strategy funds, macro funds, basis trading desks, and bank proprietary trading desks, which had previously used ETFs for arbitrage or momentum trading.
Nine institutions—Millennium Management, Brevan Howard, Goldman Sachs Group, Capula Management, Farallon Capital, D. E. Shaw, Schonfeld Strategic Advisors, Symmetry Investments, and Tudor Investment Corp—reduced their positions by between 29% and 100%, collectively cutting 68,000 Bitcoin. This exceeds the total reduction of 48,000 Bitcoin across all 2,200 reporting institutions; therefore, apart from these nine institutions, all other reporting institutions collectively increased their holdings.
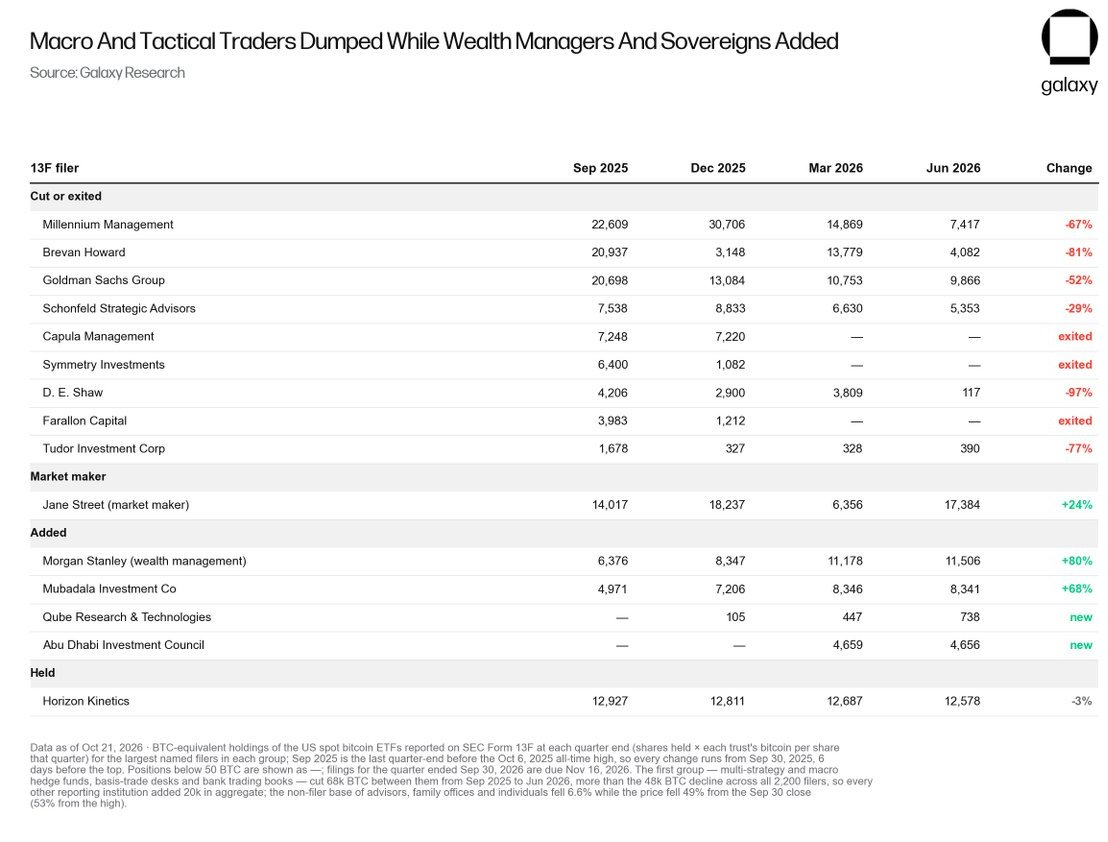
Wealth management platforms and sovereign wealth funds took over the shares sold by these speculators. In addition, among those not required to file 13F reports (including investment advisors, family offices, and individual investors), positions fell only 6.6%, while Bitcoin's price fell as much as 49% over the same period.
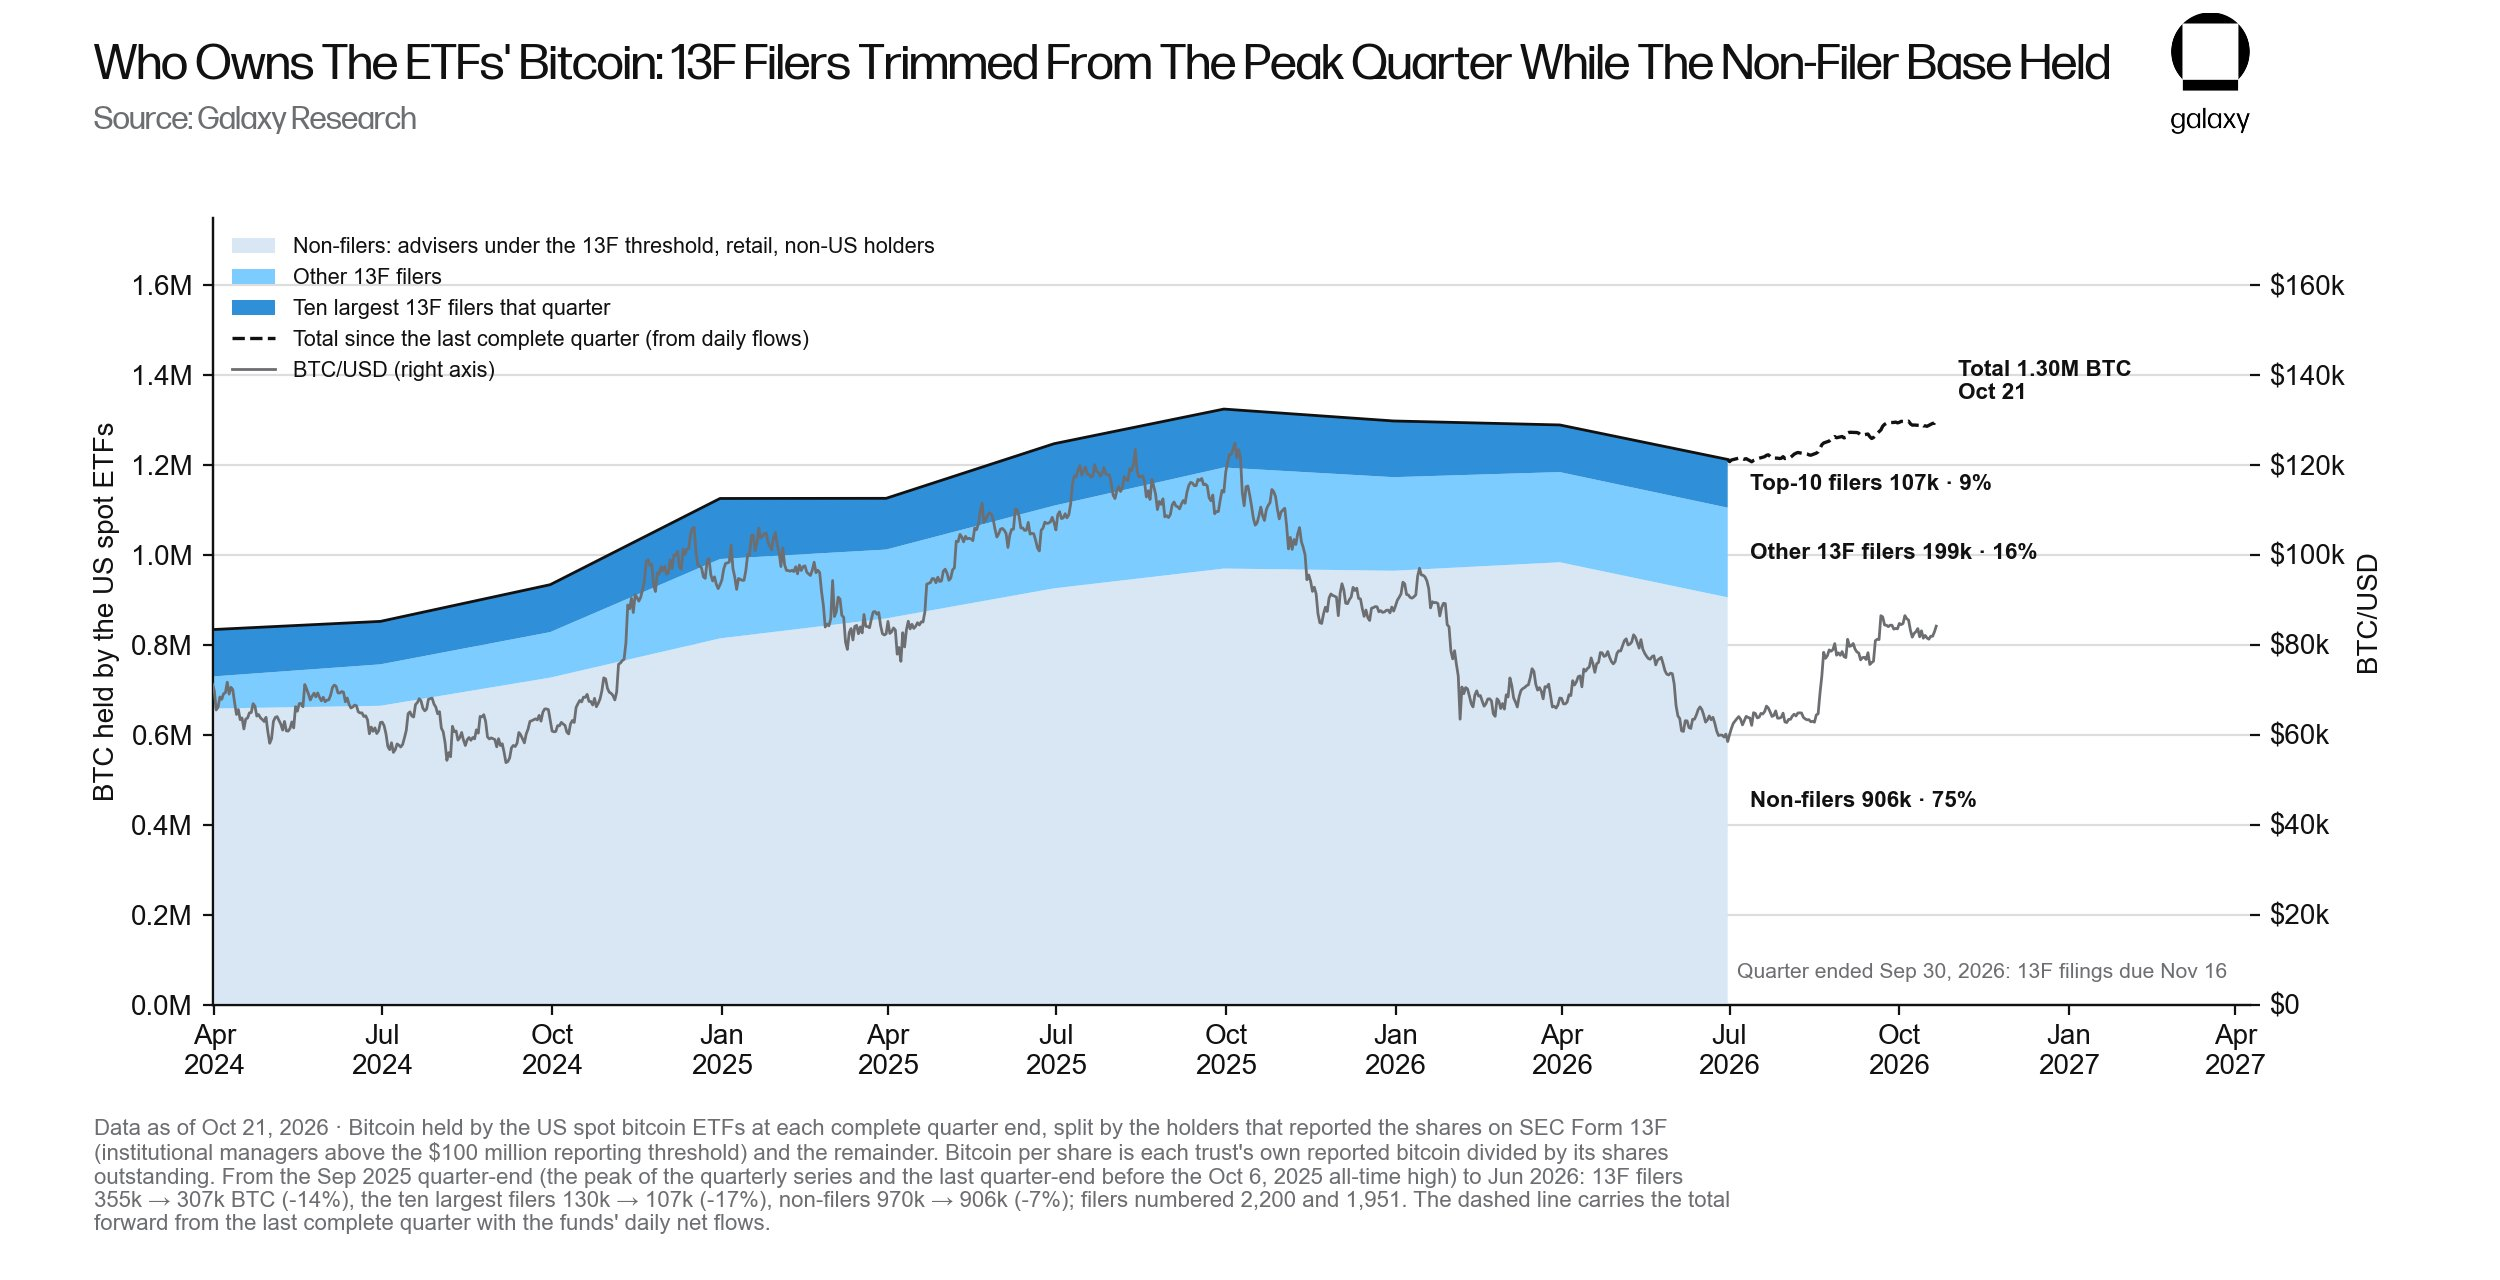
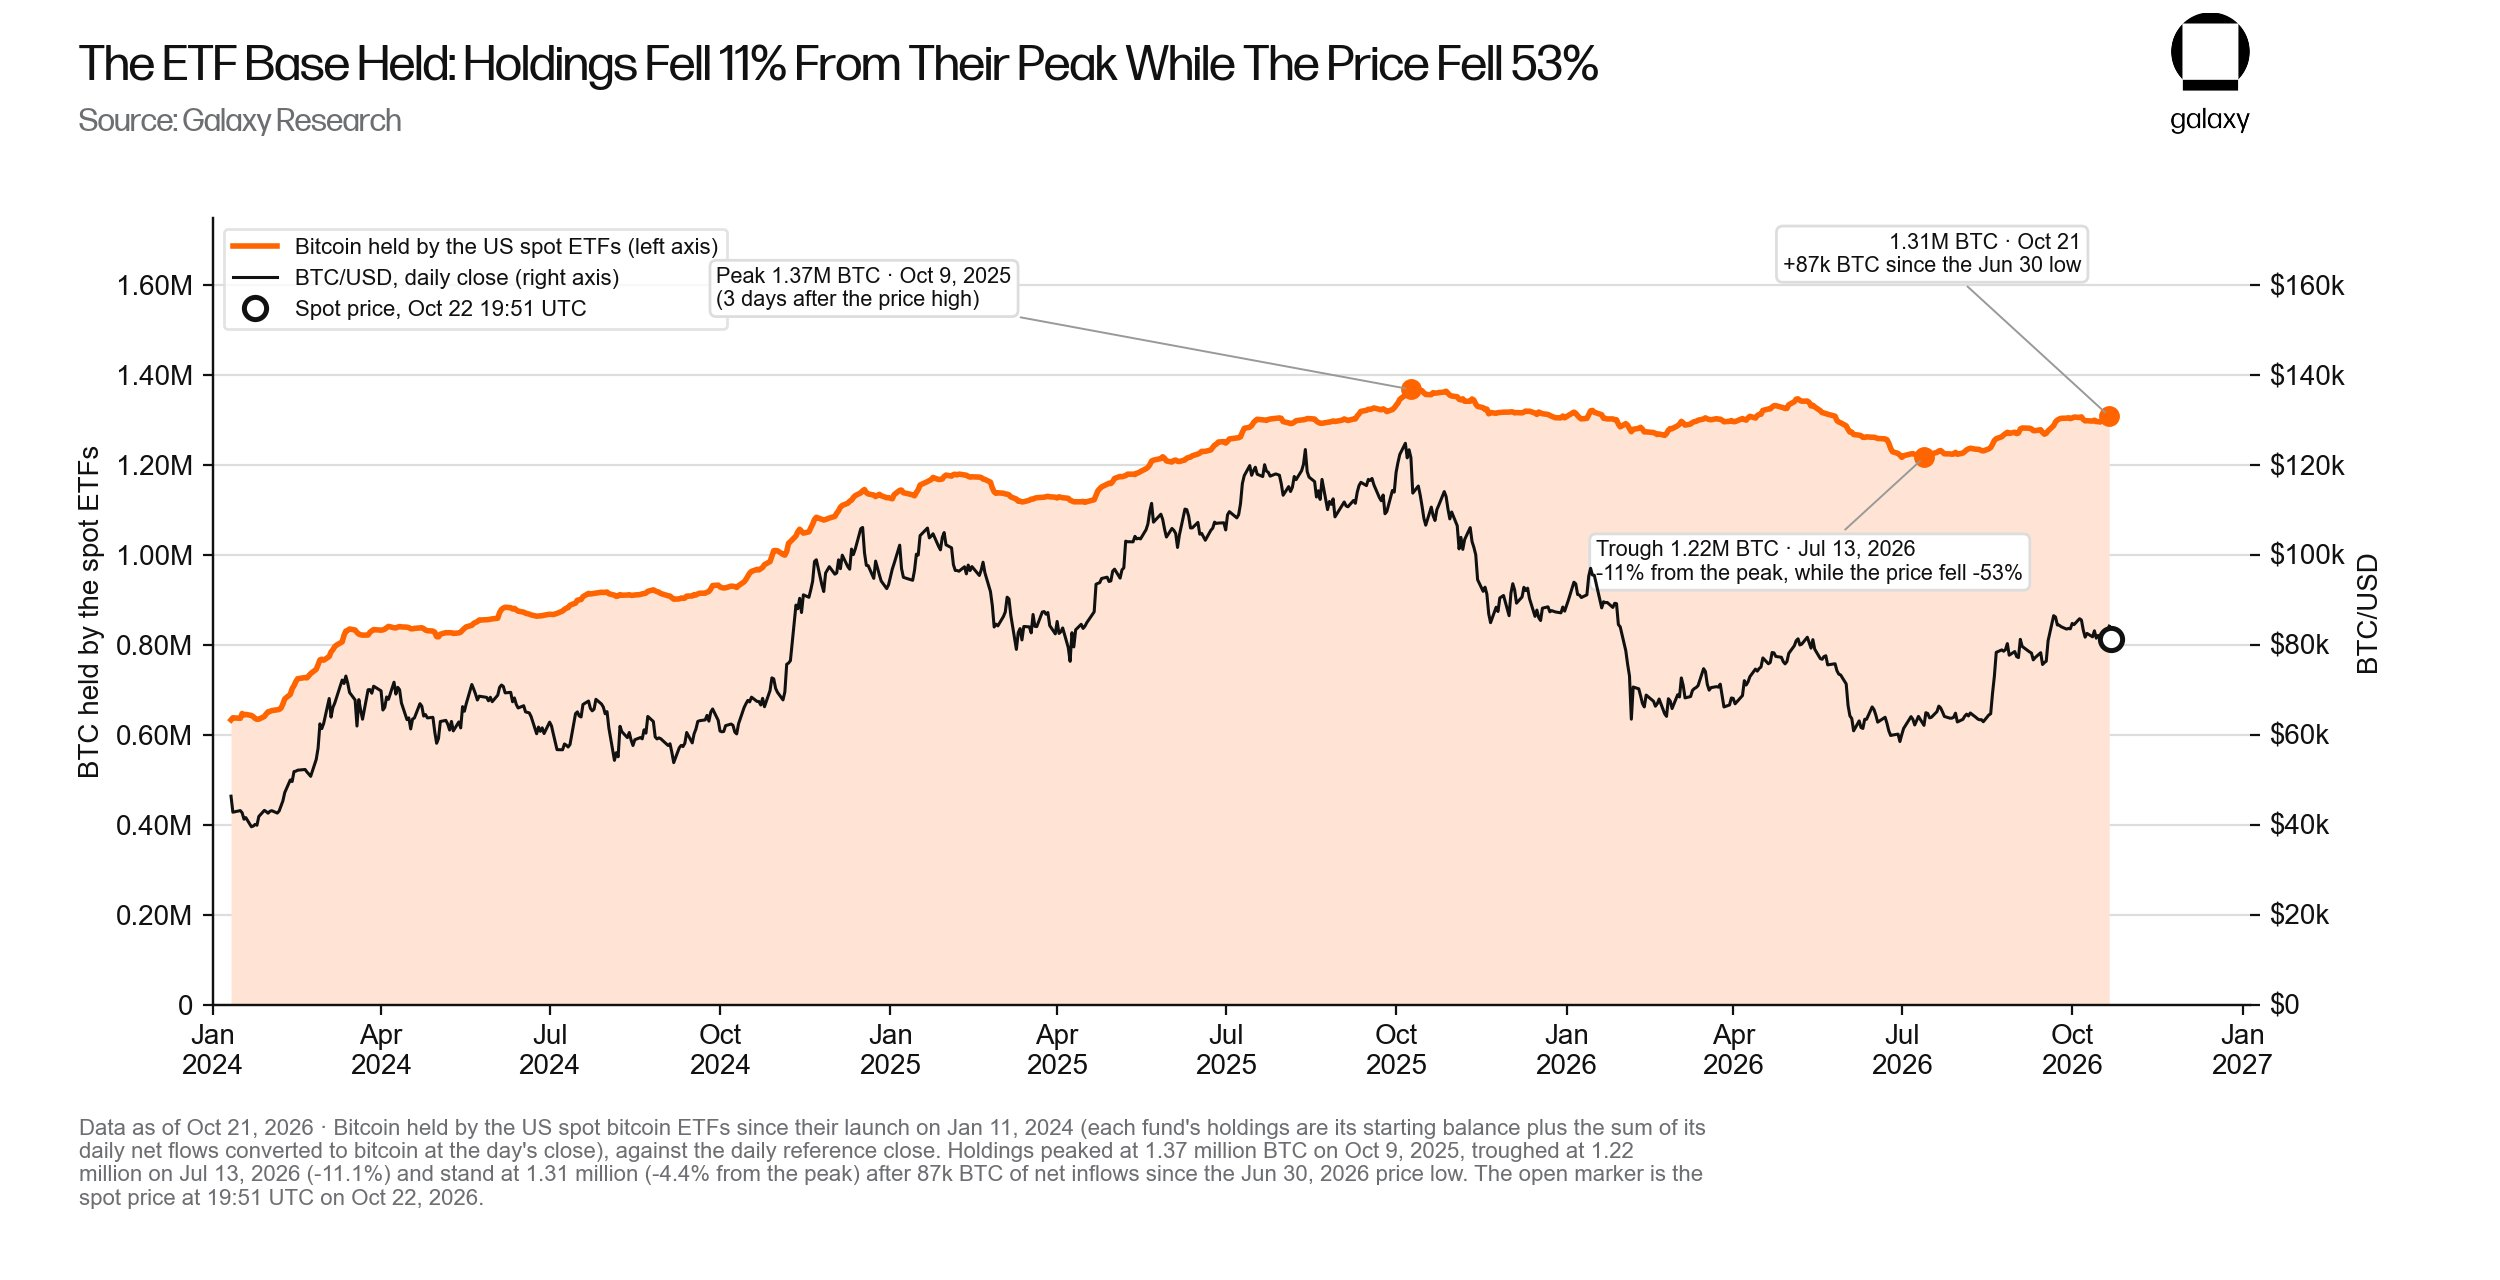
ETF holdings fell 11% from peak to trough, while Bitcoin's price fell 53%. Since the June low, ETF holdings have increased by 87,000 Bitcoin, while leveraged funds' short positions have decreased. This suggests flows have favored directional buying rather than arbitrage trades, which may also explain why this year's market panic did not trigger Bitcoin selling.
Fundamentals: AI Investment Accelerates Currency Debasement, Bitcoin Will Ultimately Appreciate
As of October 20, 2026, total US federal debt had reached $40.44 trillion, up from $23.2 trillion in early 2020; at the end of fiscal year 2026, the fiscal deficit was $1.99 trillion, or 6.2% of GDP, and annual government interest expense reached $1.28 trillion.
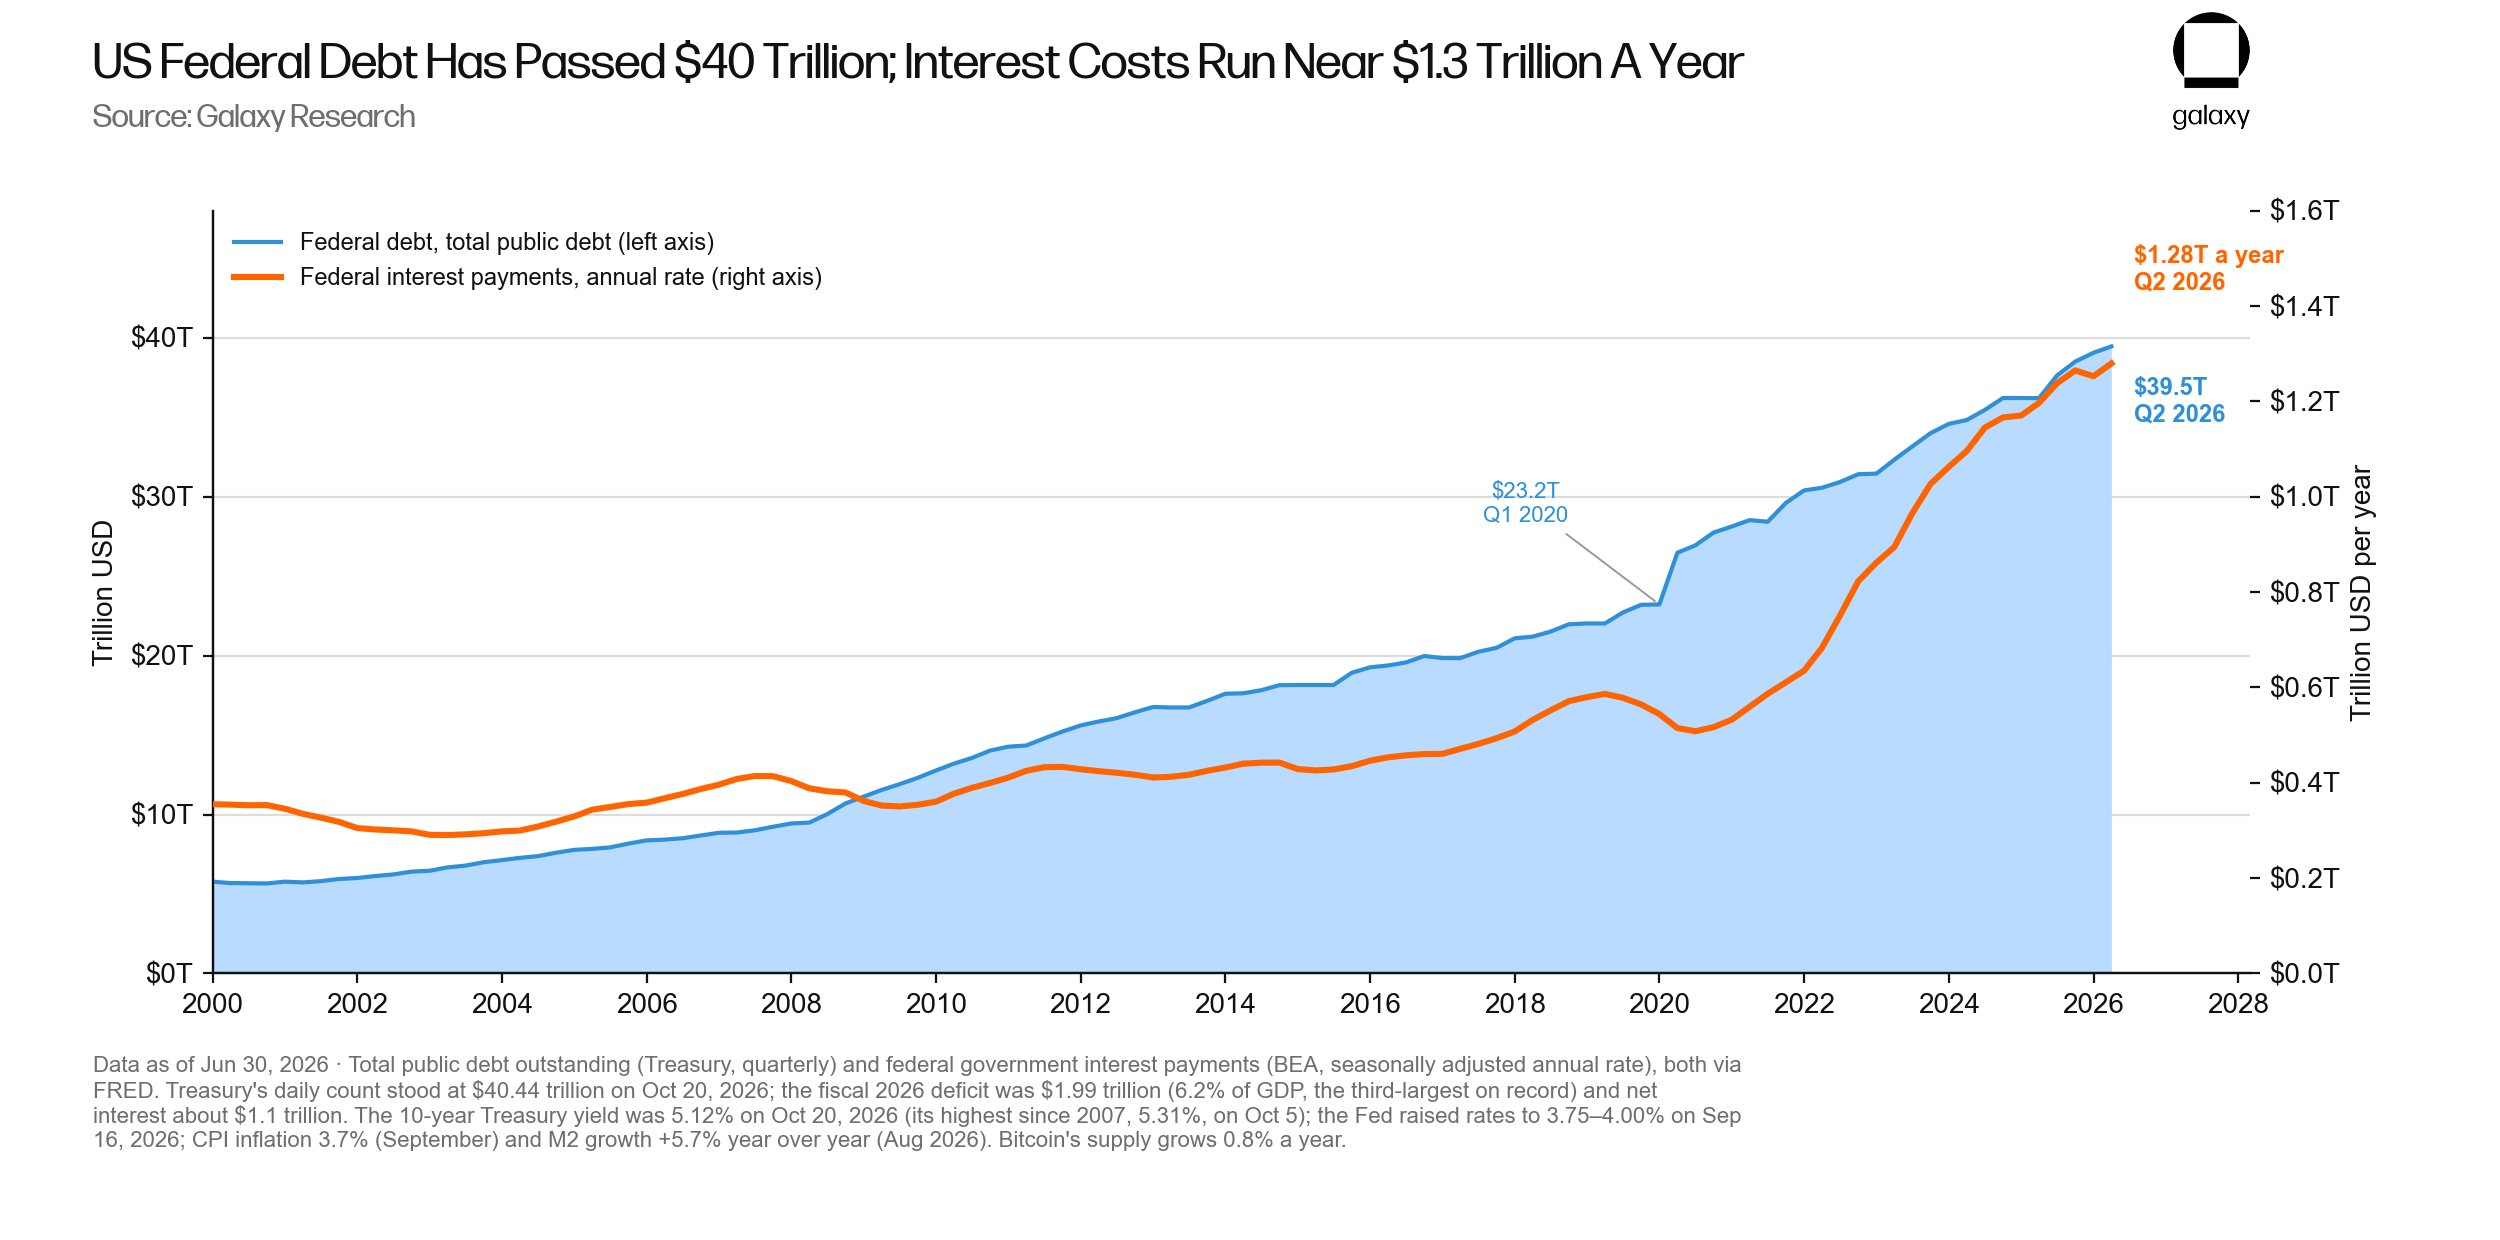
The bond market has begun to react. On October 5, 2026, the 10-year US Treasury yield reached 5.31%, a new high since 2007; on September 16, 2026, the Fed raised rates to the 3.75%–4.00% range, when CPI inflation was 3.7% and M2 money supply growth was 5.7%.
When a sovereign nation faces a 6% fiscal deficit while also needing to refinance $40 trillion in debt at a 5% interest rate, the pressure to dilute debt through inflation grows ever greater. Historical experience corroborates this trend: whenever stress emerges, central banks always return to the market as the "buyer of last resort," as happened in 2020 and March 2023.
AI infrastructure buildout is often seen as a competitor to Bitcoin in the competition for capital, but it is itself a "currency debasement machine."
Morgan Stanley expects AI-related debt issuance to reach $570 billion in 2026; by 2028, about $1.5 trillion of AI infrastructure buildout will need to be financed externally. If this investment ultimately materializes, it will in effect be financed through credit expansion; if it fails, the losses will be socialized, that is, borne by society as a whole. Either way, the supply of claims (or entitlements) on the future is growing, so the value of a hard-money asset with a fixed issuance (Bitcoin) will surely rise accordingly.
This fundamental logic predates any interest rate cycle. The demand for money that cannot be frozen, cannot be surveilled, and cannot be tampered with will grow as the capability to carry out such interventions increases—and AI is precisely what makes these interventions extremely cheap.
Tokenized deposits and stablecoins are designed with backdoors that allow freezing, while Bitcoin is the only holder-owned asset of meaningful scale that has no issuer. As the financial system moves toward programmable money, demand for this "escape hatch" continues to rise.
Market Sentiment: The Market Narrative Shifts for the Third Time Toward "Blockchain Without Bitcoin"
Previously, mainstream finance embraced blockchain technology but rejected Bitcoin as an asset.
Between 2015 and 2016, as the banking sector's R3 consortium was formed and The Economist published a cover article titled "Trust Machine," "blockchain, not Bitcoin" became the mainstream accepted view at the time. During that period, Bitcoin's weekly closing price fell to a low of $231, and the subsequent cycle high was 83x above that.
Between 2018 and 2019, the mainstream narrative shifted to "blockchain, not crypto." JPM Coin and Libra emerged in succession, while Bitcoin was seen as thoroughly finished, with its price falling to $3,195, and the subsequent cycle high was 20x above that.
In 2026, the market has evolved to "stablecoins and tokenization, not Bitcoin." Banks are piloting tokenized deposits, the CLARITY Act failed to pass a procedural vote, and AI has fully dominated the market's growth narrative. Whenever sentiment swings to this degree, Bitcoin is typically less than a year away from a cycle low





