Weekly Editor's Picks (1017-1023)


- Core Viewpoint: This week the market focused on macro risks and structural contradictions in the crypto industry: expectations of the U.S. midterm elections and fiscal battles are heating up, with gold and the U.S. dollar and Treasuries showing a rare divergence; meanwhile, although Perp DEXs such as Hyperliquid contribute huge fees, retail traders are suffering large-scale losses, raising questions about the profit distribution mechanism.
- Key Elements:
- Trump's approval rating has fallen to the lowest of his term, with Democrats holding the advantage in the midterm elections, but the 2027 debt ceiling and appropriations battle will be hard to avoid, and the market may face turbulence.
- Gold has erased all its gains since August, diverging from the trend of the U.S. dollar and Treasuries, with global risk assets coming under simultaneous pressure, and the liquidation effect may still be spreading.
- Retail traders on Hyperliquid's six major applications have lost a combined $280 million, with fees accounting for more than half of the losses, and most users stop trading after the third month.
- 38 Perp DEXs generated about $125 million in fees over the past 30 days, with Hyperliquid alone accounting for $84.55 million, and the top five together making up 85.6%.
- The OCC published the final rules for the GENIUS Act, clarifying requirements for stablecoin issuance, reserves, and redemption, effective in January 2027, and easing third-party reward arrangements.
- New MSCI rules plan to remove crypto treasury companies such as Strategy from global indexes, effective after the November review, which may trigger concentrated selling by passive funds.
- Circle retains only 7 cents of net profit for every $1 of revenue, giving up most of it to distribution partners and compliance infrastructure, with USDC accounting for about 77% of stablecoin transaction volume.
The information feed moves too fast, and in-depth analysis articles are easily drowned out by hot topics. The "Weekly Editor's Picks" column pulls content with judgment value out of the flood of information, helping you filter out the noise, retain insights, and bring inspiration.
Macro Landscape
Trump's approval rating has fallen to the lowest level of his presidency, and polls also show Democrats in a favorable position in the election race. However, even if Democrats win one or both chambers, they cannot directly take over the White House's executive power. Trump can still exercise the presidential veto and continue to wield broad executive authority in areas such as tariffs, immigration, and foreign policy.
Regardless of which party ultimately controls Congress, a struggle over raising the debt ceiling and federal government funding in 2027 is highly likely to occur. Two economists expect markets and investors to face a turbulent year.
Bond yields are falling, yet this has likewise failed to lift precious metals. The gold market is behaving abnormally, and the yen has already strengthened sharply. This may mean intervention actions aimed at driving up the yen are taking place in the market, which is usually bearish for the dollar.
Gold prices have given back their gains since August, with the entire rally almost completely erased.
Global risk assets are under simultaneous pressure, and the liquidation effect may still be spreading.
Japan's accumulated savings continue to flow overseas, especially into U.S. bonds and equities, providing an important source of funding for the prosperity of U.S. asset markets. But if investors begin to lower their expectations for U.S. economic growth, this massive capital flow could change direction, and pressure for Japanese funds to return home may rise accordingly. The yen could strengthen.
The yen's rally extended to its strongest level in more than a month, as a selloff in tech stocks prompted investors to turn to traditional safe-haven assets including the Japanese currency, Japanese government bonds, and U.S. Treasuries.
Investment and Entrepreneurship
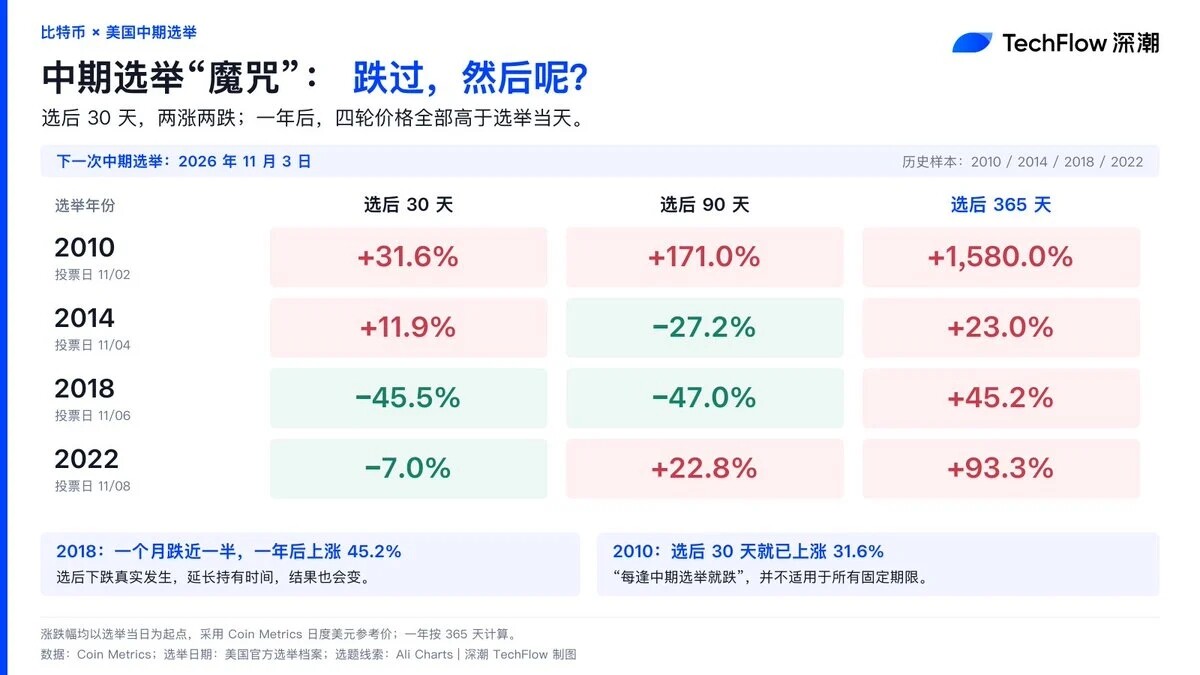
After Four Midterm Elections in History, How Did BTC Actually Perform?
Today's BTC has been widely co-opted by traditional financial channels and increasingly resembles a high-beta risk asset, with its correlation to U.S. stocks, dollar liquidity, and global risk appetite clearly strengthening. Therefore, policy expectation changes brought by midterm elections will most likely transmit to BTC's price action; however, note that this should not be understood as BTC being directly tied to election results—it is simply that in this cycle, it is clearly visible that BTC's sensitivity to macro risk appetite has been maxed out.
Behind Hyperliquid's Massive Consumer Expansion, 400,000 Retail Traders Lost $280 Million
While consumer-facing apps are raking in profits, the retail traders placing orders through such apps seem to be faring poorly—Hanson Birringer, co-founder of Hyperdash, found that across the six major mainstream apps integrated with Hyperliquid, retail traders have collectively lost $280 million.
The losses come from two sources—trading P&L and fees. Across these apps, fees accounted for the bulk, slightly more than half of the $126 million in losses. BTC was the market where users traded the most and suffered the heaviest losses.
These apps did fulfill the original design intent of Builder Code—bringing new traders, trading volume, and fees to Hyperliquid. Unfortunately, the users brought in are losing most of their principal due to overtrading, high fee drag, and liquidation. Most of them stopped trading after the third month.
Perp DEXs Generate $125 Million in Fees per Month—Who Is Really Being Rewarded?
Over the past 30 days, according to PerpsAtlas statistics, 38 Perp DEXs generated approximately $125 million in user fees. Hyperliquid alone contributed $84.55 million, with the top five platforms together accounting for 85.6%.
Traders bear trading costs and contribute fees, yet platforms use the revenue to buy back tokens, prioritizing rewards for token holders rather than necessarily those who actually generate the revenue. Tokenomics can give platform tokens value support, but it cannot replace Trader Economics.
Users farming airdrops have already paid definite costs, but whether they break even depends on token valuations they cannot control. And this calculation is even premised on the project ultimately being able to issue a token.
What PopDEX emphasizes as Trader-first means: technical investment must ultimately translate into more competitive all-in trading costs, more stable execution, and a more efficient capital usage experience.
Of the $63.2 million in net trader losses, $54.1 million (86%) was distributed to PAPER stakers. LPs received another $4.7 million, and developers got about $4.5 million (7%). Those receiving dividends are the people who lost money: the top 1,000 wallets hold 88% of PAPER, bore 81% of all losses, and took 91% of the dividends. Put plainly, this is a casino that returns the rake to the gamblers.
Revenue comes in waves along with wash trading.
PAPER has a price now, but it is very thin.
Solvency has consistently held up.
AI & Storage
AI Capital Flow Map: Nvidia Takes $690 Billion, the Other 499 Split $340 Billion
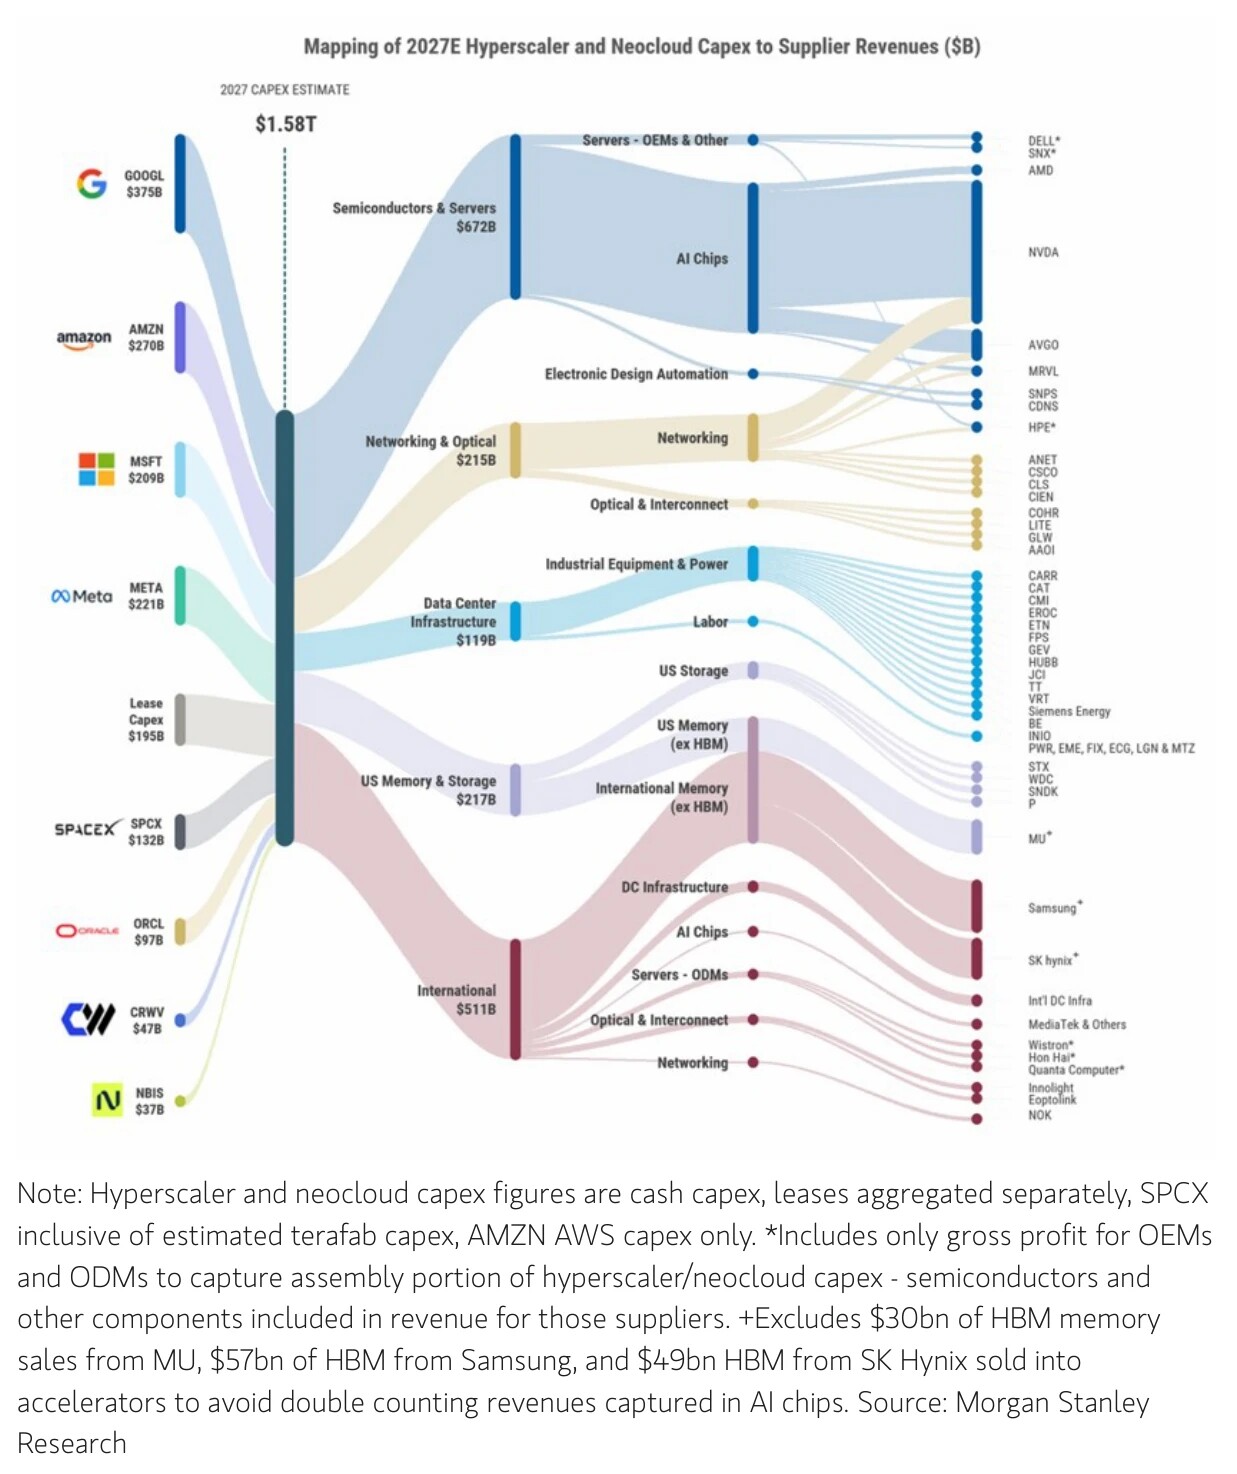
Of hyperscalers' $1.58 trillion in spending, about two-thirds of the S&P 500 benefit amount flows to Nvidia alone, while the other 499 constituents together receive only about $339 billion.
AI capital expenditure will directly drive about 25% of S&P 500 sales growth, and AI-related companies will contribute 78% of the index's earnings growth in 2027.
Hyperscalers have disclosed more than $1.1 trillion in lease commitments not yet commenced; this portion of "synthetic capex" does not appear under the capex line of any cash flow statement, yet is economically equivalent to debt financing. 2027 will be the year with the largest free cash flow gap for hyperscalers, when debt financing pressure will rise significantly.
Is CoreWeave's Credit Crisis More Like the 2023 SVB Panic Than the 2008 Subprime Crisis?
CoreWeave's unsecured bond yields have spiked to about 15% and CDS spreads have breached 1,000 basis points, raising strong doubts in the market about systemic risk across the entire AI capex cycle. But CoreWeave is more like the episodic panic triggered by Silicon Valley Bank (SVB) in 2023—a very small, structurally fragile instrument being used by the market as a barometer for the trillion-dollar AI capex cycle. The market has chosen the wrong reference frame—the unsecured bond market does not represent CoreWeave's true incremental financing cost.
Crypto AI's "Trillion Tokens" Generate Only $8.7 Million in Revenue per Month
Revenue is concentrated on platforms that control model supply or user access. Many gateways simply wrap OpenRouter and Venice APIs as crypto payments with a 4% to 30% markup, and once usage scales up they are easily replaced by upstream providers. Users are willing to pay more mainly for privacy and freedom from censorship.
Project turnover in this sector is also very fast.
The crypto AI model invocation market does exist, but currently verifiable paid revenue is less than $9 million per month, far removed from the token volumes announced by project teams.
Policy and Stablecoins
GENIUS Act Detailed Rules Take Effect, Bringing These Benefits to the Crypto Market
The U.S. Office of the Comptroller of the Currency (OCC) published final rules implementing the GENIUS Act, clarifying requirements for the issuance, reserves, redemption, custody, and risk management of payment stablecoins within its jurisdiction, effective January 18, 2027. Going forward, issuers must not only prove "whether reserves are sufficient," but also explain who custodies the reserves, how users can redeem for dollars, and how concentrated redemptions will be handled.
Compared with the draft, the most closely watched adjustment in the final rules is the relaxation of treatment for certain third-party reward arrangements. Space for trading platforms to distribute stablecoin rewards is preserved, but full clearance was not granted.
The first beneficiaries may be stablecoin issuers and distribution platforms such as Circle and Coinbase. Stablecoin payments are another direction that benefits. Funds entering on-chain may also flow to DeFi and RWA. For public chains hosting stablecoins, more transfers, payments, and financial activity are expected to bring growth in transaction volume, fees, and application demand. For the crypto market, what is more worth looking forward to is the potential buying pressure brought by stablecoin adoption.
White House Crypto Council: Four People, 14 Months, All Gone
On September 15, the Senate voted on a "motion to proceed to debate" on the CLARITY Act, with 49 in favor and 50 opposed, falling short of the 60-vote threshold. All Democratic senators opposed it, along with several Republican senators. The focus of contention was ethics provisions related to the Trump family's crypto assets and whether stablecoins can pay interest.
According to DLA Piper's assessment, the likelihood of Congress restarting this bill in the remainder of the current session is low, and the next window may have to wait until January 2027.
On the executive branch side, the White House crypto council, which was supposed to coordinate negotiations, no longer has a single serving member. From Bo Hines to Patrick Witt, this council took 14 months to see all four core members depart, and subsequent arrangements will have to wait until the midterm elections are completed.
MSCI's New Rules Take Effect: Strategy and 4 Other Companies Face Removal, DATs in Danger
On October 15, MSCI announced the adoption of a new screening framework for "non-operating companies," using indicators such as operating assets, operating expenses, and cash flow to determine whether certain listed companies are closer to investment vehicles. The relevant adjustments will be implemented with the November index review, with the final list of affected companies announced on November 11 and effective after the close on November 30.
MSCI's new rules plan to remove from global indices listed companies that "look more like investment vehicles than companies with actual businesses." Three crypto treasury companies—Strategy, Metaplanet, and Upexi—all appear on the potential deletion list.
Index eligibility directly affects passive fund allocation. After a company is removed, funds tracking the relevant indices need to adjust holdings, which may create concentrated selling. For treasury companies, the longer-term question is: will index exit compress valuation premiums and thereby reduce the efficiency of raising funds to buy crypto?
Why Does Circle Keep Only 7 Cents for Every $1 It Earns?
As of June, USDC accounted for about 77% of global stablecoin transaction volume, up significantly from 60% in the same period last year.
In the first half of 2026, Circle generated about $1.4 billion in revenue, of which about $819 million was paid to USDC distribution partners and transaction costs. Circle spent about $473 million (about 34 cents of every $1 of revenue) on obtaining compliance licenses, expanding banking partnerships, ensuring settlement liquidity, building compliance systems, developing new products, and advancing blockchain underlying integration. Of every $1 of revenue earned, Circle ultimately retained only 7 cents in net profit.
For years, Circle has shared the vast majority of USDC's economic benefits with partners that drive its adoption. And reinvestment is by no means a heavy administrative overhead—every additional $1 Circle invests widens its competitive moat. All Circle customers have always been able to redeem for free through standard banking channels, with settlement usually completed within at most two business days.
Circle's redemption terms are based on three fundamental principles: all Circle customers can redeem USDC for free; payment operations on the Circle Payments Network (CPN) can now enjoy free near-real-time settlement; and Circle platform customers can qualify for free near-real-time redemption through multiple methods.
USDC's operating model is essentially a continuously self-reinforcing "flywheel" designed to achieve symbiotic win-win across the entire ecosystem. The vast majority of economic benefits are directly passed on to partners driving market adoption, all customers can enjoy free redemption channels, and the revenue Circle retains is fully reinvested into its infrastructure foundation, keeping it firmly in the position of the world's most practical stablecoin.
Airdrop Opportunities and Interaction Guides
The Big Player Who Made A9 from the HYPE Airdrop—What Is He Farming Now?
HYPE was an0n2498.hl's most successful bet over the past two years, and Variational may be the next opportunity he is most looking forward to right now.
an0n2498.hl summarized the directions he favors into three groups: first, Hyperliquid and its surrounding ecosystem, including Entropy and Kinetiq; second, Variational and the surrounding ecosystem it may form in the future; and third, Ink, Nado, Quotrons, and the Kraken-related ecosystem.
What retail investors really ought to study may not just be what he is farming, but why he chose these projects, and whether the risks and rewards behind these choices match their own situation.
Also recommended: "Hot Interaction Roundup | Binance Launches Oracle Master Event; NoahAI Season 0 Event Now Live (October 21)".
Security
10 Million Tokens Minted Out of Thin Air—Has Cysic's Cross-Chain Bridge Become a Hacker ATM?
Weekly Hot Topics Crash Course
Policy and Macro Markets
The OCC published the final rules for the GENIUS Act, removing the presumption of illegality for third-party stablecoin rewards;
The U.S. SEC announced its review priorities for fiscal year 2027, focusing on tokenization, cybersecurity, and emerging technology risks;