Federal Reserve meeting minutes: All 19 policymakers supported a September rate hike, with "most" expecting one more increase this year, but signaling no urgency in October


- Core Viewpoint: The Fed's September minutes leaned hawkish, with most officials supporting one more rate hike within the year, but the market has pushed back rate hike expectations from October to December. Goldman Sachs believes a December hike is more likely, but the possibility of ending the tightening cycle is equally significant.
- Key Elements:
- The September FOMC unanimously agreed to raise rates by 25 basis points to 3.75%-4.00%, the first since July 2023, but there were clear disagreements over the rationale for the hike.
- Most officials believed further rate increases before year-end were "likely appropriate," but emphasized maintaining an "open attitude" toward each meeting, with no obvious urgency in October.
- Market-implied probability of an October hike dropped from about 70% to less than 20%, and the two-year U.S. Treasury yield fell more than 12 basis points in a week to about 4.78%.
- Goldman Sachs expects a second rate hike of the year in December, but noted that the possibility of the FOMC ultimately determining no further tightening is needed is equally significant.
- Almost all participants believed inflation risks were skewed to the upside, with energy price increases, geopolitical risks, and the AI investment boom all potentially pushing inflation higher.
- The economy remains resilient, consumer spending is solid, AI infrastructure construction supports business investment, and financial conditions still support growth.
- The joint U.S.-Japan intervention in the yen in July was implemented by the Treasury Department without using Federal Reserve funds, with Japan deploying a record 15.4 trillion yen.
The minutes from the Federal Reserve's September meeting released a hawkish signal, with most officials supporting another rate hike within the year, but the market has already pushed back rate hike expectations from October to December. After the minutes were released, Goldman Sachs noted that a December rate hike is more likely, but the possibility that the FOMC ultimately determines no further tightening is needed is equally substantial, adding more uncertainty to the trajectory of this tightening cycle.
According to the minutes of the Federal Open Market Committee (FOMC) meeting held on September 15-16 released on Wednesday, all 19 senior Fed officials unanimously supported raising the federal funds rate target range by 25 basis points to 3.75%-4.00%, marking the Fed's first rate hike since July 2023. The minutes showed that "most participants judged that it might be appropriate to further raise the target range for the federal funds rate before the end of the year," but officials simultaneously emphasized maintaining an "open mind" for each meeting.
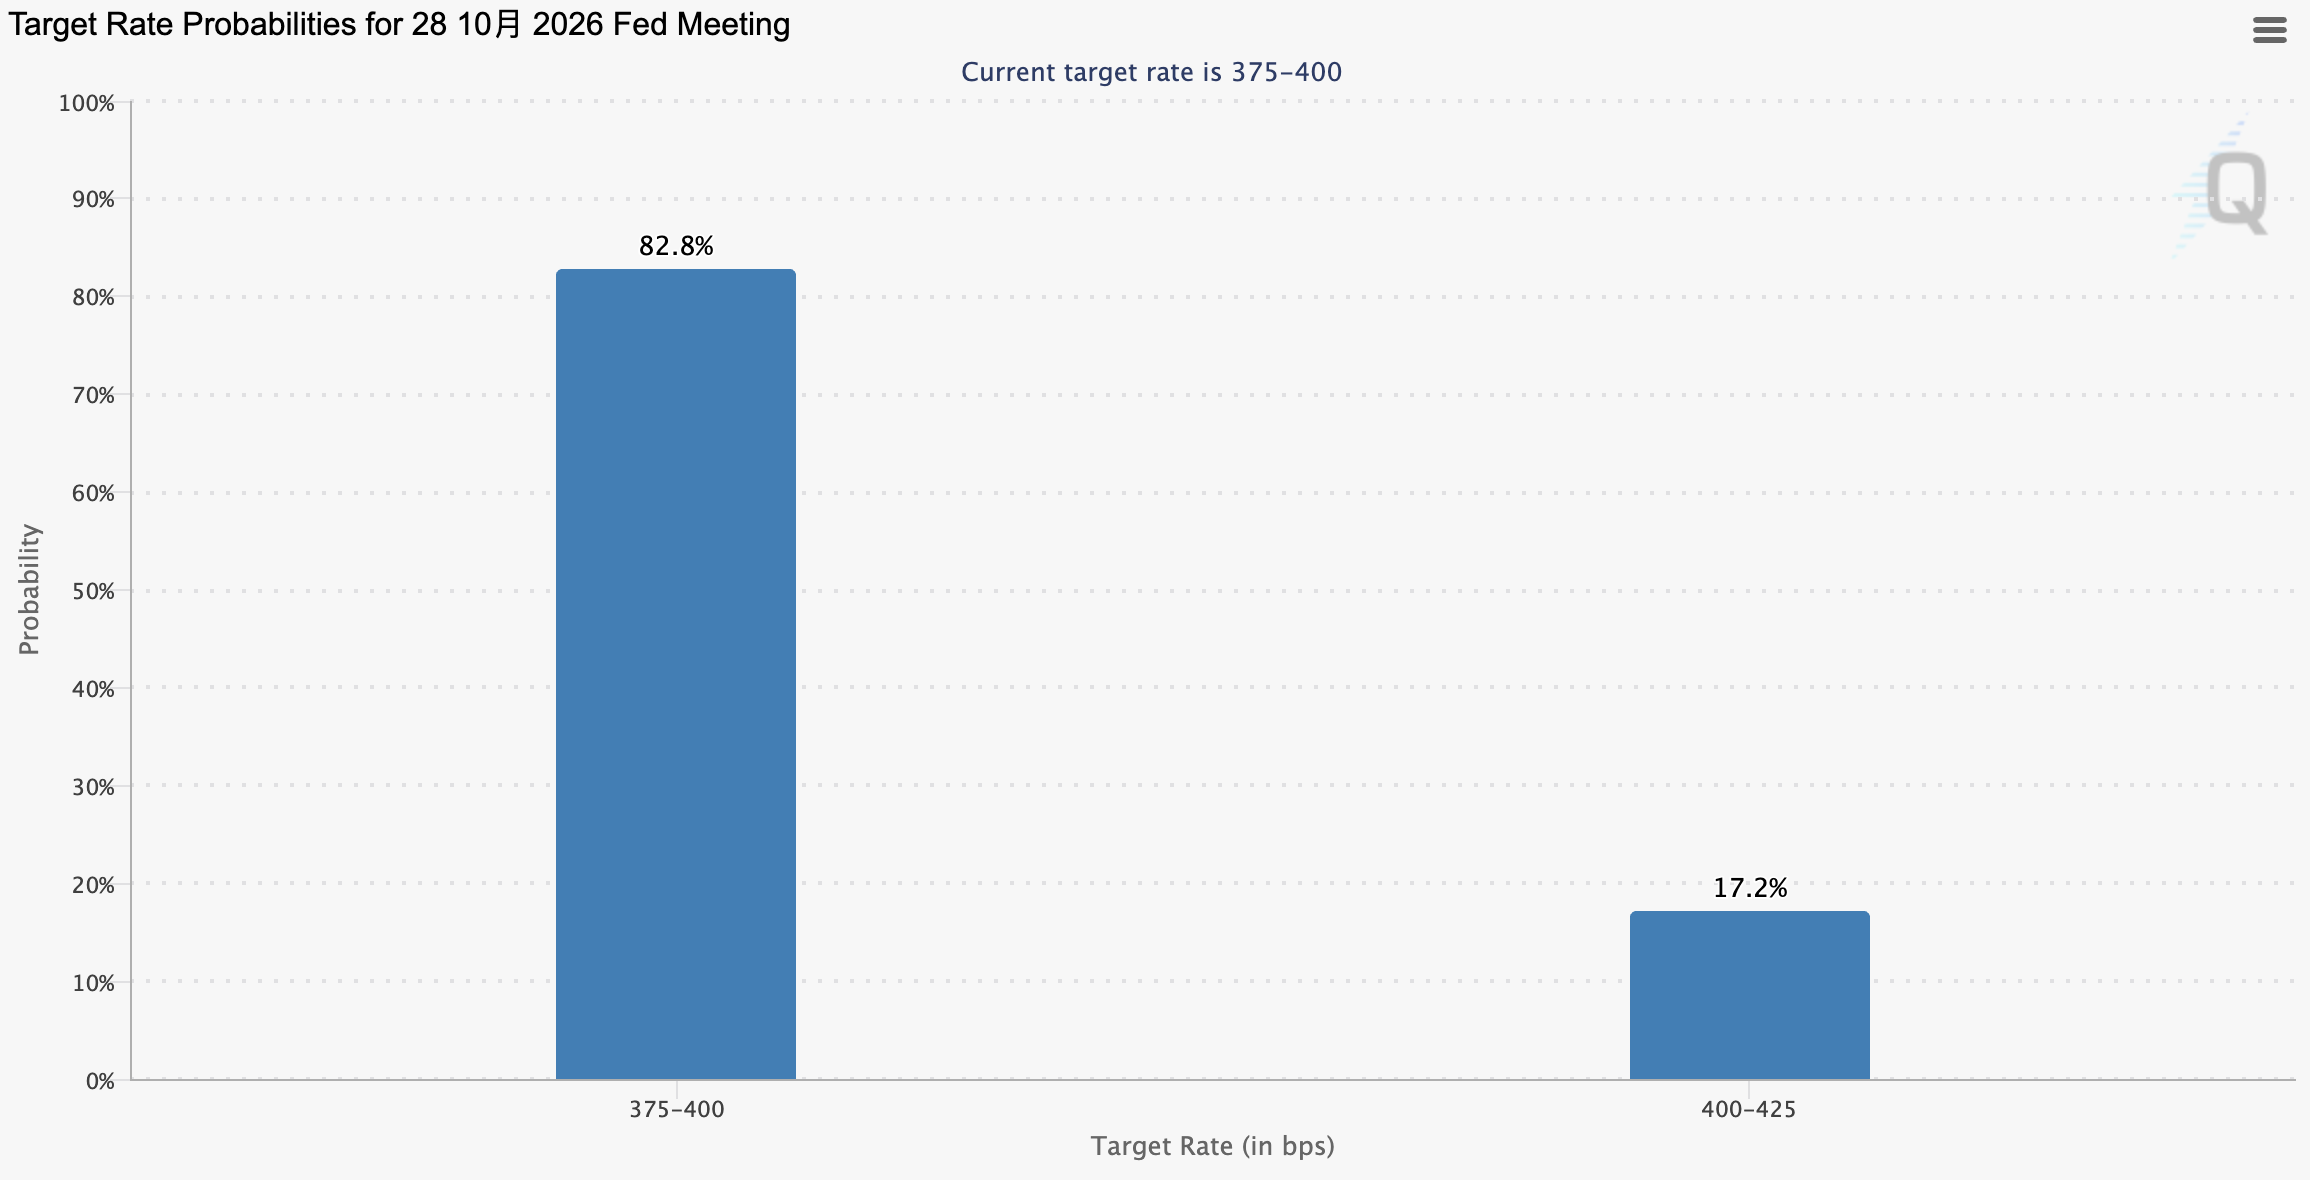
As September employment data came in weaker than expected, and New York Fed President John Williams and Fed Vice Chair Philip Jefferson successively signaled that "there is no rush to hike rates," the market has significantly reduced bets on an October rate hike. According to the CME FedWatch tool, investors are currently pricing in less than a 20% probability of a 25 basis point rate hike at the October 27-28 meeting, down sharply from about 70% in the days following the September decision. The two-year Treasury yield has fallen more than 12 basis points over the past week and is now near 4.78%.
All 19 Officials Backed September Rate Hike, but Reasons for the Hike Differed
At the September meeting, Fed officials were unanimous in their decision to raise rates, but the minutes showed clear disagreements over the specific rationale for the hike.
"Many participants" characterized the rate hike as a risk management move aimed at providing insurance against inflation remaining above the 2% target, especially in scenarios where demand proves stronger than expected or the supply side is hit again. Another group of officials believed that a higher policy rate was necessary in itself to prevent recent shocks such as energy prices from spilling over into broader goods and services prices. A few officials said the rate hike was consistent with their assessment that the neutral rate has risen.
The minutes also showed that "several participants" believed the policy rate before the September hike was "not restrictive or only mildly restrictive." This means that although all officials supported the September rate hike, there was no fully unified judgment that the Fed has entered a new phase requiring sustained and substantial monetary tightening.
Most Officials Expect One More Hike This Year, but No Clear Urgency for October
Regarding the next policy path, the minutes released a hawkish tilt but did not indicate that an October rate hike was a done deal.
The minutes stated that "most participants judged that it might be appropriate to further raise the target range for the federal funds rate before the end of the year," meaning that at the September meeting, most officials still expected at least one more rate hike within the year. However, officials also emphasized that future policy decisions would depend on incoming information.
Nick Timiraos, the journalist known as the "new Fed wire," also highlighted this statement. Fed Vice Chair Philip Jefferson and New York Fed President John Williams recently made public remarks that quickly drove the market to cut bets on an October rate hike, with investors now more inclined to believe the Fed will pause in October and consider a second rate hike of the year in December. The U.S. Consumer Price Index (CPI) data to be released on October 14 could become an important variable affecting this expectation.
Goldman Sachs: December Rate Hike More Likely, but Ending Tightening Also Quite Possible
Goldman Sachs released a commentary after the minutes were published, making a clear judgment on the subsequent policy path.
Goldman Sachs expects the Fed to implement a second rate hike of the year in December, a judgment that comprehensively considered the August core PCE data (which has incorporated methodology adjustments by the U.S. Bureau of Economic Analysis) as well as recent public remarks by Jefferson and Williams.
A Wallstreetcn article wrote that Fed Vice Chair Jefferson said future policy adjustments require careful examination of data trends and that more time may be needed to make a judgment. This, coordinated with New York Fed President Williams' remarks and echoed by Vice Chair for Supervision Bowman, saw three permanent voting members collectively release dovish signals, directly slashing the probability of an October rate hike from 70% to 25%, with the market's expectation center shifting to December.
However, Goldman Sachs also emphasized the possibility of another scenario: the possibility that the FOMC ultimately determines no further tightening is needed is quite substantial. Goldman Sachs pointed out that although the minutes showed "most" participants believed another rate hike before year-end "might be appropriate," the committee will approach each subsequent meeting with an "open mind," and the final decision is highly dependent on the economic data available at that time.
The report said this judgment means that inflation and employment data before the December meeting will be crucial—the data trajectory will not only determine whether there is a rate hike in December but will also largely determine whether this tightening cycle comes to an end.
Inflation Risks Skewed to the Upside, Energy Prices and AI Investment Are Key Variables
Although the Fed believes inflation is gradually cooling, officials still lack sufficient confidence in the pace of disinflation.
The minutes showed that almost all participants believed inflation risks were skewed to the upside, with some officials saying this upward tilt has strengthened in recent months. Recent energy price increases, geopolitical risks, and tariffs could all cause inflation to persist longer than expected.
The AI investment boom has also become an important source of inflation risk discussed at this meeting. Some officials believed that AI is driving investment and improving productivity prospects, but it could also push up inflation through stronger demand, higher input costs, and increased financing needs.
The minutes stated that AI construction is driving business investment, and its scale and pace "continue to exceed expectations." Some officials also noted that core goods price increases remain elevated, and the demand and cost pressures from AI construction could offset some of the disinflationary relief from diminishing tariff effects.
Economy Remains Resilient, Financial Conditions Still Support Growth
The resilience of economic growth was an important backdrop for the Fed's September rate hike decision. The minutes showed that several officials believed the underlying momentum of the U.S. economy had strengthened, consumer spending remained resilient, business investment was supported by AI infrastructure construction, and the overall economy continued to expand at a relatively solid pace. The labor market was seen as near full employment.
Financial conditions also did not impose sufficiently strong constraints on the economy. Although long-term Treasury yields have risen notably recently, many officials believed that financial conditions overall still support economic growth, citing reasons including the substantial stock price gains this year and corporate bond credit spreads remaining narrow.
The minutes showed that 2-year to 10-year Treasury yields rose by about 35 basis points cumulatively over the relevant period, and officials believed that changes in real interest rates were one of the main reasons for the rise in long-term Treasury yields.
Market participants also viewed geopolitical developments, uncertainty over the U.S. Treasury's buyback program, and the large volume of private debt issuance to finance AI infrastructure construction as important factors pushing up term premiums and Treasury yields.
July Joint Yen Intervention Was a Treasury Action, Did Not Use Fed Funds
The joint intervention in the foreign exchange market by the United States and Japan in late July to support the yen was an action taken by the U.S. Treasury Department and did not use the Federal Reserve's own funds.
The minutes showed that the New York Fed "acted solely in its capacity as fiscal agent of the U.S. Treasury," using Treasury funds, and the Fed's System Open Market Account (SOMA) portfolio did not participate in the operation.
The meeting minutes did not disclose the exact timing or scale of the intervention. U.S. Treasury Secretary Bessent said last month that the United States used only a "negligible" amount of funds in the operation and said the move was in the U.S. interest.
The late July operation was the first joint intervention by Tokyo and Washington in nearly 30 years to support the yen. According to Japan's Ministry of Finance data, within the one month through August 26, Japan spent a record 15.4 trillion yen (about $97.5 billion) on foreign exchange intervention. Japanese Finance Minister Katayama Satsuki and Bessent have both signaled that the two countries are willing to intervene again if necessary.