Korean Stocks Circuit Breaker Again! 10th Time This Year, Foreign Capital Withdraws $131 Billion, Asia Dragged Down, Even the Biggest Buyers Have Fled


- Core View: The sharp sell-off in Korean stocks on October 15 was driven primarily by the supply-demand structure of holdings—three pillars of buying demand receded simultaneously: large-scale foreign capital outflow, corporate buybacks winding down, and retail margin financing contracting. Macro headwinds merely amplified the decline rather than causing it.
- Key Elements:
- The KOSPI opened down 5.59%, triggered a circuit breaker in the afternoon halting trading for 20 minutes, and closed at 5,554.22 points; Samsung Electronics fell 9.48%, and SK Hynix dropped 11.06%.
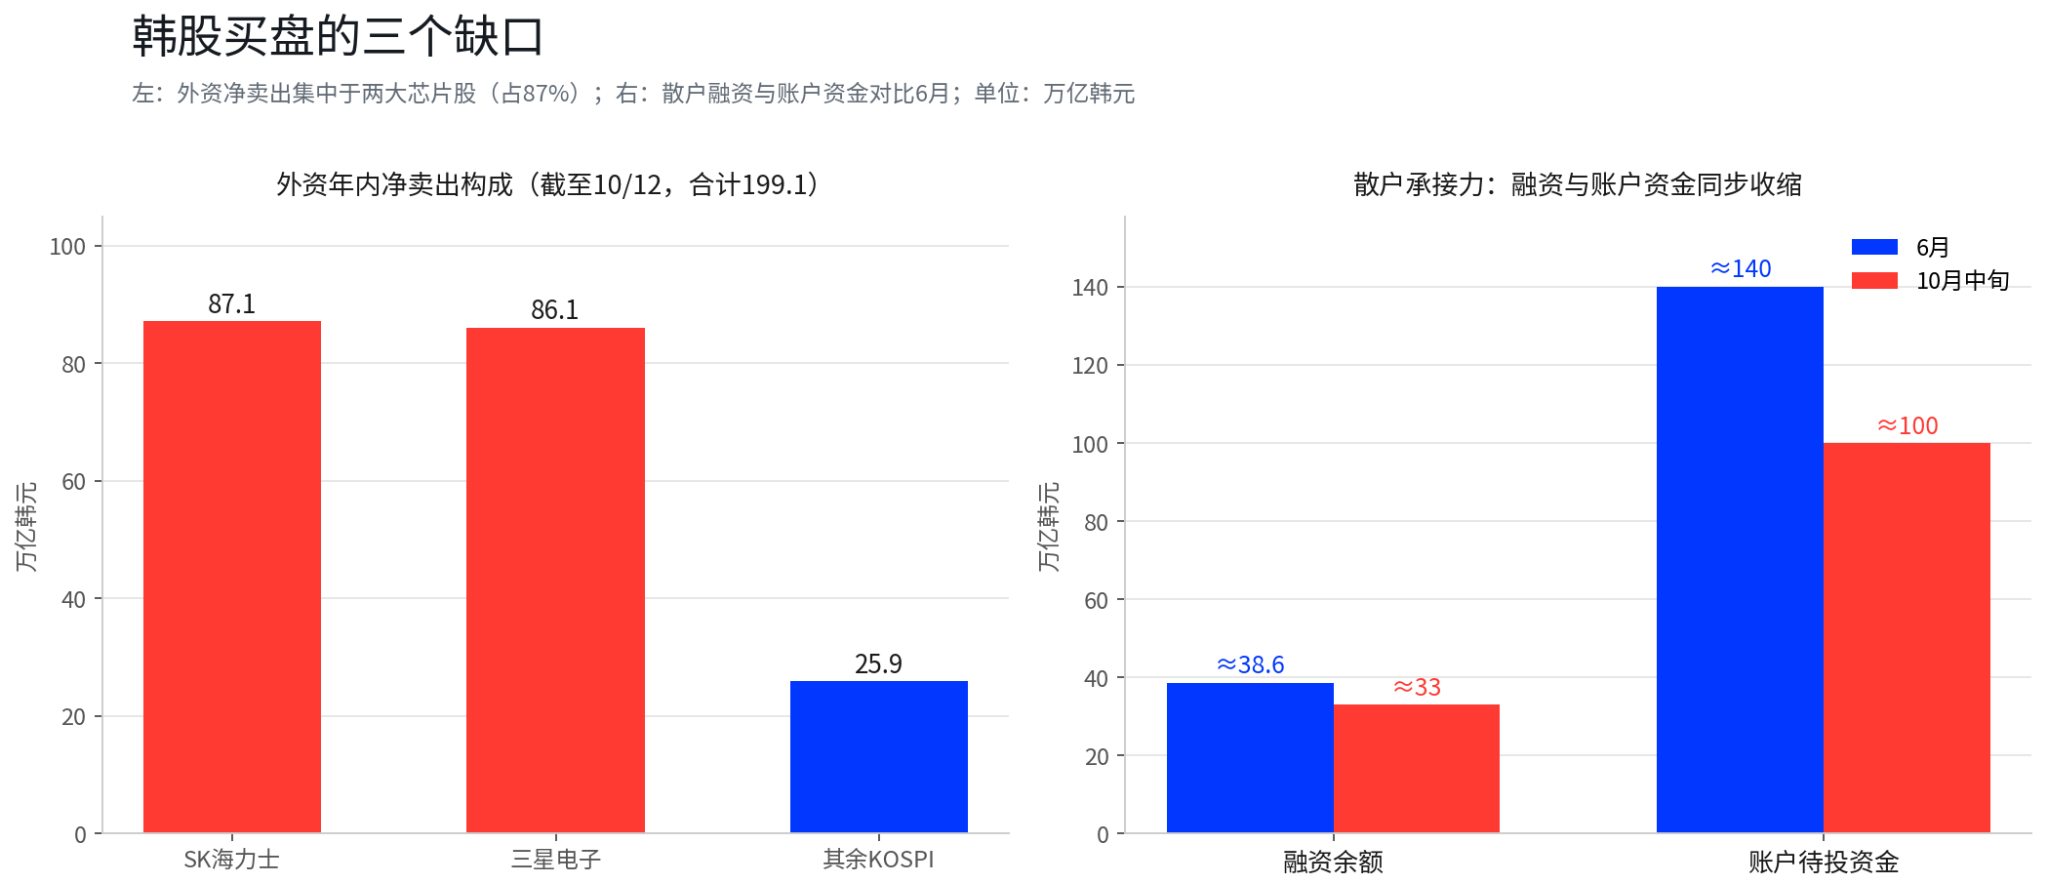
- Foreign capital withdrew approximately $131 billion year-to-date, the highest in Asia, with Samsung and SK Hynix accounting for 87% of net selling combined; the two chip giants' buyback programs totaling about 55 trillion Korean won are nearing completion.
- Retail margin balances fell from a June peak of 38.6 trillion to approximately 33 trillion Korean won, while idle investment funds dropped from 140 trillion to about 100 trillion, leaving a lack of natural buying support.
- Samsung's Q3 operating profit was approximately 107.4 trillion Korean won, up 782.5% year-over-year, a record high, yet the stock price fell instead of rising—the market has shifted to pricing based on cyclical stock logic.
- ChangXin Memory's DRAM market share rose from 4% to 10%, with progress in 4F² architecture R&D and plans to launch DDR5 server modules by the end of 2026, raising questions about technological leadership.
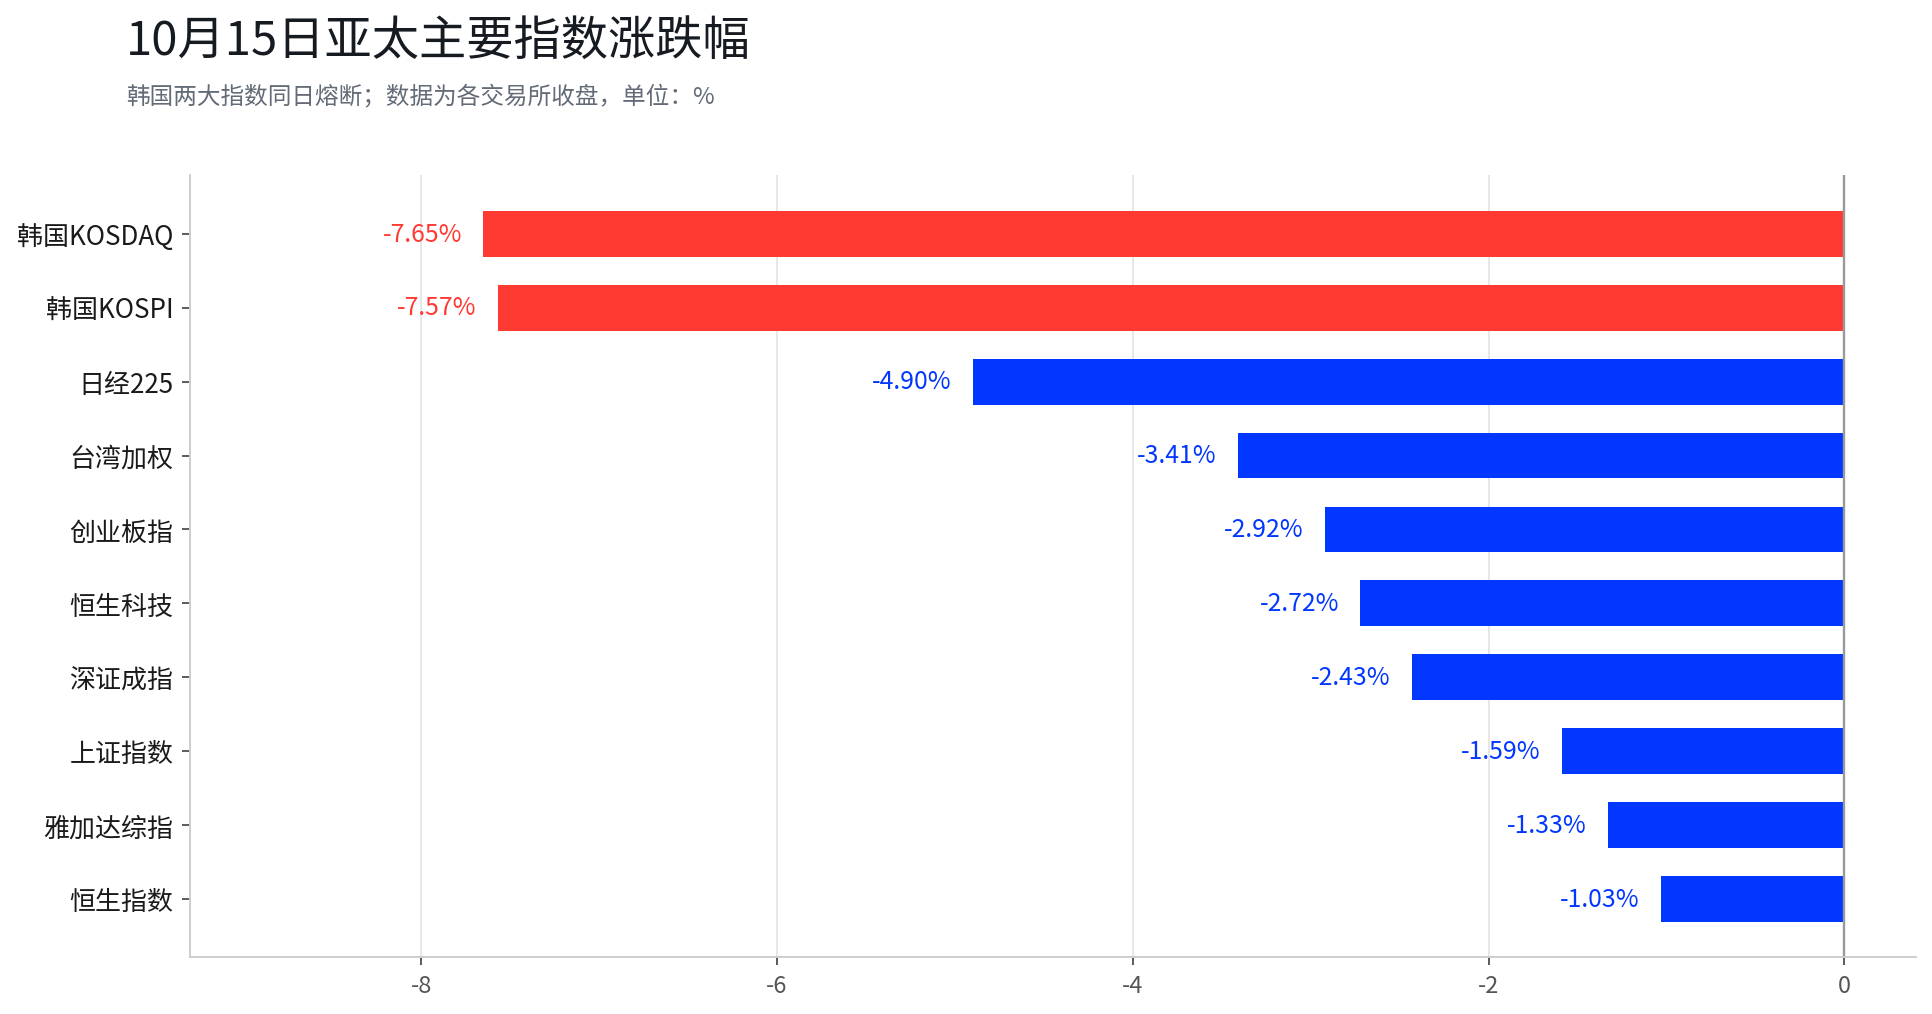
- Asia-Pacific markets came under simultaneous pressure: the Nikkei fell 4.90%, and the Taiwan Weighted Index dropped 3.41%; Hong Kong's Hang Seng Index fell only 1.03%, as its weighting is dominated by platform companies with limited AI hardware exposure.
- Southbound capital recorded net selling of HK$5.08 billion, continuously reducing holdings in SMIC for 13 consecutive days totaling approximately HK$6.92 billion, with capital flowing out of AI hardware and relatively staying in platform companies.
October 15 was dubbed "Black Thursday" by South Korean media. The KOSPI opened down 5.59%, and by the afternoon the decline widened to over 8%, triggering a circuit breaker that halted trading for 20 minutes, closing at 5,554.22 points. What truly merits recording about this day is not the magnitude of the decline, but three sets of simultaneously receding buying figures. Foreign capital withdrew approximately $131 billion during the year, the two major chip giants' buyback of roughly 55 trillion Korean won was nearing its end, and retail margin balances fell from a June peak of 38.6 trillion Korean won to approximately 33 trillion. What fell was the price; what was missing was the counterparty to absorb the selling.

1. The Hardest Hit Were Precisely the Two Heaviest Weighted Stocks
All of the single-day declines landed on weighted stocks. Samsung Electronics closed down 9.48% at 210,000 Korean won, SK Hynix closed down 11.06%, and Samsung Electro-Mechanics closed down 15.36% (market data verified). According to Newsphere Chinese edition citing Korea Exchange data, on that day individuals net bought 1.2886 trillion Korean won and institutions net bought 1.693 trillion Korean won, while foreign investors net sold 3.6241 trillion Korean won, making them the primary force dragging down the index (another statistical basis puts KOSPI market net selling at approximately 2.9 trillion Korean won). During the opening session, programmatic selling first triggered a seller-side Sidecar pause; in the afternoon, both markets successively triggered circuit breakers and were suspended for 20 minutes, and after reopening, they declined again toward the close.
2. Foreign Capital Exit Was an Open Secret; the Buyback Conclusion Was the Real Variable
The buying gap emerged before macro headwinds. According to exchange data compiled by Bloomberg, foreign capital withdrew approximately $131 billion from the South Korean stock market this year, the largest among major Asian markets, with net selling exceeding $6 billion in October alone. Korea Exchange data (cited by Chosun Ilbo, as of October 12) shows that foreign investors accumulated net selling of 199.1 trillion Korean won in the KOSPI during the year, of which Samsung Electronics accounted for 86.06 trillion and SK Hynix 87.14 trillion, totaling 173.2 trillion Korean won, or 87% of total net selling. Foreign ownership of Samsung Electronics fell to approximately 46.4%, the lowest since January 2008, and SK Hynix's ownership ratio also dropped below 50%.
 The buyback timeline is equally clear. Of the two companies' combined buyback plan of approximately 55 trillion Korean won (about $41 billion), Samsung Electronics' approximately 15 trillion Korean won buyback launched in August (for employee performance and special bonuses) was substantially completed by early October. According to researchers at Eugene Investment & Securities, Samsung's buyback ended on October 6. SK Hynix's approximately 40 trillion Korean won buyback aimed at share cancellation was about 80% complete by early October, and daily buying had already slowed. JPMorgan estimates that of approximately $23 billion in buy orders in the South Korean stock market last month, the two companies' buybacks contributed the vast majority. The market's largest marginal buyer was about to leave or had already left.
The retail side was also contracting. Margin loan balances fell from a June peak of 38.6 trillion Korean won to approximately 33 trillion, and brokerage account idle funds dropped from nearly 140 trillion Korean won to approximately 100 trillion (Bloomberg and exchange data, relayed by media). Margin position liquidations and account fund depletion occurred simultaneously, meaning there was a lack of natural absorbing force during the decline.
From a timeline perspective, the acceleration of foreign capital exit and the conclusion of buybacks occurred from September to early October, while the macro triggers for this round of decline (US CPI, rising rate hike expectations) only materialized after October 14. One testable interpretation is that this decline was driven by chip structure, with macro data serving as an amplifier. If subsequent foreign net selling falls back to within 1 trillion Korean won per day and new corporate-level buying emerges, this reading would need revision; if foreign capital maintains its current pace, regulatory statements will struggle to fill the gap left by buybacks.
3. Earnings Are Still Hitting New Highs, but the Market No Longer Prices It as a Growth Stock
Current earnings and stock price movements are diverging unusually. Samsung Electronics' earnings preview released on October 8 showed third-quarter consolidated revenue of approximately 195 trillion Korean won, up 126.6% year-over-year, consolidated operating profit of approximately 107.4 trillion Korean won, up 782.5% year-over-year, with an operating margin of approximately 55%. Quarterly profit exceeded one quadrillion Korean won for the first time, also exceeding the 105.75 trillion expected by brokerages (Yonhap relayed). Since the preview was released, the stock has fallen rather than risen, dropping another 9.48% on October 15.
Two background factors complicate these figures. First, according to public reports, the president of ChangXin Memory Technologies stated at a semiconductor forum in Shanghai on October 10 that R&D on 4F² architecture DRAM had achieved key progress, with plans to launch DDR5 server memory modules by the end of 2026. Counterpoint Research data shows that ChangXin's global DRAM market share rose from 4% in Q2 2025 to 10% in Q2 2026. SK Group Chairman Chey Tae-won subsequently said that China is "catching up at an alarming speed." Second, Bloomberg compilations show that Samsung Electronics and SK Hynix's combined weight in the Korean stock market now exceeds half, with index movements highly dependent on the two companies' memory pricing.
KB Securities analyst Mingyu Kim's assessment is that market doubts about the sustainability of AI investment are pushing investors to price semiconductors according to cyclical stock logic (as reported). Synthesizing this information, the more likely reading is that the market is not questioning current earnings but rather the sustainability of earnings and the shelf life of technological leadership. If fourth-quarter memory contract prices and order data continue to strengthen and ChangXin's mass production timeline is not validated, the "cyclical stock pricing" framework may need to be re-examined.
4. Asia-Pacific Spillover and Hong Kong's Buffer
Across Asia that same night, the decline differed by sevenfold. The Nikkei 225 closed down 4.90% at 64,425.95 points, falling 3,318.34 points, its sixth consecutive trading day of decline (reported as the largest single-day drop since April 2025). The Taiwan Weighted Index fell 3.41% to 46,969.87 points, the sixth-largest closing point drop in history, with TSMC's Taipei shares falling 2.01%. The Jakarta Composite fell 1.33%, and the Shanghai Composite fell 1.59%, briefly breaking below 3,700 points intraday before recovering toward the close, with liquor and brokerage sectors bucking the trend.
Hong Kong stocks provided a comparison group. The Hang Seng Index closed down 1.03% at 24,062.72 points, the Hang Seng Tech Index fell 2.72%, and full-day main board turnover was approximately HK$224.2 billion. The structural reason for the notably smaller decline compared to Korean stocks is that the Korean market's movements are dominated by two memory companies, while Hang Seng Tech's weighted constituents remain platform companies such as Tencent, Alibaba, and Meituan, with limited exposure to AI hardware manufacturing. However, AI hardware names also came under pressure that day, with Lenovo Group plunging 14.54% to close at HK$25.98, the worst-performing blue chip, Hua Hong Semiconductor falling 7.8%, and SMIC dropping 3.96%.
The direction of southbound capital is a more granular observation point. On October 15, southbound capital overall net sold HK$5.08 billion, but net bought Tencent Holdings at HK$852 million and CNOOC at HK$331 million, while net selling YOFC at HK$931 million, Hua Hong Semiconductor at HK$800 million, and SMIC at HK$774 million (Wind data, relayed by Cailian Press and others). SMIC has been net sold for 13 consecutive trading days, accumulating approximately HK$6.92 billion. Capital flowing out of AI hardware manufacturing and relatively staying in platform companies is consistent with Hong Kong stocks' relatively resilient performance. If the pace of southbound reductions in hardware manufacturing slows, the buffer reading for Hong Kong stocks would need to be re-examined.
Based on the overall market action and public information, the more likely reading is that this round of decline in Korean stocks was driven by chip structure, with rising interest rates and cracks in the AI narrative serving as amplifiers. South Korean regulators, after an emergency meeting, believed there was a certain degree of overreaction in the market, with fundamental indicators (foreign exchange reserves, current account, financial institution soundness) broadly stable, but what the market lacks is buyers, not reasons. For the rebound in early trading on October 16 to continue, foreign net selling needs to narrow or new corporate actions need to emerge; otherwise, pricing pressure from the buyback vacuum may persist.
BIT supports real-time quotes and direct trading for Hong Kong and US stocks, with stablecoin deposits credited 7×24 in seconds. During periods of heightened market volatility, manage position holding and leverage levels. Please consider your own risk tolerance.
Data Notes
- Korean stock market action and circuit breakers: Korea Exchange data, 2026/10/15, relayed by Sedaily, Newsphere, and others.
- Individual stock changes: Closing changes for Samsung Electronics, SK Hynix, and Samsung Electro-Mechanics verified against market data, 2026/10/15.
- Foreign capital flows and buybacks: Bloomberg compilation ($131 billion), Korea Exchange (199.1 trillion Korean won) relayed by Financial World and others, as of 2026/10/12. Buyback progress from Eugene Investment & Securities and exchange data relayed by media.
- Samsung earnings preview: Company announcement, 2026/10/8, relayed by Yonhap.
- Asia-Pacific market action and Hong Kong capital flows: Various exchange closes, 2026/10/15. Southbound capital from Wind data, relayed by Cailian Press and others.
- KOSPI200 trend: Market interface daily line (KOSPI Composite Index has no interface data; KOSPI200 used as reference), as of early trading 2026/10/16.
Disclaimer:
This content is for general informational and market commentary purposes only, compiled based on public information available as of the time stated herein. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other persons cited herein represent only the views of the relevant third parties at specific times and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, and should not be relied upon as the basis for any investment decision. Financial markets involve risk; securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Margin trading amplifies losses, and losses may exceed principal. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when needed. BIT's Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted jurisdictions.