Fleeing in a Panic! Hedge Funds Dump Two Years of Net Buying in a Single Week, Goldman Sachs Warns: Deleveraging May Have Only Just Begun


- Key Takeaway: Hedge funds' AI positioning accumulated over the past two years was completely wiped out within five trading sessions, with cumulative net buying of global AI stocks falling to zero — yet positioning remains at historically elevated levels, suggesting deleveraging may have only just begun.
- Key Points:
- From October 8 to 14, hedge funds net sold AI stocks for five consecutive days, fully reversing all cumulative net buying since the start of 2025, with long selling to short selling at roughly 3.5:1.
- South Korea's KOSPI plunged into bear market territory and triggered a circuit breaker, Taiwan saw a record single-day foreign net outflow of approximately $9.3 billion, and TMT long/short funds lost 2.7% in a single day.
- Global AI stocks' net allocation stands at 26.1%, still in the 83rd percentile on a three-year basis; the long/short ratio fell from a peak of 4.34 to 3.27, in the 64th percentile on a three-year basis.
- Goldman Sachs' gross leverage is at 310.3%, in the 94th percentile on a five-year basis and near a five-year high, with the actual sellable amount far exceeding net exposure.
- The selloff reflects a broad shift to defense, with 8 of 11 US sectors seeing net selling, and capital rotating into healthcare and consumer staples.
- Global systematic long/short funds emerged as the sole winners, leading all strategies with a year-to-date return of 21.7%.
- Goldman Sachs judges that AI net exposure and gross leverage remain at historically elevated levels, with record foreign outflows from Asia, making deleveraging closer to the starting point than the end.
Original Author: Zhao Ying
Original Source: Wallstreetcn
AI positions that hedge funds spent nearly two years accumulating were completely wiped out in five trading sessions. The intensity and speed of this selloff are fueling concerns about a larger-scale deleveraging.
According to a latest report by Vincent Lin, head of Goldman Sachs Prime Brokerage, hedge funds net sold global AI stocks for five consecutive trading days from October 8 to 14, and all cumulative net buying since the start of 2025 has been completely reversed—in other words, every single net purchase over the past nearly two years was erased within a week.
Meanwhile, Goldman Sachs Prime Book shows that global equities saw "significant net selling," with the single-day net selling magnitude reaching -2.1 standard deviations on a one-year lookback basis. North America and emerging Asia led the declines, with South Korea and Taiwan becoming the most concentrated markets for net selling.
The direct impact of this selloff has already manifested across multiple markets. South Korea's KOSPI plunged into a bear market, Seoul triggered a circuit breaker, Taiwan recorded a historic single-day foreign net outflow of approximately $9.3 billion, and several Asian central banks were forced to intervene in currency markets. TMT directional long/short funds lost 2.7% in a single day, an extreme move of -2.6 standard deviations, with month-to-date October losses widening to 4.5%.
Two Years of Net Buying, Erased in Five Days
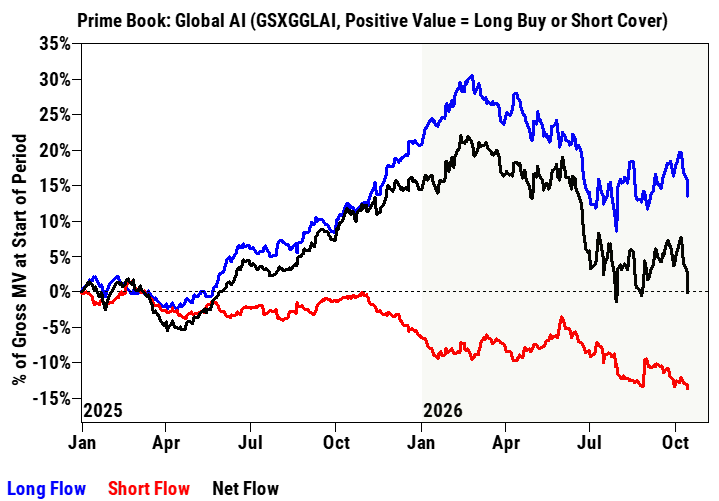
The scale of this AI stock selloff ranks second only to the crash in July of this year in Goldman Sachs' historical data. According to Goldman Sachs Prime data, the single-day net selling of global AI stocks (GSXGGLAI constituents) was the second-largest in the past year, with the ratio of long selling to short selling at approximately 3.5 to 1—meaning this selloff was primarily driven by active long position reduction rather than increased short selling.
Looking at the flow chart, hedge funds' net flow on the AI list (black line) has fallen back to the starting point of early 2025. Long flow (blue line) has continued to decline from its peak around February to March of this year, while short flow (red line) has remained near a low of approximately -13% throughout the entire period. Goldman Sachs' chart clearly illustrates this "round trip": the entire 2025 to 2026 net buying cycle was completely reversed within a week, while shorts continued to add positions during the decline.
Just last week, Goldman Sachs noted that hedge funds' net exposure to Mag7 in its Prime Book was close to 22% of total US exposure, a historic high. Five days later, the same group of funds collectively rushed for the exits.
Positions Still Heavy, Deleveraging Far From Over
Despite the massive selling intensity this week, from a longer-term perspective, AI positions remain elevated, and the room for deleveraging cannot be ignored.
Goldman Sachs data shows that global AI stocks' net allocation as a percentage of global single-stock net market value currently stands at 26.1%, down from a peak of 31.7% in early June, placing it in the 49th percentile over the past year—but still in the 83rd percentile on a three-year basis. The long/short ratio of AI portfolios has fallen from a June peak of 4.34 to 3.27, placing it in the 7th percentile over the past year, but still in the 64th percentile on a three-year basis.
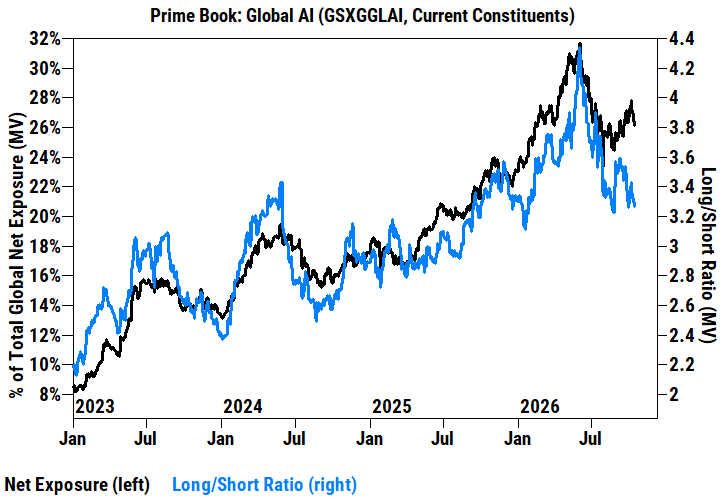
In short, one-year data suggests positions have been relatively cleared out, but three-year data indicates that hedge funds as a whole remain significantly overweight. Rachel Hu from Goldman Sachs' Asia team noted that trading feedback from the Taiwan market suggests the "capitulation" level of this selloff was less than in July, implying there may still be more selling pressure ahead.
JPMorgan's market intelligence TPM positioning indicator currently sits in "neutral" territory at around the 46th percentile, far above the 19th percentile at the late-July low, meaning there is still room for "further deleveraging" before key tech catalysts arrive.
Defensive Shift: Sell Tech, Buy Toothpaste
This selloff was not limited to the AI sector but reflected a broad defensive shift. Goldman Sachs Prime Book shows that 8 of 11 US sectors saw net selling, with information technology and industrials leading the declines. Within information technology, all sub-sectors—software, semiconductors and semiconductor equipment, and IT services—were net sold.
Meanwhile, hedge fund buying was concentrated in healthcare and consumer staples, which Goldman Sachs characterized as a "marginal strengthening of defensive posture." On Thursday morning, healthcare and consumer staples each rose more than 2%, supporting the Dow, while the Nasdaq slid to a near one-month low. CoreWeave fell another 8.5%, and the Philadelphia Semiconductor Index declined for a seventh consecutive day, with approximately $2 trillion in related market value evaporating.
Amid this collective bloodletting by human fund managers, quantitative funds emerged as the only winners. Global systematic long/short funds rose 0.5% on the day, with October month-to-date gains of 1.9% and year-to-date returns of 21.7%, leading all strategies.
Fragile Leverage Structure, Violent Deleveraging Risk Remains
Leverage data reveals why this selloff was so severe. Goldman Sachs Prime Book's overall gross leverage declined only slightly by 0.4 percentage points to 310.3%, placing it in the 72nd, 91st, and 94th percentiles on one-year, three-year, and five-year bases respectively—near a five-year high. Net leverage fell 1.5 percentage points to 73.3%, down 4.3 percentage points month-to-date in October, placing it in the 6th percentile over the past year.
Goldman Sachs' logic is that for a fund with 310% gross leverage and 73% net leverage, the actual sellable scale far exceeds what net exposure suggests. When crowded longs (AI) and crowded shorts move in opposite directions simultaneously, deleveraging becomes the only way out, and the exit is extremely narrow—everyone rushes toward the same door at once. This is precisely a repeat of the late-July crash.
Rich Privorotsky from Goldman Sachs' Delta-One business summed up the current predicament in an overnight report: "In hindsight, the pain trade was long AI, short bonds. Now we're seeing both ends unwinding simultaneously... The market is discovering that compute demand can grow exponentially, but the capital that can finance it cannot."
Goldman Sachs: This Looks More Like the Beginning Than the End
The core debate in the current market is: is this a buying opportunity, or the prelude to a larger-scale deleveraging?
JPMorgan leans toward the former, believing it's a buying opportunity on dips. Goldman Sachs' flow trading desk had spent the previous two days observing positive year-end technical signals. But Goldman Sachs' overall assessment is more cautious: AI net exposure remains in the 83rd percentile on a three-year basis, gross leverage sits in the 94th percentile on a five-year basis, and Asian foreign capital is withdrawing at record scale—these signals collectively point to this deleveraging round being closer to the starting point than the end.
Hedge funds have already sold all AI positions bought since 2025. But positions accumulated in 2023 and 2024 remain fully on the books.