CPI and the Earnings Reports of Five Major Investment Banks Face Back-to-Back Tests This Week; October Rate Hike Probability Drops to 20%, December Nears 90%


- Core View: Ahead of the Fed's October policy meeting, the market is pricing a contradictory rate path—October is likely to see rates held steady, while the probability of a December hike is about 87.6%. In essence, this is a pace adjustment rather than a cycle turn, with core CPI and bank earnings serving as the key tests this week.
- Key Elements:
- September nonfarm payrolls rose by only 29,000, far below the expected 90,000, while July-August were revised down by a combined 60,000 and the unemployment rate rose to 4.2%; the weakening in employment only pushed down short-end rates.
- The 10-year U.S. Treasury yield closed near 5.33%, rebounding more than 10 basis points after a brief dip on the day of the nonfarm payrolls release, with the long-end pricing logic clearly diverging from the short end.
- Internal Fed disagreement centers on the pace of hikes: Hammack advocates rapid adjustment, Waller leans toward waiting until December, and the September minutes show most officials expect one more hike this year.
- September headline CPI is expected to rise to 3.7% year over year from 3.4%, with the core month-over-month consensus at about 0.2%; the direction of any deviation in the core reading will determine the path of October probabilities.
- TSMC's Q3 net profit is expected to be about NT$746.3 billion, up about 65% year over year, with the earnings call focused on CoWoS capacity expansion, the N2 process timeline, and capital expenditure commentary.
- The focus of the five major investment banks' earnings has shifted from profit growth to credit costs, deposit competition, and asset quality, making this the first window to test the depth of high-rate transmission.
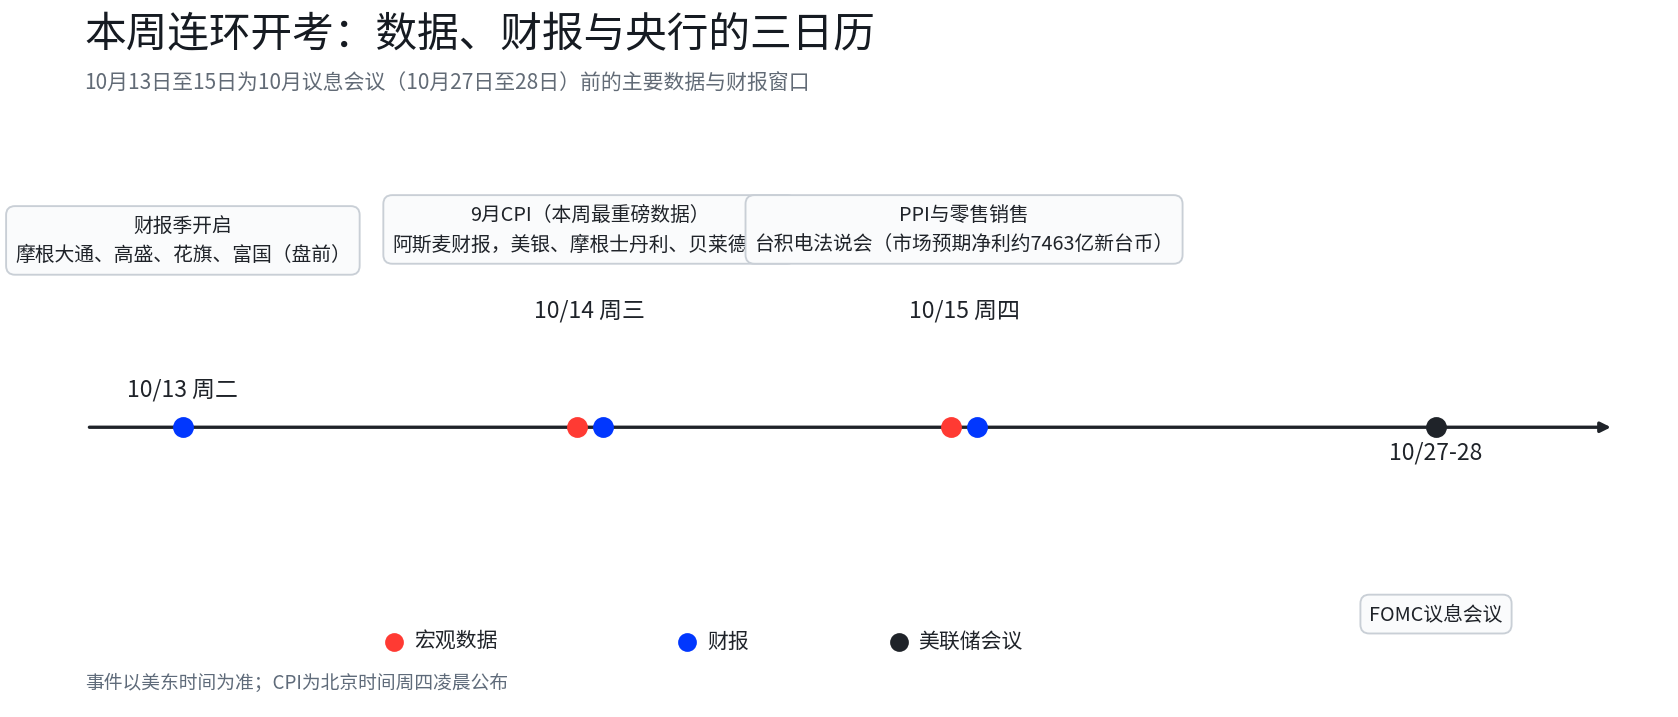
This week is the most important data and earnings window before the Federal Reserve's October 27-28 policy meeting. On Wednesday (October 14), the U.S. September CPI will be released, and on the same day ASML will report its Q3 results. JPMorgan, Goldman Sachs, Citigroup, and Wells Fargo already reported before the bell on Tuesday, while Bank of America, Morgan Stanley, and BlackRock follow on Wednesday. TSMC holds its earnings call on Thursday, and Thursday also brings PPI and retail sales. Within a single week, both the denominator of the rate path and the numerator of earnings growth will be put to the test. On the market side, the 10-year Treasury yield closed near 5.33% last Friday, having briefly dipped and then rebounded by more than 10 basis points on the day of the nonfarm payrolls release, and touched an intraday high of 5.357% on October 8. Monday was Columbus Day, with the U.S. bond market closed. Before the dense wave of data lands, the market has given two seemingly contradictory answers about the same Fed: hold steady in October, tighten as usual in December. This article breaks down that contradiction.
1. The Probability Curve's Rollercoaster, Twice in One Month
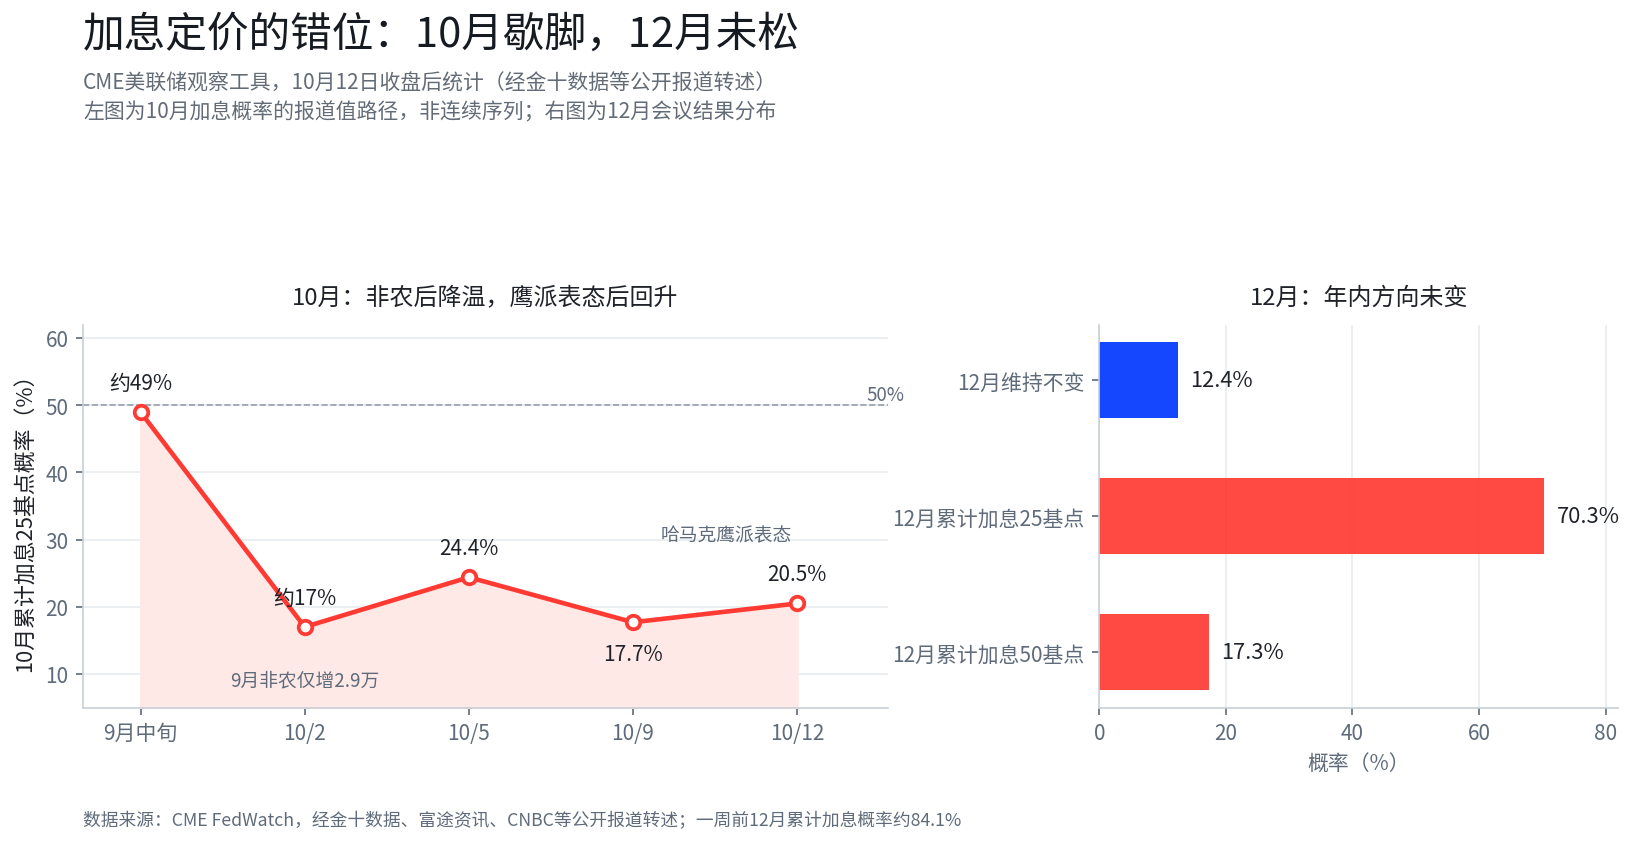
Laying out the timeline of October rate-hike probability is more intuitive than any words. A month ago, the market priced only about 51% odds of the Fed holding steady in October, with a hike nearly a coin flip. On October 2 (Friday), the September nonfarm payrolls were released, showing only 29,000 new jobs, less than one-third of the expected 90,000. August data was revised down from 162,000 to 133,000, and July was revised down to negative 10,000, for a combined two-month downward revision of 60,000, while the unemployment rate rose to 4.2%. That day, the October rate-hike probability fell from about 22% to 17%. Over the following week, the probability hovered between 17.7% and 24.4%, rebounding to 20.5% after Hammack's remarks on Monday and briefly approaching 22% intraday.
 The details of the nonfarm report were weaker than the headline. Over the past three months, job growth has averaged only 51,000 per month, the breadth of industries adding jobs fell from 57.6% in August to 49.0%, an 11-month low, and government employment shrank by 17,000. According to economists' estimates, because retirements and tighter immigration have reduced labor supply, the U.S. needs roughly 50,000 new jobs per month just to maintain balance, so 29,000, though weak, is not far from the breakeven line. This explains why the weak jobs report only pushed down the short end.
The long end is a different matter. On the day of the nonfarm release, the two-year yield fell 10 basis points in a single day to 4.69%, while the 10-year yield, after a brief dip, rebounded by more than 10 basis points to 5.30%. The bond market gave the jobs report only half a day of deference. Based on these readings, what the market is truly worried about is no longer whether the next meeting will bring a hike, but the direction of long-end inflation compensation under an energy shock, something Wednesday's CPI will test more directly.
2. The Focus of Official Disagreement Is Pace, Not Direction
Voices within the Federal Reserve were amplified this week. Cleveland Fed President Hammack said Monday at the National Association for Business Economics annual meeting that a restrictive monetary policy stance is appropriate, and that it is better to adjust modestly and relatively quickly than to wait for risks to accumulate and then pay a greater cost for correction. She added in an interview that demand for electricity and components from AI data center construction has begun to affect a broader range of industries, that some companies plan price increases exceeding the rise in input costs, and that the risk of entrenched inflation psychology is rising. It is worth noting that she did not explicitly say she supports another hike in October, only that she will attend the October 27-28 meeting with an open mind.
Fed Governor Waller's remarks on October 8 offer a contrast. He believes further hikes may still be needed if data meets expectations, but that they need not come at consecutive meetings, leaving more action for the December 8-9 meeting. The September meeting minutes (released October 7) show that most officials expect one more hike this year, and that meeting already raised the policy rate by 25 basis points to 3.75%-4.00%, the first hike since July 2023. According to reports, Goldman Sachs maintained its call for another 25 basis point hike in December after Waller's speech.
Putting these three voices at one table, the disagreement centers on one word: speed. Hammack worries about the cost of waiting, Waller and the minutes allow room to wait, and the market has priced this debate with an approximately 87.6% cumulative probability of a hike by December. Combining market pricing and officials' wording, the more likely interpretation is that holding steady in October is a pacing adjustment rather than a turn in the hiking cycle. If Wednesday's core CPI comes in clearly below expectations, or subsequent employment data continues to deteriorate, that interpretation will need to be revised.
3. CPI Preview: Headline Almost Certain to Accelerate, Core Is the Real Test
Wednesday's CPI is the week's heaviest data point. Market consensus expects September headline CPI to rise from 3.4% to 3.7% year-over-year, with a month-over-month increase of perhaps 0.5% to 0.6%, mainly reflecting higher gasoline and energy prices. A high headline reading is already within market expectations; the real fork lies in the core. Consensus for core CPI month-over-month is about 0.2%, while Barclays and Morgan Stanley reportedly forecast about 0.24%, citing a partial pullback in wireless communication services price gains; core year-over-year is expected between 2.4% and 2.5%.
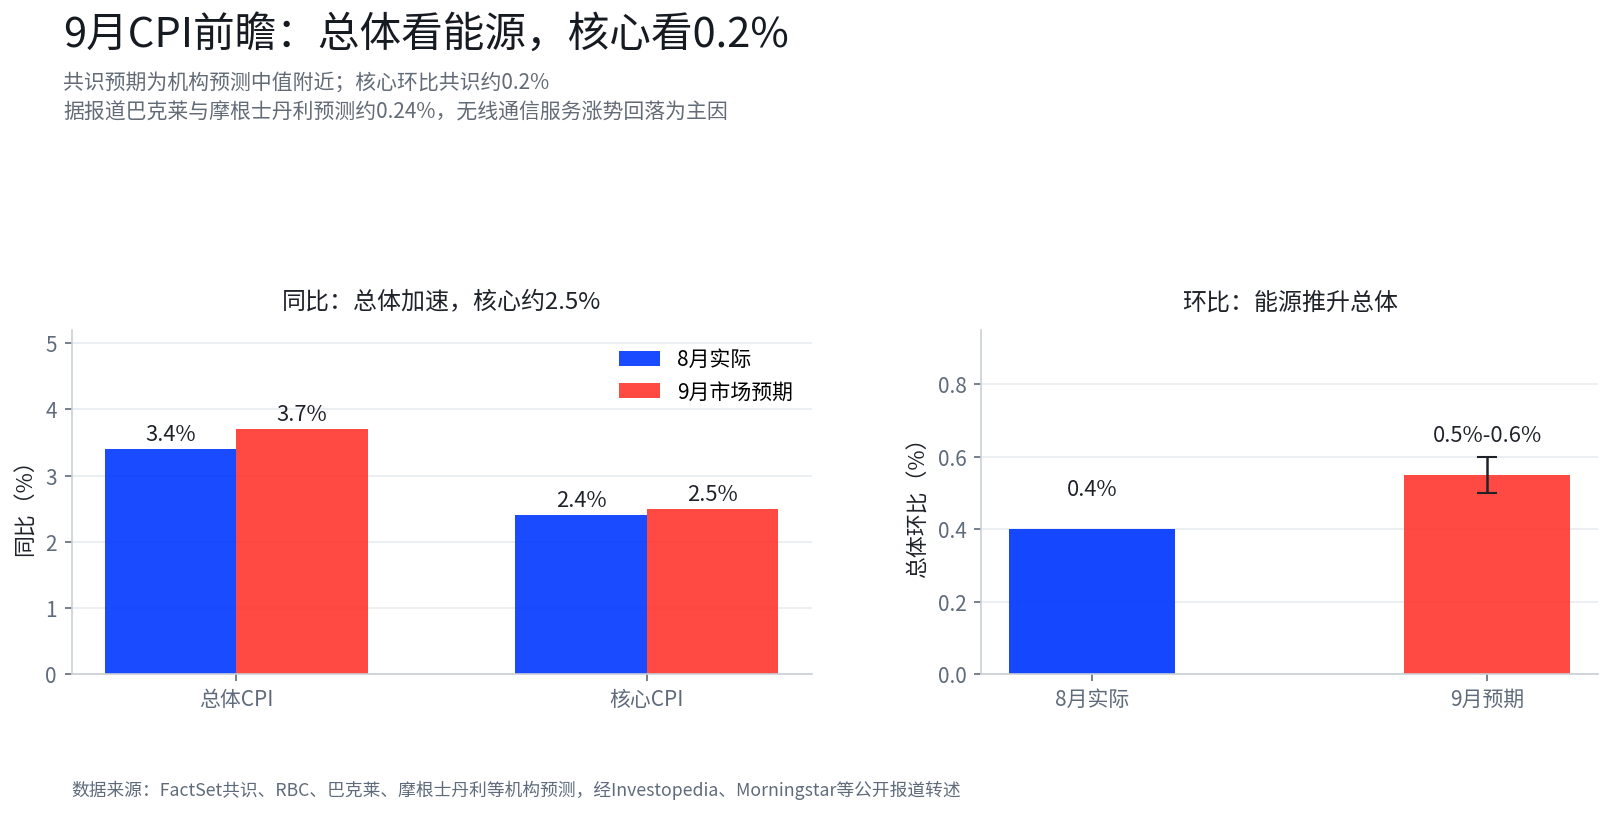 Two directions correspond to two market outcomes. If core meets or falls below expectations, the October rate-hike probability may be revised further down, long-end yields and the dollar may fall in tandem, and risk assets may get a breather. If core unexpectedly rebounds, confirming the pass-through from energy to core, the roughly 87.6% December hike probability may continue to rise, long-end yields may approach the 5.357% high again, and highly valued assets will face greater pressure. Bloomberg's earlier analytical framework is worth referencing: this round of inflation acceleration mainly stems from localized items such as energy, differing from the broad-based price increases of 2022, which is also the premise that allows the Fed to remain patient. That premise is itself fragile: if oil prices continue to spiral out of control, localized hotspots could evolve into broad-based pressure, at which point the "pacing adjustment" narrative would face renewed scrutiny.
4. Two Kinds of Tests in Earnings Season
The test for banks is the depth of high-rate transmission. JPMorgan, Goldman Sachs, Citigroup, and Wells Fargo reported before the bell on Tuesday, with Bank of America, Morgan Stanley, and BlackRock following on Wednesday. With the 10-year Treasury yield near 5.3% and the policy rate at 3.75%-4.00%, the market's focus has shifted from profit growth to credit demand, deposit costs, capital markets business, and asset quality. The credit cost commentary from the five major investment banks may become the first window for judging whether high rates are beginning to materially affect businesses and consumers.
The test for chips is the sustainability of AI orders. ASML reports Q3 results on Wednesday, having previously guided revenue of 11 billion to 12 billion euros. TSMC's Thursday earnings call will draw even more attention. According to Reuters, the LSEG SmartEstimate of 16 analysts expects third-quarter net profit of about NT$746.3 billion (about $23.4 billion), up about 65% year-over-year, potentially marking a sixth consecutive quarter of record single-quarter results. TSMC previously reported third-quarter revenue of about NT$1.49 trillion (about $46.7 billion), up about 50.9% year-over-year, with September revenue up 54.6% year-over-year. The earnings call's highlights may center on CoWoS advanced packaging capacity expansion, the N2 process timeline, and 2027 capital expenditure commentary.
It should be noted that before the chip earnings land, the secondary market has already priced in a round. On Monday, the Philadelphia Semiconductor Index closed down 2.67%, with optical communications and memory leading the decline; related transmission and liquidity discussions can be found in the same day's AI hardware piece and will not be expanded here.
Next Steps
Wednesday's core CPI month-over-month reading is the week's first checkpoint; the direction of any deviation from 0.2% may determine whether the October probability is revised further down or rebounds. Wednesday evening's bank earnings and Thursday's TSMC earnings call provide a second set of signals: the former for credit costs and deposit competition, the latter for CoWoS expansion and capital expenditure commentary. Further out, the relative changes in October and December probabilities in the FedWatch tool are worth continued tracking; if the October probability rises back above 30%, the "pacing adjustment" interpretation may need to be reassessed. Before the data lands, positions in either direction may be simultaneously exposed to both upside inflation surprises and deteriorating employment risks, and how much repricing has already been priced in by the market remains to be seen.
Data Notes
- Rate-hike probabilities: CME "FedWatch," compiled after the October 12 close, as relayed by Jinshi Data and others.
- Nonfarm payrolls and Treasuries: September nonfarm data relayed from public reports; the 10-year Treasury yield of 5.33% is the October 9 close (market data interface), with the U.S. bond market closed Monday.
- CPI expectations: FactSet, RBC consensus; Barclays and Morgan Stanley forecast about 0.24%, relayed from reports.
- Official remarks and September meeting minutes: relayed from public reports.
- Earnings: calendar verified via Futu and Morningstar; TSMC forecast relayed from Reuters' LSEG SmartEstimate.
Disclaimer:
This content is provided for general information and market commentary purposes only, based on public materials available as of the time stated in the article, and relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other persons cited herein represent only the views of the relevant third parties at specific times and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it serve as the basis for any investment decision. Financial markets involve risk, securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when needed. BIT's Hong Kong stock trading services are not provided to residents of Hong Kong or users in other restricted jurisdictions.