September CPI comes out tonight, core 0.2% or 0.3% — the final test before the Fed's October decision


- Core view: Tonight's CPI report is the last inflation data point before the FOMC meeting. Whether core CPI comes in at 0.2% or 0.3% month-over-month will determine whether the Fed holds steady in October. The headline inflation jump has already been priced in by consensus on energy prices — the core trajectory is the key variable that will divide the market.
- Key factors:
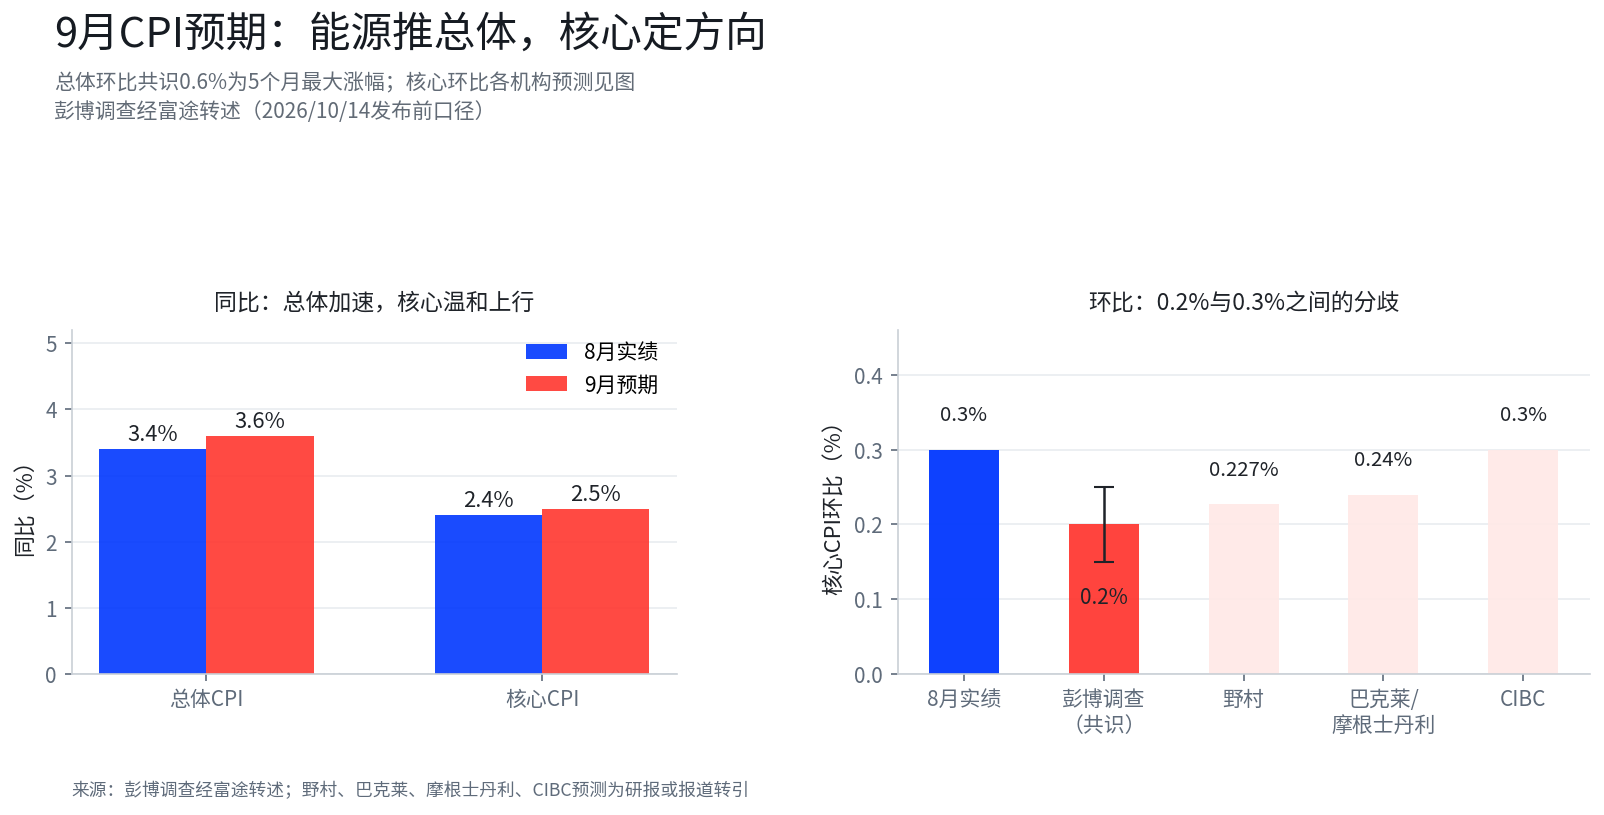
- September gasoline retail prices averaged a record $4.33 per gallon, with headline CPI potentially rising 0.6% month-over-month and climbing to about 3.6% year-over-year — but this is not the core issue.
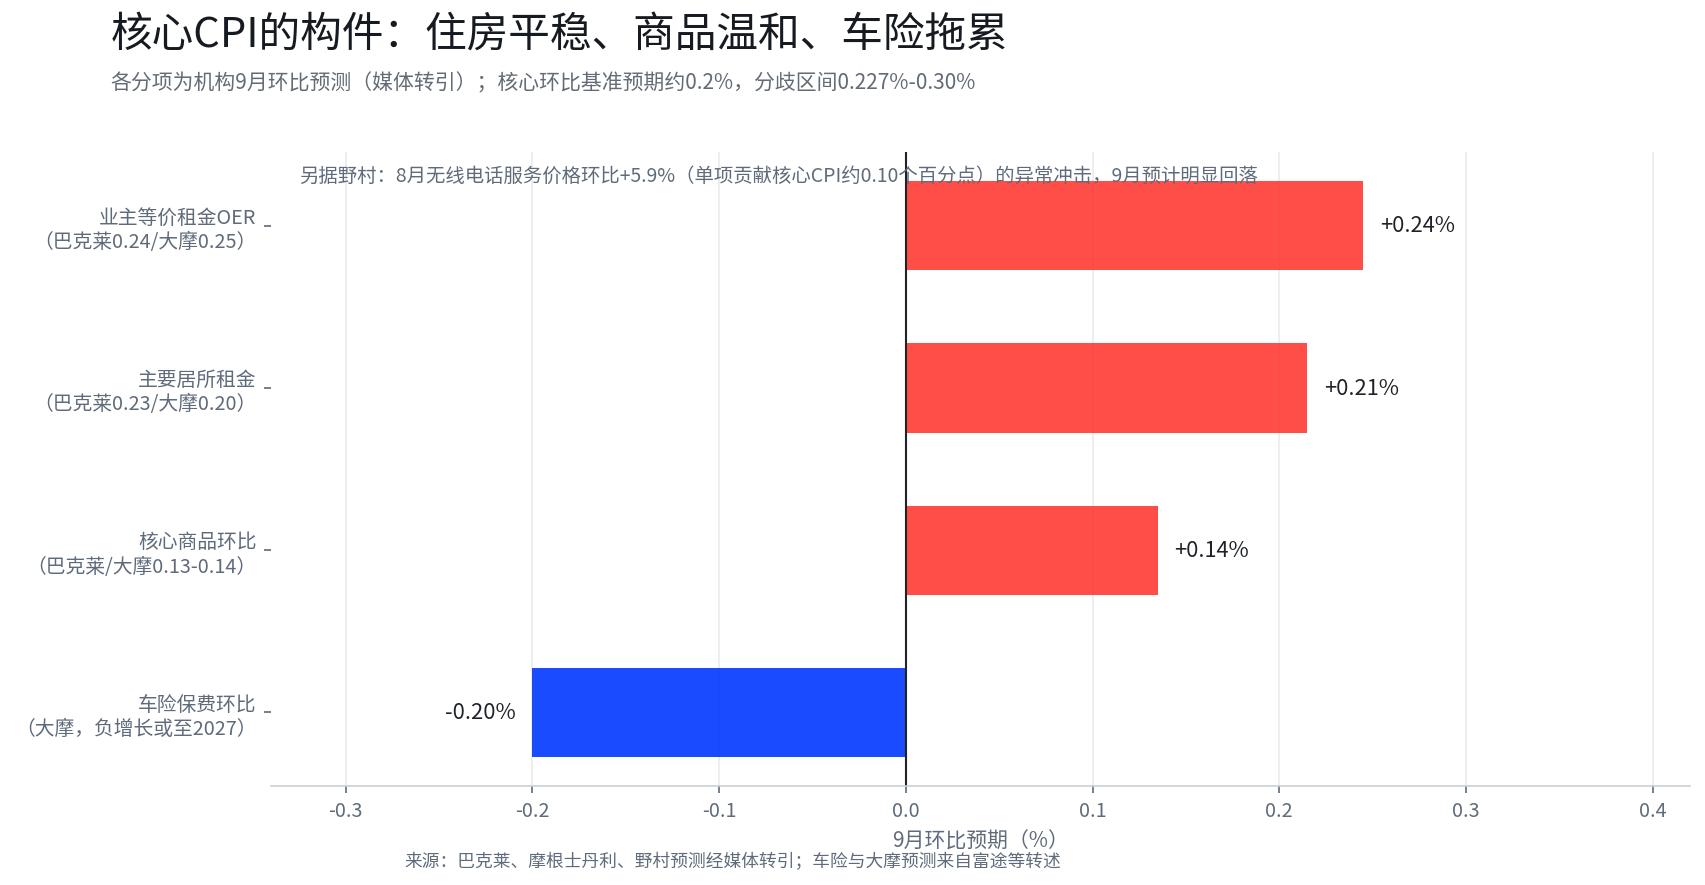
- The baseline expectation for core CPI is 0.2%, supported by a technical decline in wireless phone services, stabilizing housing inflation (OER around 0.24%-0.25%), and core goods holding at 0.13%-0.14%.
- Counterarguments include airfare, hotels, auto parts, and diesel pass-through risks; CIBC expects core at 0.3% and believes a rate hike could come as soon as this month.
- CME FedWatch shows roughly a 77% probability of rates staying unchanged in October, up from about 51% a month ago, with the market having priced in three cumulative rate hikes including September.
- The September minutes show all 19 officials unanimously supported raising rates to 3.75%-4.00%, with most believing further tightening may be needed this year, and for the first time listing the surge in AI investment as a cause of inflation.
- Williams' remarks that one more rate hike this year would be appropriate and that no tightening is needed in 2027 reflect that internal Fed divisions are centered on pace rather than direction.
- Tonight, the focus should be on where core CPI lands relative to 0.24%, the month-over-month housing component, and the trajectory of core services prices.
Tonight at 20:30, the market will receive the last inflation report before the FOMC meeting on October 27-28. What the market needs to guard against is not a jump in headline CPI — energy prices pushing it higher is already consensus — but the direction in which core CPI deviates from expectations. 0.2% would correspond to a continuation of holding rates steady in October, while 0.3% would correspond to a renewed rise in rate hike expectations. New York Fed President Williams also provided a new anchor on Tuesday, stating that one more rate hike this year would be appropriate and that there is no need to raise rates in 2027, adding that aside from AI and the energy sector, he has not seen broad price pressures. This report will test both directions at once.
1. The Jump in Headline Inflation Is Due to Energy
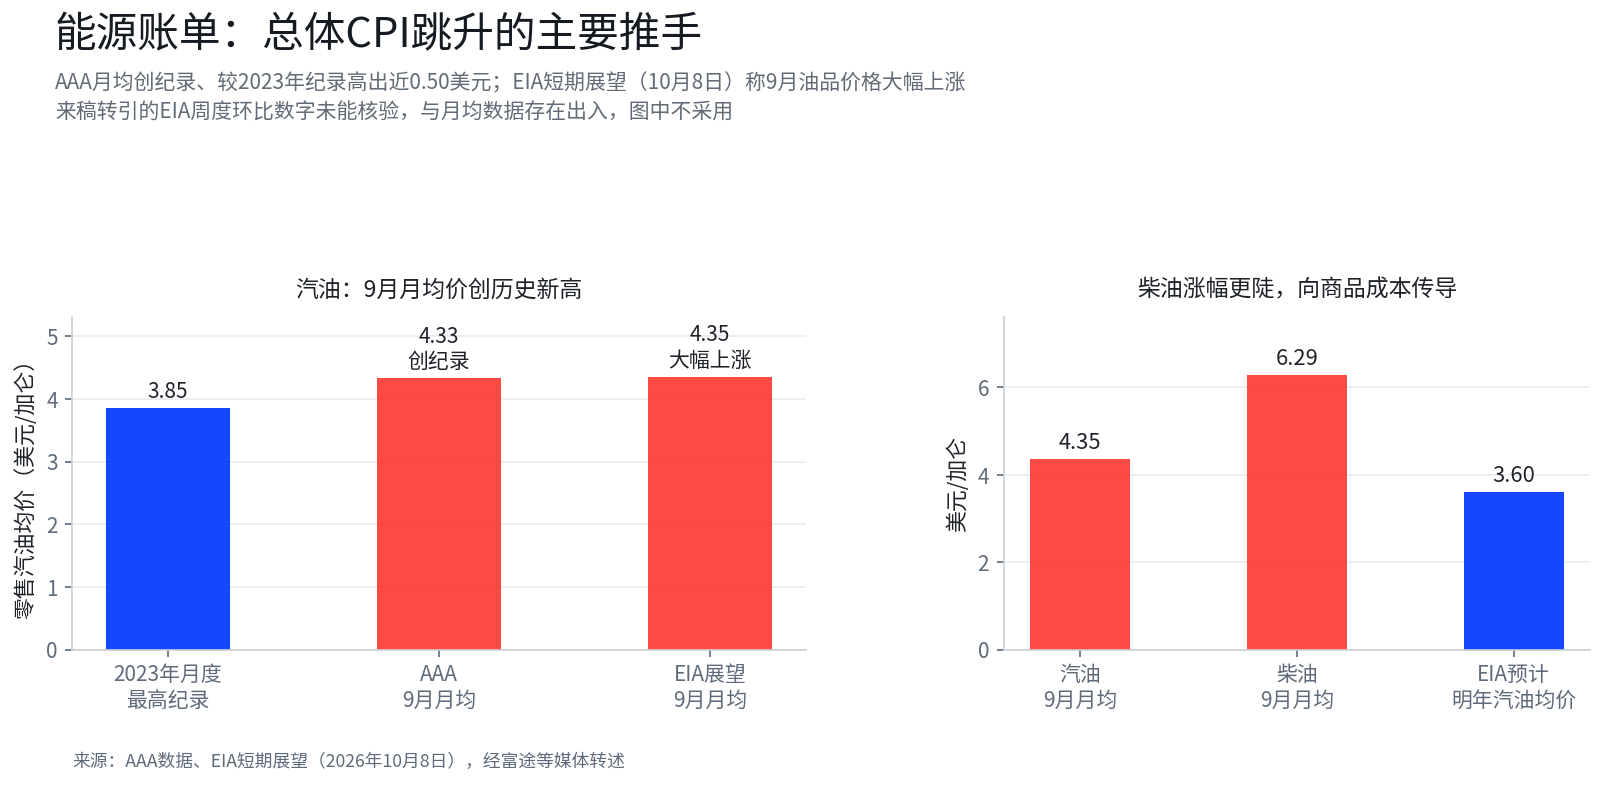
The biggest distortion in the September CPI data came from energy. According to AAA data, the average monthly retail gasoline price in September reached a record $4.33 per gallon, nearly $0.50 above the previous monthly record set in 2023. In its Short-Term Energy Outlook released on October 8, the EIA said U.S. retail gasoline and diesel prices rose markedly in September, with gasoline averaging about $4.35 per gallon and diesel about $6.29, driven by higher crude oil prices and stronger refining margins. The month-over-month increase figures cited in the submission from the EIA weekly survey (about +7.3% month-over-month and +37.6% year-over-year) could not be independently verified and differ from the monthly average data above, so the main text only adopts directional wording. Headline CPI is expected to rise 0.6% month-over-month and climb to about 3.6% year-over-year, which is the market's consensus pricing for the energy shock.
The jump in energy is not the core issue. Bank of America economist Stephen Juneau's view is that if core inflation comes in at 0.2% month-over-month, market expectations for a rate hike will not rise significantly. If it reaches 0.3%, it could reignite speculation that the Fed needs to continue tightening in October (as relayed by Futu).
2. Three Reasons for a Slowdown in Core Inflation, and Three Counterarguments
The baseline expectation is a 0.2% month-over-month core reading, a slowdown from 0.3% in August. The support comes from three areas.
First, a technical pullback in wireless telephone service prices. August core CPI exceeded expectations, mainly because wireless telephone service prices surged 5.9% month-over-month, contributing about 0.10 percentage point on its own. Nomura believes this temporary shock will fade markedly in September and forecasts a September core month-over-month reading of 0.227%, while also flagging continued upward pressure from airfares, healthcare, and housing (as relayed by Futu).
Second, housing inflation is leveling off. According to public reports, the housing sub-index is the largest single component of CPI (with a weight on the order of about 35%; the submission's 35.3% could not be independently verified). Barclays forecasts September owners' equivalent rent at 0.24% month-over-month and primary residence rent at 0.23%. Morgan Stanley forecasts the two at 0.25% and 0.20%, respectively, and notes that since May, housing inflation has averaged about 0.24% per month, slightly below the pre-pandemic long-term trend of about 0.26%.
Third, core goods lack upward momentum. Barclays and Morgan Stanley forecast that September core goods will hold in a range of 0.13% to 0.14% month-over-month, roughly flat versus August. Morgan Stanley forecasts a 0.20% month-over-month decline in September auto insurance premiums, with negative growth potentially continuing into 2027 (as relayed by media). The slowing pace of core goods gains indicates that this round of upside was mainly driven by a localized energy shock, and its spillover into core consumer goods and services remains limited.
The counterarguments are equally specific. The team of RBC economist Mike Reid believes the likelihood of a marked slowdown in core inflation is limited, and if core remains elevated for a second consecutive month, the possibility of an October rate hike could emerge again. The upside risks listed in the Futu report include airfares, hotels, auto parts, and the recent sharp rise in diesel prices feeding into goods costs. CIBC chief economist Shenfeld expects core month-over-month at 0.3% and believes a rate hike will come this month, citing the reason that "there are still too many categories growing at a pace above 3%."
3. The Fork Between 0.2% and 0.3%: Where Does the Market Stand?
CME FedWatch shows that traders currently see about a 77% probability that the Fed will keep rates unchanged this month, compared with about 51% a month ago (as relayed by Futu, October 14 data. The submission's 17% probability of a rate hike differs from this statistic, so the main text adopts the roughly low-20s figure corresponding to 77%). The market has now priced in a cumulative three rate hikes including September (as relayed by Futu). Investment banks' path assessments are also layered. Piper Sandler's Kurt Lewis expects the Fed to raise rates three times in total before reassessing the inflation outlook. Stifel's Lindsey Piegza believes at least three to four more rate hikes are needed to bring inflation under control (this view represents only the relevant institution's judgment). Williams' remarks on Tuesday serve as an anchor in the opposite direction: one more hike this year is appropriate, no further tightening is needed in 2027, and the labor market is showing no signs of driving inflation.
4. Policy Background: The Minutes Wrote Energy and AI into the Causes of Inflation
The September meeting minutes (released October 7) show that all 19 officials supported raising rates by 25 basis points to 3.75%-4.00%, the first rate hike since July 2023. Most participants believed that further increases in the target range later this year could be appropriate, while emphasizing an open stance toward each meeting. The minutes noted that ongoing geopolitical conditions are pushing up crude oil and refined product prices, and that the surge in AI-related investment has also intensified inflationary pressure. Fed staff raised their inflation forecasts for 2026 through 2028, projecting inflation returns to 2% in 2029, a one-year delay from the July forecast. Several officials observed that the impact of AI buildout appears to be strengthening, while the impact of tariff increases is weakening. Some officials also believed that the current level of interest rates is only mildly restrictive. Put together with Williams' dovish remarks, these statements indicate that the Fed's internal disagreement centers on the pace rather than the direction, and tonight's core CPI is the next input variable in that disagreement.
5. Three Numbers to Watch Tonight
First, where core CPI month-over-month sits relative to 0.24%. At 0.2% or lower, cooling rate hike expectations would give high-valuation assets some breathing room. Above 0.25%, expectations for a December rate hike could rise, and long-end yields could retest prior highs.
Second, the month-over-month reading for the housing sub-index. If OER and rents continue to come in around 0.2% to 0.25%, the baseline path for core inflation will not be broken. If they move higher again, the narrative of a core slowdown will need to be re-examined.
Third, core services prices. August core services growth was about 3% (according to reports), and price increases in services tend to persist for months; their trajectory reflects inflation stickiness better than headline CPI. Thursday's PPI is also used in the Fed's preferred core PCE calculation, and the two data releases will enter the input list for the October 28 meeting together.
Taking the market picture and public information together, one possible scenario is a high headline reading with core in line with or close to expectations, allowing the pricing for holding steady in October to continue. If core lands on the 0.3% side, the consensus on pace adjustment will need to be reassessed.
Data Notes
- CPI expectations: Bloomberg survey as relayed by Futu, statistics before release on 2026/10/14.
- Energy prices: AAA monthly average prices, EIA Short-Term Energy Outlook (October 8). The EIA weekly survey month-over-month figures in the submission could not be independently verified and differ from the monthly average data.
- Sub-index forecasts: Barclays, Morgan Stanley, Nomura, RBC, CIBC, and Bank of America are research reports or economist statements relayed by media.
- Meeting minutes and officials' remarks: September FOMC minutes (released October 7) and Williams' Tuesday remarks, as relayed by media.
- Rate hike probabilities: CME FedWatch as relayed by Futu, October 14 data.
Disclaimer:
This content is for general informational and market commentary purposes only, based on public information available as of the time stated in the article, and the relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other persons cited in the article represent only the views of the relevant third parties at a particular time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, and should not be relied upon as the basis for any investment decision. Financial markets involve risk, securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Investors should independently assess the relevant risks based on their own circumstances and seek professional advice when needed. BIT's Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted jurisdictions.