Meta Earnings Analysis: Free Cash Flow Turns Negative for the First Time as Zuckerberg's AI Gamble Accelerates


- Core View: Meta's Q3 earnings, with revenue beating expectations and the initial monetization results of its AI assistant Muse, temporarily eased market concerns about returns on AI investment. However, free cash flow turning negative for the first time and a significant upward revision to capital expenditure reveal Zuckerberg's long-term high-stakes bet in the AI race—"trading profit for growth."
- Key Elements:
- Q3 revenue reached $64.6 billion, up 26% year-over-year; ad unit prices rose 14% year-over-year; excluding $9.89 billion in legal settlement costs, EPS was approximately $7.40, far exceeding market expectations of $6.08–$6.54.
- Six weeks after launch, the AI assistant Muse has seen over 10 million users in North America create agents, with 25% converting to daily active users; more than a quarter of users made actual purchases, with an average order value exceeding $200.
- Q3 capital expenditure reached $34.91 billion, with the first three quarters totaling $83.06 billion—nearly double—and free cash flow came in at -$2.12 billion, turning negative for the first time since going public.
- The lower bound of the 2026 capital expenditure guidance was raised from $130 billion to $135 billion, and the company announced the addition of non-voting Class C common stock, reserving instruments for future financing and equity incentives.
- Reality Labs posted a quarterly loss of $4.13 billion, and the CFO provided a clear timeline for stopping the bleeding: narrowing to $18–19 billion in 2026 and reducing to approximately $15 billion in 2027.
- Total headcount shrank 15% year-over-year to 66,775, but R&D expenses surged from $40.24 billion to $59.41 billion in the first three quarters, with resources concentrated on AI compute and top researchers.
Original | Odaily (@OdailyChina)
Author | Azuma (@azuma_eth)
Amid the gathering clouds of an "AI confidence crisis," Zuckerberg was the first to give the market some reassurance.
Over the past few weeks, doubts have been mounting over the tech giants' massive AI investments that have yet to prove commercial returns, and chip stocks and Nasdaq tech stocks have also gone through a clear round of correction.As the first trillion-dollar tech giant to "turn in its paper" this earnings season, Meta's Q3 2026 earnings report, released after the U.S. market close on October 21 Eastern Time, became the first major test of the commercial viability of AI.
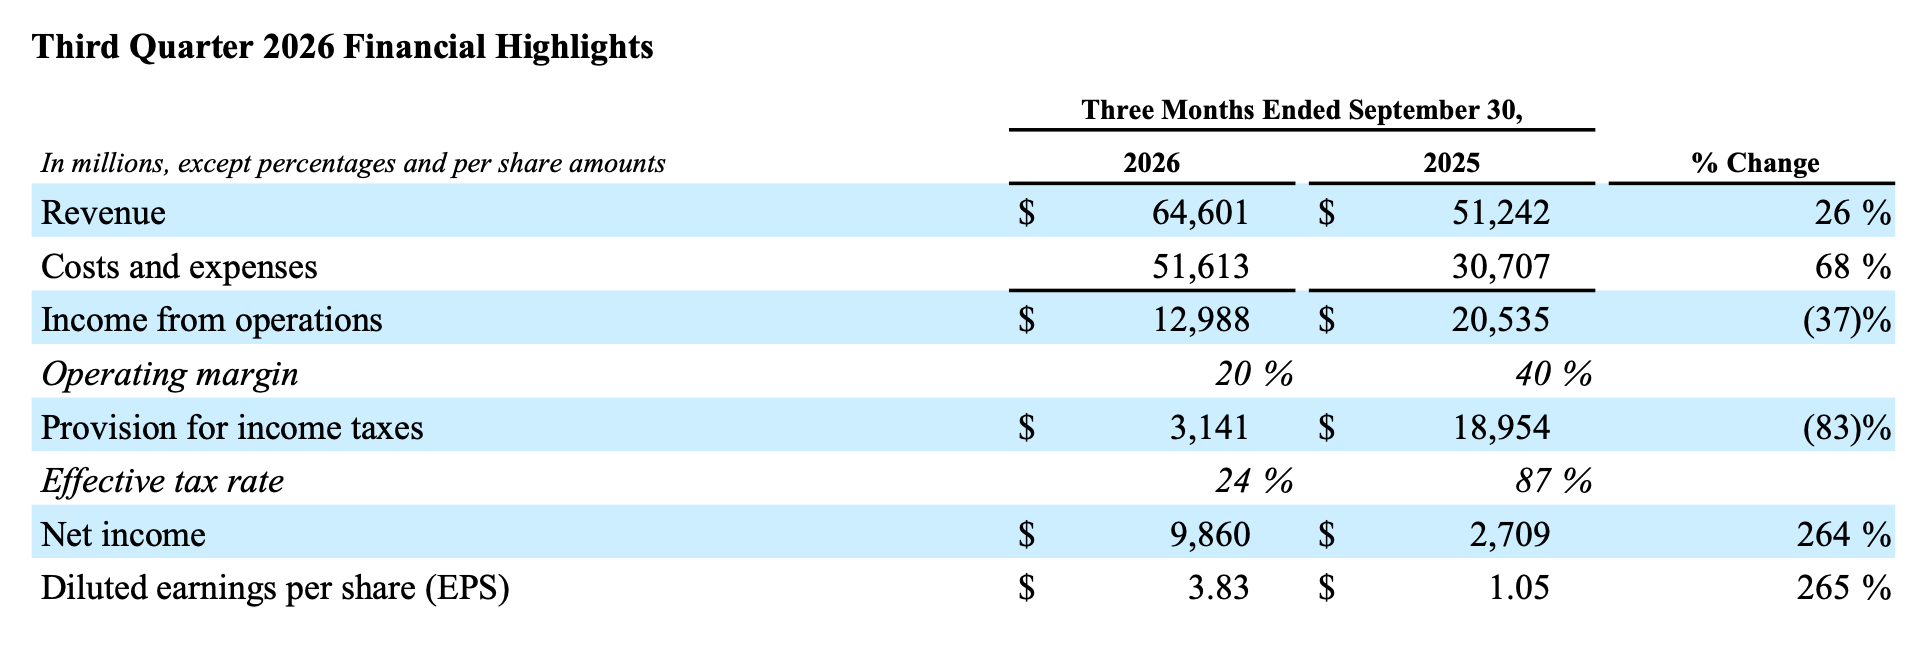
The earnings data show that Meta's Q3 revenue reached $64.6 billion, up 26% year-over-year, beating analysts' expectations of $63.3 billion; the company expects Q4 revenue to reach $73 billion to $76 billion, with the midpoint of the range also above market expectations. Judging from the market reaction, this report card has temporarily passed muster — with both quarterly revenue and Q4 guidance beating Wall Street expectations, Meta's after-hours share price rose as much as 6% (it has since pulled back to 2%).
But if you look carefully at the underlying details of this earnings report, you can't help but feel a strong sense of contradiction. On one side, there is quarterly revenue of $64.6 billion, a steadily growing advertising business, and the AI assistant Muse, which attracted more than 10 million North American users within a month and a half of launch; on the other side, the company's free cash flow turned negative for the first time since its IPO, it booked nearly $10 billion in legal settlement charges in a single quarter, its full-year capital expenditure guidance was further raised, and Meta even announced a new Class C common stock plan to reserve room for future financing and equity incentives.
Taken together, these developments sketch out Meta's current situation — the existing business is still providing ample revenue and cash flow, but Zuckerberg is clearly not satisfied with that. He is directing more resources toward AI and arranging funding in advance for a race whose investment cycle may be longer.
Uncovering the Illusion of "Halved Profits": The Advertising Money Printer Is Still Roaring
Let's start with the income statement, which is most prone to misinterpretation.
Meta's Q3 total costs and expenses rose 68% year-over-year to $51.61 billion, significantly outpacing the 26% revenue growth; GAAP operating income fell 37% year-over-year to $12.99 billion; and the operating margin dropped from 40% in the same period last year to 20%.

Looking at these numbers alone, it's hard to call this a pretty income statement. However, the profit decline was mainly affected by a one-off charge — in August this year, Meta reached a settlement with the attorneys general of 52 U.S. states and territories over lawsuits related to teen mental health and social media addiction. According to the materials cited in the original text, this arrangement involves potential payments of up to approximately $18.59 billion over the next ten years.Meta booked a one-time legal settlement charge of $9.89 billion in Q3, recorded in general and administrative expenses (G&A).
Excluding this non-recurring expense, Meta's operating income for the quarter would be approximately $22.88 billion, and diluted earnings per share would be approximately $7.40, significantly higher than the reported $3.83 and also above Wall Street's prior expectation range of about $6.08 to $6.54.
What supports this real profitability is still Meta's unshakeable advertising foundation. In Q3, Meta's total revenue reached $64.6 billion (up 26% year-over-year), above market expectations of $63.3 billion; of this, advertising revenue from the Family of Apps (FoA) contributed $63.06 billion, also up 26% year-over-year.What reassures investors even more is the internal structure of advertising growth — "both volume and price rising."
- Impressions: Ad impressions across all apps rose 10% year-over-year, and Family Daily Active People (DAP) reached 3.64 billion (up 3% year-over-year);
- Average price per ad: The average price per ad surged 14% year-over-year.
In a macro environment full of uncertainty, a 14% increase in average ad price is quite valuable. This directly confirms the positive cycle of Meta's massive compute investment over the past two years in recommendation algorithms and automated advertising tools (such as Advantage+, whose annualized revenue run rate has exceeded $75 billion) — AI has substantively raised ad conversion rates and advertisers' ROI, allowing Meta to continue to have strong pricing power in an era when social traffic has peaked.
At the same time, Meta's Q4 revenue guidance is as high as $73 billion to $76 billion (midpoint $74.5 billion, corresponding to about 24% year-over-year growth), once again firmly beating Wall Street's consensus expectation of around $73.7 billion, proving that advertising demand during the year-end holiday shopping season remains extremely strong.
The Second Curve Breaks Through: Muse Brings a Glimmer of "AI Monetization"
If the advertising business proves the power of AI in "improving efficiency of existing operations," then Muse, the AI personal assistant launched just in September, has given Wall Street its first glimpse of Meta's monetization dawn in "incremental AI-native applications."
On the earnings call, Zuckerberg could hardly contain his excitement about Muse and Muse Wonder, the underlying frontier model just released last week.Judging from the core operating data disclosed, Muse is helping Meta complete the narrative shift from "AI money burner" to "AI monetizer."
- User growth and stickiness: Within just a month and a half of launch, more than 10 million users in the U.S. and Canada have created Muse personal agents, of whom about 25% converted into "daily active users" (DAU), and the early retention curve has become increasingly solid with longer usage time.
- Breaking the curse of "chatting without making money": Unlike many large-model applications that remain at the Q&A level, shopping has become Muse's largest use case so far. Zuckerberg revealed that more than a quarter of Muse users have made actual purchases on the platform, with an average order value (AOV) exceeding $200. Combined with the two subscription tiers of $20 and $100 per month officially launched in mid-October, Muse has dual monetization potential of "subscription + e-commerce referral commissions."
- Software-hardware integration and B2B expansion: Starting next month, Muse will officially launch on Meta's smart glasses, becoming the core of its hardware business model; on the enterprise (To B) side, CFO Susan Li explicitly stated that the company will charge developers for access to the foundation model and the Muse Code coding agent, and will gradually build a "Muse business agent network" serving small and medium-sized enterprises.
Of course, concerns remain. Currently, dozens of external websites, including Amazon, have blocked Muse's access out of consideration for data security and commercial competition, which to some extent limits the smoothness of its cross-platform price comparison and shopping, but the cost roadmap Zuckerberg laid out is still highly enticing — Muse's compute cost efficiency is expected to improve 10-fold within the next year, and it is expected to become a highly profitable business within the next few years.
The Aggressive Capital Bill: $34.9 Billion Spent in a Single Quarter, Cash Flow Turns Negative for the First Time
Turning to the flip side of the earnings report, the price Zuckerberg has paid for this AI gamble is equally staggering.
In order to seize a position in the compute arms race with OpenAI, Anthropic, and Google, Meta's capital expenditures in Q3 (including principal repayments on finance leases) reached as high as $34.91 billion, and cumulative purchases of property and equipment in the first three quarters reached $83.06 billion, nearly double the $48.31 billion in the same period last year.
Such a terrifying pace of cash burn directly led to a historic financial inflection point — although Meta's Q3 operating cash flow reached as high as $32.79 billion, after deducting capital expenditures, its free cash flow came in at -$2.12 billion (compared with $10.63 billion in the same period last year), marking the first time Meta's free cash flow has turned negative since its IPO.
Even so, Zuckerberg has no intention of hitting the brakes at all. In the earnings report, Meta raised the lower bound of its full-year 2026 capital expenditure guidance from $130 billion to $135 billion (narrowing the range to $135 billion-$145 billion), and explicitly stated that it will continue to "invest aggressively" in 2027.
With operating cash flow tightening and long-term debt balance having climbed from $58.74 billion at the end of last year to $80.92 billion, where will the hundreds of billions of dollars in compute funding come from in the future? Meta gave the answer in its Q3 earnings report — new Class C common stock.
According to the plan announced by the company, Meta will distribute Class C shares to existing Class A and Class B common stockholders on a 1:1 basis, with the arrangement expected to take effect on January 19, 2027. Since Class C shares carry no voting rights, this plan distinguishes between economic interest distribution and company control. For Meta, this arrangement has at least three implications.
- First, it provides more options for future equity financing and M&A. As AI infrastructure investment continues to increase, Meta needs to consider not only how to increase capital expenditures, but also how to strike a balance among cash, debt, and equity financing. Adding a new class of non-voting shares can provide a tool for future financing and equity incentives.
- Second, it helps maintain the existing control structure. Meta's Class A shares carry 1 vote per share, and Class B shares carry 10 votes per share. Creating non-voting Class C shares means the company can, to some extent, expand the scope of using equity tools without having to simultaneously change the existing voting arrangements of current shareholders. This is especially important for Zuckerberg, who wants to continue to hold tight control of the company.
- In addition, to support the new share plan, the board of directors and Zuckerberg signed a "Founder Alignment Agreement." Previously, affected by the potential multi-billion-dollar tax burden of the "California wealth tax" (Proposition 40), the market had rumors that Zuckerberg might leave California. Through this capital structure restructuring and the design of sale provisions, Zuckerberg has also committed to remaining in his post and staying in California for the next eight years.
It should be emphasized that creating Class C shares does not mean Meta has already decided to raise its next round of AI funding through large-scale issuance, nor can it be directly equated with the company being about to face a funding gap. It is more like preparing a financing tool in advance; as the scale of investment grows, Meta wants to keep more options open for the future.
This plan also reveals another signal — the AI race may not just be a few quarters of heavy investment, but a long-term campaign that will require many years and advance planning of the capital structure.
Strategic Maneuvering: Cutting the Metaverse, Reducing Headcount, Everyone All In on AI
In order to free up more resources for AI, Meta is also adjusting its internal business and organizational structure.
First, the metaverse division (Reality Labs), which has continued to drag on operations, will officially face a strategic contraction. In Q3, Reality Labs revenue was $443 million, with an operating loss of $4.13 billion (cumulative losses in the first three quarters have reached $13.17 billion). Unlike the previously vague statements of "losses peaking," the CFO rarely gave a clear "stop-the-bleeding timetable" in this earnings outlook: full-year 2026 Reality Labs losses are expected to narrow to $18 billion-$19 billion, and by 2027 the loss will be further sharply reduced to around $15 billion. The billions of dollars in budget saved are expected to be reallocated to AI projects centered on Meta Superintelligence Labs (MSL).
Second is the "reshuffling" of the organizational structure. As of September 30, 2026, Meta's total headcount had dropped to 66,775, a sharp 15% year-over-year reduction (down about 12% quarter-over-quarter). However, while headcount was significantly streamlined, Meta's R&D expenses in the first three quarters soared from $40.24 billion in the same period last year to $59.41 billion —behind the scissors gap of "headcount falling, R&D surging" is the large-scale layoff of ordinary positions, while resources are being concentrated with unprecedented density into sky-high AI compute and top large-model researchers.
The Earnings Report Has Passed, but the Return on Investment Still Needs Time
Overall, with a Q3 earnings report featuring strong revenue and optimistic guidance, plus Muse's impressive start of breaking 10 million users, Meta successfully won the first defense battle in Wall Street's "AI confidence crisis." The after-hours share price gain proves that as long as the core advertising money printer is still roaring and new AI products show real transaction conversion, the market is still willing to tolerate a short-term negative free cash flow.
But this does not mean the alarm has been completely lifted. With full-year total expense guidance raised to $175 billion to $179 billion, and regulatory clouds far from dissipating, Meta does not have much room for error going forward.
When hundreds of billions of dollars in capital expenditures translate into massive financial depreciation in 2027, and the financing expectations for Class C shares officially materialize, can the incremental revenue brought by Muse and AI advertising truly outrun the exponentially expanding compute bills? Zuckerberg's gamble will sooner or later have to answer this ultimate question.